Key Takeaway
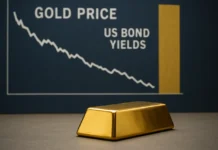
- 📊 The gold price forecast spread: spot gold trades ~$4,150 (Oct 5) while JPMorgan’s standing forecast is $6,300 by end-2026 — a $2,150 gap on the same asset, both sides on record. Somebody is very wrong; finding out who is the investor’s work this quarter.
- 🏦 The bull case: JPMorgan raised its target from $5,055, forecasting 800 tons of central-bank gold purchases in 2026 on an “unexhausted” reserve-diversification trend; Deutsche Bank stands at $6,000.
- 🧱 The bear case: the yield wall — 10-year Treasuries near 5.3% and the dollar index at 18-month highs around 102 — pays holders paper instead, and it has been the price ceiling all year.
- 🇵🇭 The local layer: Manila opens Monday into the biggest liquidity week of the quarter — GCash’s ₱92-billion IPO: final price ₱6.60, firm orders due Oct 8, DragonFi early lane open until Oct 7 (3 p.m.), official window Oct 6–12, listing Oct 20.
Every few years, one market produces a forecast gap so wide it becomes a teachable artifact. This quarter’s is the gold price forecast ledger itself: the street’s most influential bull — JPMorgan — has a standing year-end forecast of $6,300 per ounce, while the metal itself trades around $4,150 as Manila wakes Monday. That is a 52% disagreement between the biggest banks’ research desks and the price tape, in real time, on an asset the entire world pretends to understand. This week’s World Investment Watch takes the gap apart — who is right is less knowable than what each side is betting on, and what a Filipino investor should DO while two trillion-dollar viewpoints argue.
The Gold Price Forecast Tape: Who Says What, and Who Has to Answer in December
Today’s gold price forecast ledger — the standing commitments every investor tracks — reads like this. JPMorgan, $6,300 by end-2026 — a call on record since early in the year, raised from $5,055, resting on structural arguments: central-bank reserve diversification that the bank calls “a clean, structural, continued diversification trend that has further to run amid a still well-entrenched regime of real asset outperformance vs paper assets,” with central-bank purchases forecast at 800 tons for 2026 (the Reuters-cited note). That note was reaffirmed in the October tape, when the same house cited central-bank and investor demand pushing toward the year-end target. Deutsche Bank’s $6,000 gold price forecast — reiterated despite volatility. And the skeptics’ floor argument lives in the year’s own history: gold suffered its sharpest one-day drop since 1983 back in January (−9.8% in a single session, with exchange margin hikes adding pressure) — proof that this trade’s volatility is structural, not incidental.
The discipline an investor owes this ledger: forecasts are dated commitments, not schedules. JPMorgan’s number says where the house expects the year to END — it does not promise the path, and it has absorbed a 26% January-to-October drawdown from the year’s peaks without withdrawing. Reading both the gold price forecast numbers with a date attached is what separates a research consumer from a headline victim.
Why the Tape Says $4,150 While the Street Says $6,300
Walk the two bets behind the gold price forecast gap to their engines. The bulls bet on the buyer: central banks (800 tons, mostly the non-Western reserve managers steadily converting dollar exposure), plus a retail-investor base hedging fiat erosion. Theirs is a flow argument — physical demand at a scale that eventually overwhelms paper pricing. The bears bet on the alternative: cash that PAYS. A 10-year Treasury yielding ~5.3% (two-decade highs) and a dollar index near 102 (an 18-month peak) make the “do nothing” trade genuinely lucrative — every peso parked in yield-bearing paper competes directly with the yellow metal, which pays nothing while it waits. That yield wall has been gold’s gravity all year (our Investment Watch #010 mapped it), and it explains why the metal sits 26% below January’s $5,608 peak even with central banks buying: the flows fight the yields, and so far the yields have held the tape.
Both cases can even be right at once — path dependence is the reconciliation. Gold can average $4,800 across 2026 and still print $6,300 in a December breakout; or the December print never comes and the central-bank thesis simply needed more time. The investor question is therefore not “who wins” but “what would confirm each side, and how early?” The confirmation instruments are public and free: quarterly World Gold Council demand data (did the 800-ton pace hold?), ETF flow prints (Western investors returning or fading?), and the real-yield direction (yields falling = the wall melting = the bull case igniting; yields rising = gravity continues).
Manila Monday: the ₱92-Billion Week the Local Tape Was Waiting For
While the world argues about the gold price forecast, the Philippine tape has its own spectacle: the week the GCash IPO finally opens. The verified map as of Monday: the offer period runs October 6–12, with GStocks in-app buying live from midnight Oct 6 and an early-subscription lane on DragonFi running until 3 p.m. Oct 7 — ahead of the official window. Final price: ₱6.60, announced Oct 1. Firm orders are due October 8 — the institutional book-sealing date, which makes the middle of this week the real test of demand. The deal’s size: roughly ₱92 billion, with HSBC and CLSA added late to the global bank syndicate — a stamp of international sponsorship this market rarely sees in domestic deals. Listing: October 20 on the PSE, ticker GCASH. Our buy-window drill carries the step-by-step, and PSE Watch #011 has the tape mechanics — the ₱53-billion estimated liquidity queue and the 5,600 band the index must hold while the market digests a giant.
What This Means for the OFW Portfolio: Two Vaults, One Decision Map
The practical synthesis this week is a two-tranche map, and it is genuinely this simple:
- Tranche 1 — the growth allocation (the GCash week): a Filipino professional buying GCASH at ₱6.60 is buying the country’s everyday-money rails — payments, credit scoring, a super-app with nine-figure users. It is a growth decision inside one’s home-market exposure, executable from Riyadh through GStocks. Sized within position limits (≤2% for a single name at IPO terms is the standing discipline), it is the highest-conviction NEW allocation window the local market has offered this year.
- Tranche 2 — the hedge allocation (the gold price forecast question): the $2,150 forecast gap is not a reason to buy — it is a reason to define terms. An OFW hedging peso exposure buys gold in tranches regardless of the forecast, because the hedge’s job is not to catch $6,300; it is insurance against the tape’s tail risks. If the forecast ignites, the tranche rewards; if the wall holds under the gold price forecast debate, the tranche still did its insurance job. What the disciplined investor does NOT do is size the gold tranche around a bank’s year-end number.
And the reconciliation rule, in pesos: growth tranche first, hedge tranche monthly. One is an event (this week, with a deadline — Oct 12); the other is a habit (auto-buy a fixed amount, ignore the noise). Confusing the two — treating gold like an event trade or GCASH like insurance — is how the same portfolio ends up owning a lottery ticket with insurance premiums.
The December Reckoning (Our Standing Audit Date)
Forecasts deserve accountability: this franchise has now logged the full gold price forecast ledger — JPMorgan’s $6,300, Deutsche’s $6,000, and the $4,150 starting tape dated October 5. When the year-end numbers arrive, this watch audits the ledger — the house either printed its number or it did not; either outcome teaches. That audit is scheduled into the December edition of this watch, and no reader should act on the spread alone before then. Mountains are patient with forecasts; they simply check the receipts.
The Local Metals Pocket: How the Forecast Gap Reaches a Filipino Wallet
The forecast debate sounds foreign-currency abstract — until the conversion math shows it in pesos and it becomes a local decision. At the standing ~₱59/USD conversion, the gap between the two camps is not an abstraction: $4,150 spot translates to roughly ₱245,000 per troy ounce, while JPMorgan’s $6,300 year-end scenario translates to ₱372,000 — a ₱127,000-per-ounce disagreement. Scale that to the amounts an actual household buys: the 1-gram bahay-level bars sold in Manila shops (the ₱4,500–₱6,000 tier that dominates Bangko Sentral’s reported retail coin demand) embed exactly this same spread bet at retail scale — the buyer at today’s prices is paying the spot camp, and the buyer’s December outcome is whatever the forecast camps prove. The practical Philippine sizing instruments, verified channels and all: BSP-issued gold bars via the Bangko Sentral’s own retail window, bank-sold bullion at the major universal banks, and the PAX/gold-backed token products our #010 watch mapped for those who prefer vaulted digital ounces. What none of these instruments promise is the $6,300 print — what they all deliver is the tranche discipline: peso-cost averaging into metal monthly means the December verdict lands on an AVERAGE position, not a single taped entry.
The local angle widens with the mining tape: the Philippine gold producers riding the LME/Bloomberg metals complex (the sector’s PSE constituents trade the metal’s momentum daily) give equity-market Filipinos their version of the same exposure — with operating leverage that amplifies the metal’s moves in both directions. That amplification is precisely why the equity route is not the hedge itself but the aggressive expression ON the hedge — the same reason we separate the GCash growth tranche from the metal vault in the map above. One instrument per job: the metal for insurance, the miners (if at all) for conviction-sized aggression, the stablecoin-rails innovation covered in our BSP piece for the future where the same discipline rides new rails. The mountains of it all, literally: Philippine geology holds some of the richest gold ground in Asia — the household that buys 1-gram bars monthly is participating in the same metal the national mines export, at an instrument size the sari-sari register can sustain.
The Week’s Ledger in One Paragraph
For the reader in a rush, this week’s positions, dated: gold spot $4,150 (Oct 5) against a $6,300/$6,000 two-bank bull ledger and a yield wall that has ruled since January; GCASH at ₱6.60 with its window open Oct 6–12, firm orders Oct 8, listing Oct 20, the DragonFi early lane closing 3 p.m. Oct 7; the peso at the ~₱59 level that converts the gold gap into ₱127,000 per ounce of disagreement. The audit dates are already in the calendar: the Oct 8 firm-order print (does the institutional book fill?), the Oct 20 listing (does the retail book flip or hold?), and the December forecast reckoning. Every number above is checkable; nothing above requires faith. That is the standard this franchise holds itself to — the same standard, it turns out, the mountain applies to weather: measure it, date it, and never confuse a forecast with a fact.
Frequently Asked Questions
Is JPMorgan’s $6,300 gold price forecast realistic for 2026?
It requires the central-bank buying trend (800 tons forecast) plus Western ETF inflows returning, overpowering the 5.3% real-yield wall that has capped the tape all year. A 52% move in three months is a tail scenario, not a base one — the forecast is a stated conviction with dated accountability, not a schedule.
Why is gold falling if the gold price forecast says rally?
Because the tape prices NOW while every gold price forecast describes LATER. The current $4,150 spot reflects the yield wall (high Treasury yields make non-paying gold expensive to hold), while the bank scenarios describe year-end structural flows. Both can coexist for months.
What does the 800-ton figure in the gold price forecast mean?
It is roughly 8% of annual global mine supply, concentrated in non-Western reserve managers diversifying away from the dollar. Sustained official-sector buying is the strongest structural floor under the metal — and the pillar of every $6,000+ forecast.
Should an OFW buy gold now or wait out the gold price forecast?
Hedge allocations are bought in tranches on a schedule, never timed on any gold price forecast. The monthly auto-buy discipline (a fixed amount, regardless of tape) captures whatever outcome arrives without betting the position on a bank’s December number.
What’s the GCash IPO status as of Monday, October 5?
Offer window Oct 6–12 (GStocks in-app from midnight Oct 6; DragonFi early lane until 3 p.m. Oct 7), final price ₱6.60, firm orders due Oct 8, listing Oct 20 under ticker GCASH. The offer is ~₱92 billion with HSBC and CLSA added to the syndicate.
Gold hedge or GCash shares — which comes first for a small OFW budget?
They are different jobs, not a race: the growth allocation (GCASH this week, event-driven with a deadline) and the hedge (gold, habit-driven) are sized separately per their own roles. Households with tight budgets typically establish the growth position first and build the hedge monthly.
Financial Disclaimer
General information only — not investment advice. Prices, forecasts, and offer terms reflect public disclosures and reporting at writing and change without notice; verify current figures before acting. Securities and commodities carry loss risk; consult a licensed professional before financial decisions.