Key Takeaway
- 🏗️ What AI capex actually buys: three asset classes — accelerators (GPUs/TPUs with 3-6 year usable-life debates), the shells that hold them (land, buildings, power interconnects, cooling), and the energy contracts behind both; the “AI capex” headlines bundle all three into one number.
- 📊 The scale, on record: the four US hyperscalers’ combined annual capital expenditures reached the hundreds of billions of dollars in 2025-2026 — more than the annual GDP of most countries — with guidance still rising into 2026.
- ⚖️ Capex vs opex is the real AI-economics question: capital expenditures buy owned capacity (risky if demand dips), operational expenses rent it (expensive per token but flexible) — the industry’s spend mix is literally a bet on demand durability, and 2026 marked the first year companies spent more running AI than building it (our spending-flip piece).
- 💵 The financing changed too: the buildout moved from cash-flow-funded to debt-and-SPV-funded (special purpose vehicles, vendor financing, lease structures) — read next to our CoreWeave debt-crisis and AI selloff pieces.
- 🔍 How to read it like an analyst: separate committed-revenue-backed capacity (buildings with tenants) from speculative fleets (GPUs betting on demand); ask the depreciation schedule and the utilization behind the guidance — the checklist at the end.
AI capex is the biggest corporate-spending story of the decade: the four US hyperscalers now pour a combined scale of hundreds of billions of dollars a year into the AI buildout — chips, buildings, power — a figure that exceeds the annual GDP of most nations and still rises in guidance. Yet the term gets thrown around as if it were one number. This piece unpacks it: what the capital expenditure actually buys (three asset classes with different risk profiles), why the capex-versus-opex split is the real economics question, how the financing changed, and how an analyst — or a curious professional — should read every “record capex” headline that lands.
Table of Contents
Why this matters beyond the market pages: capex decisions made in 2026 set electricity demand, land markets, hardware pricing and AI-service availability for years — they are the reason your token bill, your GPU rental rate and your utility’s grid planning look the way they do (all traced in the cost pieces on this site).
What AI capex is: the definition and the three asset classes
Definition: capital expenditure (capex) is money spent acquiring or upgrading long-lived physical assets — as opposed to operational expenditure (opex), the recurring cost of running them. “AI capex” bundles three very different asset classes under one headline, and the differences are where the analysis lives.
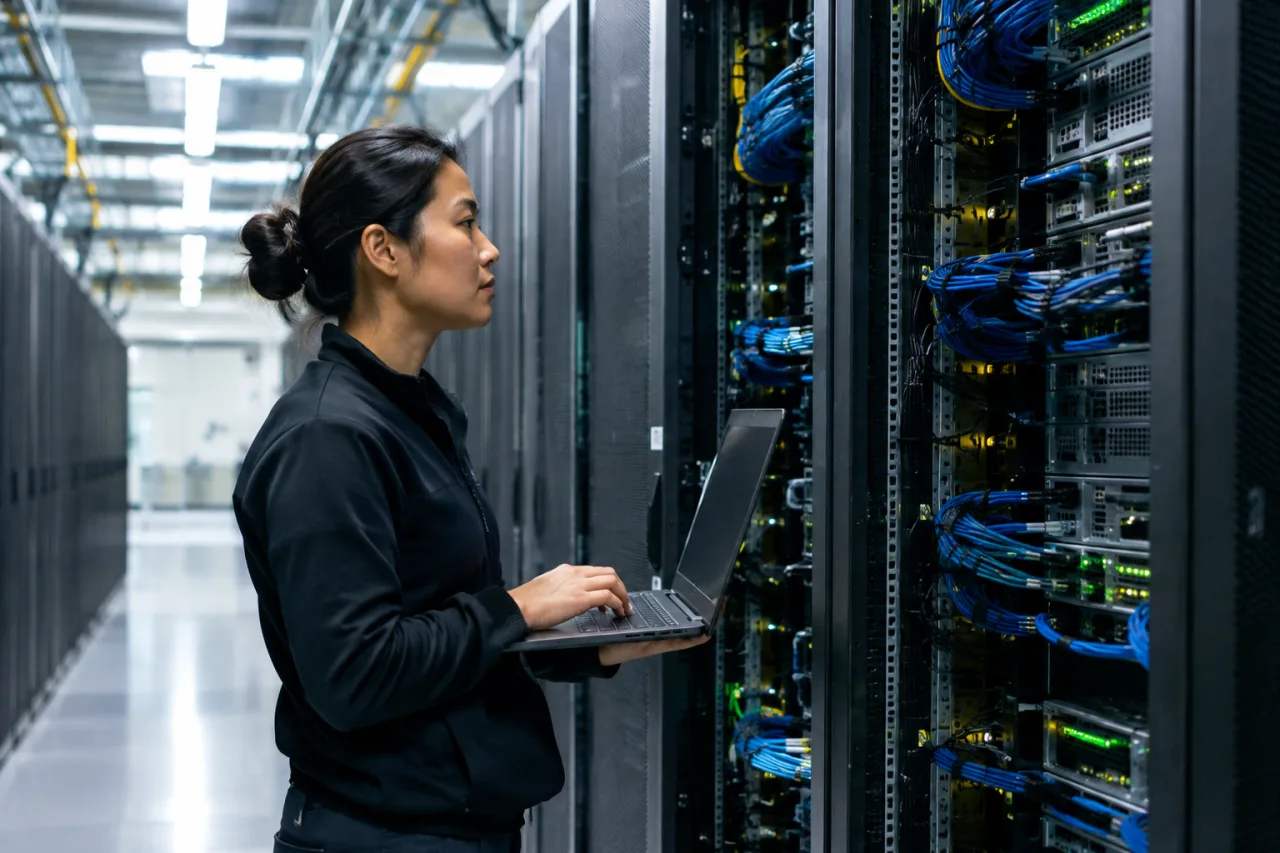
Class 1 — Accelerators: in AI capex terms, the GPUs and TPUs themselves — the fastest-depreciating, most demand-sensitive line. The usable-life debate (how many years a data-center GPU stays profitably deployable while the model frontier moves) is the single most contested assumption in the whole buildout: longer lives justify the spend; shorter ones inflate effective costs. Class 2 — The shells: land, buildings, power interconnects, substations and cooling — long-lived, slow to permit (the multi-year queues our power-pipeline piecetracks), and useful for decades regardless of which accelerator generation fills them. These are the “boring” half of capex and the least reversible. Class 3 — Energy: generation contracts, utility-scale deals — the nuclear PPAs (our nuclear data-center piece), the grid fights, and the consumer-bill disputes (tracked in who-pays-for-AI-data-centers).
Why the classes matter separately: a dollar of accelerator capex can strand in three years if demand dips; a dollar of shell capex serves the next tenant whatever chips come; a dollar of energy capex shapes regional politics. Analysts who price “AI capex” as one number make the exact error the categories exist to prevent.
The scale: why the 2026 numbers broke every chart
The headline numbers: AI capex guidance from Amazon, Microsoft, Google and Meta reached the hundreds of billions of dollars for 2025-2026 — individually, each company’s AI-era capex now runs multiples of its pre-2023 baseline, with Microsoft alone guided above the combined GDP-scale thresholds that made headlines in 2024. The sum matters less than the composition: an increasing share buys accelerators and their power, and the acceleration compressed depreciation schedules that were already aggressive.
Where the AI capex is going physically: the shells — new data center campuses across the US (the backlash maps track where cities are pushing back), Southeast Asia’s race (our Malaysia pieces), and the Philippine tier (the 500-MW buildout). The capex wave is globalizing even as the accelerator purchases concentrate in the US mega-campuses.
Capex vs opex: the AI economy’s defining split
The two postures: capex-heavy players (the hyperscalers, the sovereign programs) own their capacity — best economics at utilization, but the risk sits on their balance sheet if demand dips or accelerators turn over faster than depreciated. Opex-heavy players (AI startups, most enterprises) rent — paying the per-hour premium our GPU rental index prices, in exchange for flexibility.
The 2026 milestone that reframed the debate: for the first time, companies spent more running AI than building it — inference spending overtook training-and-build capital (our spending-flip piece carries the numbers). That flip matters because it changes whose risk dominates: the buildout-era question was “will demand justify the shells?”; the inference-era question is “will the running costs clear their price?” — and the capex crowd now depends on the opex crowd’s sustained willingness to pay (the selloff pieces track what happens when that confidence wobbles).
The small-player translation: the capex/opex choice is the same arithmetic at every scale — a team deciding between a local rig and the cloud is running the identical capex-vs-opex analysis as a hyperscaler, just with four zeros fewer. The break-even math is the person-scale version of this entire section.
The financing shift: from cash flow to debt and SPVs
The old model: hyperscalers funded data centers from operating cash flow — slow, self-insured, balance-sheet visible. The new layers: special-purpose vehicles that hold assets off the primary balance sheet; vendor financing (chipmakers effectively financing their own customers’ purchases); lease-back and debt structures at the neoclouds (CoreWeave’s model — the debt-crisis piece is the stress test); and, at the edge of the practice, circular-revenue arrangements that drew the selloff’s hardest questions about demand quality.
Why the financing matters to non-investors: financing structure sets behavior — debt-funded capacity must run hot to service its loans, which shows up as utilization-maximizing pricing (the neocloud rate advantage), aggressive customer acquisition, and — at the tail — distressed-discount capacity if the cycle turns. The buyers’ lesson: today’s favorable rental rates are partly a financing artifact; price commitments with an eye on the counterparty’s leverage, not just the rate card.
The bubble question: what would validate or pop it
The validate case: sustained inference-revenue growth clearing the buildout’s running costs; committed-revenue-backed capacity absorbing supply (the contract backlogs the market cheered); utilization staying high through the depreciation schedules. The pop case: a demand plateau or an efficiency shock (models that need less compute per answer — the test-time-compute economics cut both ways: more thinking tokens per answer raise demand; more efficient models lower it), accelerator turnover faster than depreciation (the usable-life debate swinging short), or financing markets repricing the leverage under the fleets.
Both cases run on the same observable: utilization. The bubble debate resolves the moment real-world utilization data separates committed capacity from speculative fleets — which is why the checklist below reads filings and contracts before headlines.
How to read capex guidance like an analyst
Five questions turn any AI capex headline into analysis, in order. 1 — What mix? How much of the guidance is accelerators versus shells versus energy? (Shells appreciate across chip generations; accelerators may not.) 2 — What backs it? Committed customer revenue, or faith in demand? Contract-backed capacity and speculative fleets price differently in every stress scenario. 3 — What depreciation schedule? The usable-life assumption silently sets reported margins; a lengthened schedule flatters earnings today and defers the reckoning. 4 — Who finances it? Cash flow, debt, SPVs, vendor financing — each changes who bears the downside (the CoreWeave chapter again). 5 — What utilization evidence? Any published fleet-utilization or inference-growth data beats the guidance narrative — our spending-flip and cost-formula pieces are the reader’s instruments.
WorldNgayon Insight: capex is a demand bet, not a spending habit
The headline error in AI-capex coverage is treating the spend as evidence of demand. Capex is a bet ON demand — placed years before the demand data exists, financed increasingly with instruments that amplify both sides. The disciplined read separates three things the headlines blur: what was bought (the three asset classes), why it was financed that way (the leverage story), and what revenue would have to exist for the bet to clear (the utilization question). Readers who keep those three sorted can walk into any “record capex” headline — this year’s or next decade’s — and price it in minutes. That skill, not the headline number, is the actual yield of this story.
What this means for work, money and the Philippines
Budgets and careers: the capex wave is the jobs wave — the data-center roles map prices what a $200M campus employs — and the skills ride the asset classes (power engineering and mechanical trades for the shells; ML-ops and networking for the accelerators). For investors and professionals: read the checklist above before the headlines; separation of the asset classes is the edge most commentary lacks. For Philippine readers: the country’s tier of the story is the shells — the 500-MW buildout, the regional campus entrants and the $500M sovereign-backed entry are the local capex story, and the constraint set (our power-crisis analysis) is the same capex-vs-grid arithmetic at national scale. The practical stance for professionals: the jobs and the buildout are the investable layer; the frontier-capex drama is a watched input, not a hometown fact.
Verdict: price the commitments, watch the utilization
AI capex explained: three asset classes bought at historic scale, on a financing structure that changed the risk, against a demand bet the market grades weekly. The capex-versus-opex split is the economy’s real fork — and the 2026 inference-spending flip moved the pressure onto the running side of the ledger. Price the commitments, watch the utilization, separate the shells from the chips — and every record-capex headline becomes readable in a minute.
Sources on the record: Epoch AI compute data · Microsoft for Startups AI-infrastructure guide.
Two companion numbers complete the scale picture. First, the contract backlog: the buildout’s demand side is partly contracted years forward – the CoreWeave-class backlogs reached the tens of billions of dollars – which changes what the capex means (committed revenue behind shells versus speculative fleets is the difference between a financed buildout and a bet). Second, the rental side: the same dollars show up as hourly rates on the open market, where our 36-rate index put flagship GPU hours at $3.21-3.53 on neoclouds versus about $6.98 on hyperscaler on-demand – the same infrastructure, priced differently by who owns it and how it was financed.
The geography of the spend is the third lens. The accelerator purchases concentrate in a handful of US mega-campuses; the shells globalize – Southeast Asia’s national programs (our Malaysia and Singapore-Johor pieces carry that race) and the Philippine tier (the 500-MW buildout this site tracks) buy the slower assets: land, power contracts, buildings. For a reader pricing exposure to the buildout, that split is the practical map: the frontier-capex drama plays out in the accelerator half, the durable capacity story plays out in the shells – and the two halves rarely make the same headline, though they share the same dollars.
A closing practical note for professionals: the checklist in this piece is also a news-reading tool. Every record-capex quarter will arrive with a mix of guidance, backlog and financing noise; running the five questions takes a minute and separates the buildout’s durable facts from its narrative. The skill compounds: the same five questions will price the next infrastructure wave whatever it is called.
Financial Disclaimer
This article is editorial analysis of publicly reported capital expenditures, guidance and market conditions, not investment or financial advice, and no investment outcome is promised. Capex guidance, depreciation assumptions and market conditions change; verify with filings and named sources before any financial decision. Investing carries substantial risk.
- epoch.ai — Epoch AI compute data
- microsoft.com/en-us/startups/what-is-a-neocloud — Microsoft for Startups AI-infrastructure guide
External sources linked in this article, in order of first mention. Spotted an error or a broken link? Tell us.
Cite this pagePublished Oct 28, 2026
Agron, E. (2026, October 28). AI Capex Explained: What the Billion-Dollar Buildouts Actually Buy. WorldNgayon. https://worldngayon.com/ai-capex/
Agron, Edmon. “AI Capex Explained: What the Billion-Dollar Buildouts Actually Buy.” WorldNgayon, 28 Oct. 2026, worldngayon.com/ai-capex/.
Agron, Edmon. “AI Capex Explained: What the Billion-Dollar Buildouts Actually Buy.” WorldNgayon, October 28, 2026. https://worldngayon.com/ai-capex/.
Agron, E. (2026) ‘AI Capex Explained: What the Billion-Dollar Buildouts Actually Buy’, WorldNgayon, 28 October. Available at: https://worldngayon.com/ai-capex/.
E. Agron, “AI Capex Explained: What the Billion-Dollar Buildouts Actually Buy,” WorldNgayon, Oct. 28, 2026. [Online]. Available: https://worldngayon.com/ai-capex/
@online{agron2026aicapex,
  author       = {Agron, Edmon},
  title        = {{AI Capex Explained: What the Billion-Dollar Buildouts Actually Buy}},
  year         = {2026},
  date         = {2026-10-28},
  organization = {WorldNgayon},
  url          = {https://worldngayon.com/ai-capex/},
  urldate      = {}
}TY - ELEC AU - Agron, Edmon TI - AI Capex Explained: What the Billion-Dollar Buildouts Actually Buy T2 - WorldNgayon PY - 2026 DA - 2026/10/28/ UR - https://worldngayon.com/ai-capex/ Y2 - ER -
Cite the version you read; the page may be updated. Zotero and Mendeley can also import this page directly.