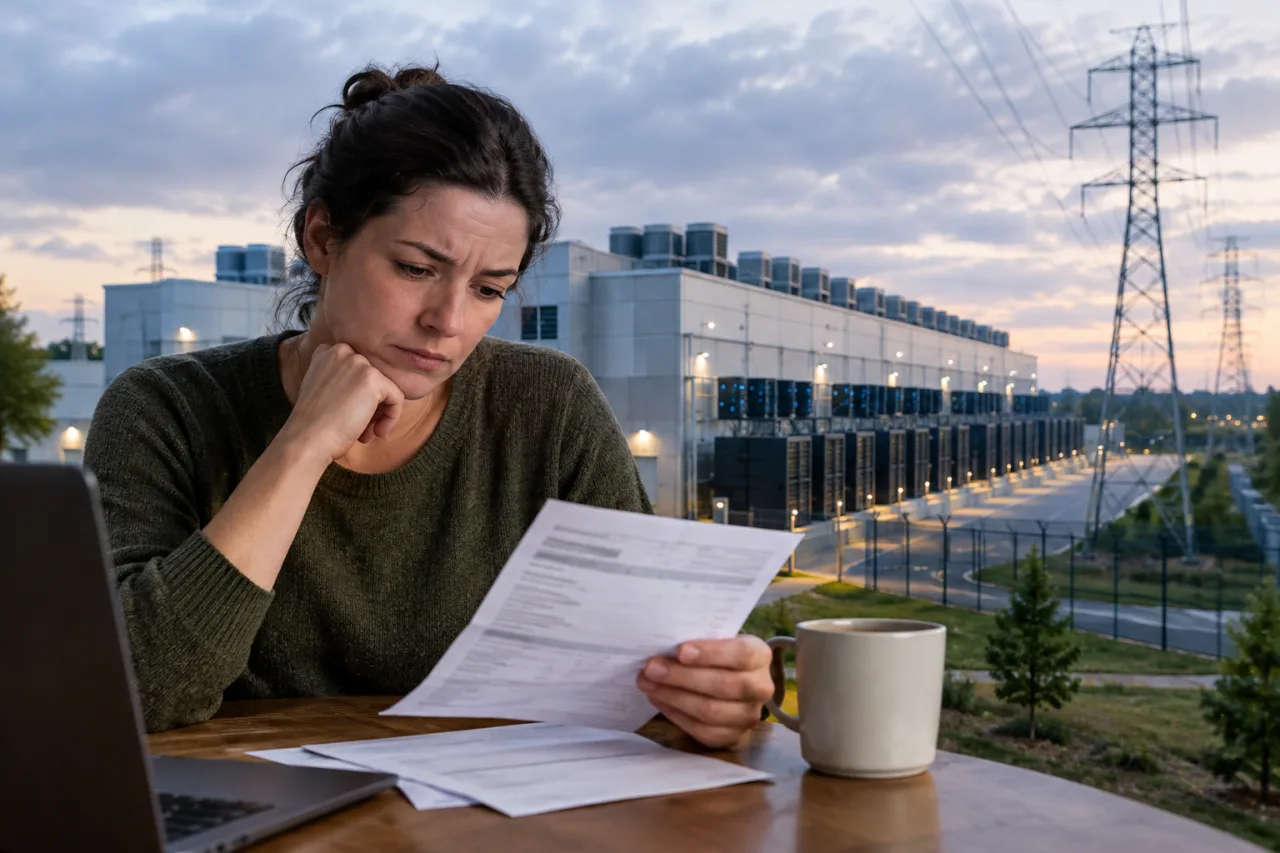
The AI money is private, the AI bill is arriving public – in your utility bill line, if you live anywhere near the world’s data-center boom. This week’s sequence: Consumer Reports published a framework demanding what data centers should do to “pay their own way” – AI data centers “pay their own way,” Illinois’ utility watchdog warned that ComEd customers could pay billions for data-center hookup costs, PJM’s capacity auction quietly repriced the grid everyone shares, Google began piloting the virtual power plant solution, and a CNBC survey put the voter backlash on record – with the White House position that tech companies will “pay for their own electricity use.” The AI data centers cost fight has officially moved from conference slides onto residential electric bills, and the fight over who pays is now the most consequential economics story of the buildout. This guide maps the whole thing: who charges whom, the five mechanisms by which AI data centers touch your bill, the utility-regulator scoreboard, the solutions actually deployed, and where the numbers sit as of today.
Key Takeaway
- The fight formalized: a Consumer Reports paper (released this week) laid out what AI data center rate structures should require; Illinois’ Citizens Utility Board warned ComEd customers could pay billions in data-center hookup costs; the White House says tech will “pay for their own electricity use.”
- The mechanisms are five: capacity-auction pass-throughs (PJM), grid-upgrade riders, rate-class segregation, stranded-asset risk and tax-base shifts – each one is a line item your utility’s next rate case can carry.
- The demand is structural: AI data centers add gigawatt-scale concentrated load – the PJM capacity auction that prices 13 states’ reliability is the mechanism by which the buildout becomes everyone’s bill.
- The solutions shipped: Google’s virtual power plant pilot shows the first utility-scale answer – use the data center’s batteries and flexibility as grid assets rather than only as load.
- The backlash is measured: the CNBC survey has the voter numbers; local moratorium rejections (Trumbull) and project-document hearings (Cromwell) mark the town-level resistance; consumer-protection papers mark the federal-level one.
The debate in one paragraph
Here is the economics in its compressed form. AI data centers concentrate enormous electrical demand – gigawatt-scale campuses drawing power around the clock – and the grid serving them needs generation, transmission and reliability reserves built ahead of that demand. The buildout costs money; utilities recover costs through rates and riders; and the question every regulator now faces is whether the incremental cost of serving AI load is carried by the AI load itself or spread across everyone’s kWh line. The AI data centers consumer-cost question landed on residential bills this cycle because utility-watchdog groups did the arithmetic and regulators started listening: Consumer Reports’ paper this week formalized the consumer-protection argument, Illinois’ Citizens Utility Board put a “could pay billions” estimate on the state’s flagship utility, PJM’s capacity auction – the market mechanism serving 13 states – repriced with load growth as the driver, and the political dimension got a survey and a White House line. Whoever wins the argument sets the actual number on next winter’s bill.
The five ways your bill touches their buildout
The mechanics, numbered so you can spot them in your own utility’s next rate filing:
- Capacity-auction pass-throughs. Regional grid operators (PJM runs the one covering from Illinois to Virginia) hold annual auctions to line up enough generating capacity for the years ahead. When data-center load growth raises the demand forecast, the auction clears higher – and the capacity charge lands on bills through the transmission-and-distribution lines. This is the mechanism with the widest blast radius: every customer in the footprint pays a share of the reliability premium.
- Grid-upgrade riders and hookups. Large industrial customers need transformer stations, transmission spurs and substations; utilities historically recover those costs from the customer that causes them – when the allocation breaks, as the ComEd analysis argues it may, residential customers inherit the shortfall. This is the “billions” warning in its native form: hookup-cost allocation is a rate-case fight.
- Rate-class segregation. The pro-consumer fix: tariff classes that separate data-center service from residential service so the AI load pays its own incremental costs. Consumer Reports’ framework is this argument formalized – the question is whether regulators adopt it before or after the cost lands.
- Stranded-asset risk. If demand forecasts overshoot the buildout, the generation and transmission built for AI load becomes the utility’s asset and the ratepayer’s burden – a risk utilities began pricing into contracts this cycle; the demand-vs-hype debate is a stranded-assets debate wearing different clothes.
- Price-shock spillovers. Concentrated load growth tightens local supply-demand faster than the auction can reprice it – spot-price volatility in constrained zones (the mechanism Virginia’s utilities have been managing) transmits as fuel-cost adjustments before the capacity market catches up.
The honest framing our data-center coverage has carried all quarter: none of this is unique to AI – concentrated industrial load has always touched shared grids – but the SPEED and CONCENTRATION of the AI buildout makes the five mechanisms land at once, at scale, in rate cases stacked on rate cases. That is why the consumer-protection side finally has papers and surveys rather than newsletters.
The regulator scoreboard: who won what
The week’s concrete moves, in order of what they settle. Federal-consumer side: Consumer Reports’ paper – the consumer-safety institution entering the rate-design fight with a framework called “paying their own way” – matters because it arms state utility commissions with a ready structure for data-center tariff classes. State-watchdog side: Illinois’ Citizens Utility Board warning that ComEd customers could pay billions in hookup costs – the watchdog’s framing puts the allocation question directly into the state’s rate-case calendar. Political side: the CNBC survey documenting the voter backlash over data-center growth under the administration’s buildout push, plus the White House’s State-of-the-Union line that tech companies will “pay for their own electricity use” – the political alignment that turns utility-rate fights into visible elections issues. Town side: Trumbull’s rejection of a data-center moratorium (the town kept its door open) and Cromwell’s document-revelation timeline (discussions ran over a year) – the pattern across towns is neither blanket yes nor blanket no; it is a negotiation over exactly the allocations this piece itemizes. The scoreboard’s honest summary: no regulator has yet adopted the full segregation model at scale – the argument is being built while the load is being built, which is why every rate case this winter is a precedent case.
The solutions actually being deployed
The most concrete answer shipped this week is Google’s: backing a virtual power plant built around AI data centers – using the flexibility and storage that data centers bring (batteries, interruptible load, on-site generation) as grid assets rather than treating them purely as demand. Virtual power plants historically meant households’ water heaters and EVs coordinating; the data-center version inverts the model – the largest new loads on the grid become participating capacity. The economics: if a gigawatt campus can curtail, shift and discharge during peaks, its own bill shrinks AND the capacity auction’s premium shrinks for everyone – the only structure on the table so far that converts the buildout from load into grid support. Our power-side coverage tracks the engineering reality of the same lane: the grid connection queue, the gas turbines, the nuclear contracts and the water wall – the VPP is the demand-side of that same buildout finally getting an instrument.
The honest caveat the desk keeps on record: virtual power plants and data-center flexibility solve the capacity problem at the margin; they do not erase the transmission and generation buildout the load growth demands. The consumer-cost question narrows with them; it does not close without the rate-design fight.
The Philippines angle
The same economics, different geography – which is exactly why the global story lands here. The Southeast Asia data-center map we track is densifying into Manila, and the same five mechanisms now live in Meralco’s world: concentrated load, transmission upgrades, rate-class design, and the tariff decisions that decide whether the new campuses’ costs ride their own meters or the grid’s. The Filipino consumer-side stakes look smaller in absolute terms – our data-center footprint is a fraction of Virginia’s – and they are proportionally the same: when a hyperscale campus plugs in near a Metro Manila substation, the tariff design in that contract is a household-bill question. Our data-center backlash coverage and the generation-side timeline mapped the engineering; the consumer-protection layer is the regulator scoreboard above, imported to local rate cases. The desk’s lane note: the Philippines has a natural advantage in the argument – the EPIRA framework already separates generation, transmission and distribution – the rate-class question arrives earlier and cleaner here, which makes the current rate-case calendar in Manila worth watching as closely as Virginia’s.
What to watch this winter
The calendar’s four tells. One: the state rate cases carrying data-center tariff classes – whether any U.S. commission adopts the Consumer Reports-style structure wholesale. Two: PJM’s next capacity auction filings – the 13-state footprint’s reliability premium is the widest-blast-radius number. Three: ComEd’s hookup-cost accounting – the “could pay billions” figure is a warning until the rate case converts it into an actual allocation. Four: the virtual-power-plant pilots’ performance data – Google’s structure scaling converts the AI data centers story from load-side to grid-side, and every pilot’s numbers become rate-case exhibits. The bill you will see next winter is being written in exactly those four files.
Financial Disclaimer
This article is infrastructure and utility-analysis coverage for general information, not financial or investment advice. Rate outcomes, auction results and regulatory decisions change without notice; utility bills and any investment implications of utility economics depend on jurisdiction-specific filings. Nothing here recommends any investment or utility choice. Consult licensed professionals before acting. WorldNgayon holds no positions in any utility or company discussed.
One more consumer-side number completes the picture of the AI data centers cost fight: the WBEZ investigation’s figure – data centers are expected to cost ComEd about $3 billion in hookup-and-infrastructure investment, and the consumer groups’ fight is over the sharing ratio, not the buildout itself. Read the two documents side by side and the shape of the negotiation is fully visible: the utility’s filing says the infrastructure is necessary and large; the watchdog’s review of the utility’s records argues the allocation must put the load’s own costs on the load; and the state commission’s rate case is where the ratio gets written. The same shape now governs every new grid in the buildout – which is why the who pays question, born this week as a utility-rate fight, ends the winter as either a precedent or an invoice.
FAQ
Who pays for AI data centers?
Under current U.S. rate structures, everyone connected to the affected grids pays a share – through capacity-auction pass-throughs, transmission riders and fuel-cost adjustments – unless regulators adopt segregated data-center tariff classes. Consumer Reports’ framework argues the incremental cost should fall on the data centers; several states are moving rate cases in that direction.
How much could bills rise because of AI data centers?
The concrete warning on the record: Illinois’ Citizens Utility Board says ComEd customers could pay billions in data-center hookup costs. National-scale numbers depend on the PJM capacity auction (13 states) and each utility’s allocation decisions – the mechanism, not one number, is the finding.
What did Consumer Reports propose?
A rate-design framework under which AI data centers “pay their own way” – dedicated tariff classes so the incremental grid cost of data-center load is carried by that load, protecting residential customers from cost-shifting. It arms state utility commissions with a ready structure for the current wave of rate cases.
Is there a solution that doesn’t raise bills?
The most shipped one is the virtual power plant: Google’s pilot treats data-center batteries and flexible load as grid assets, so the largest new users curtail and discharge during peaks – paying less themselves and shrinking the capacity premium everyone shares. It solves the capacity margin at best; the transmission buildout question remains.
Why is this happening now?
Because AI data centers add gigawatt-scale concentrated demand faster than any industrial load grew in recent decades, and the grid’s cost-recovery mechanisms – auctions, riders, rate classes – are now converting that growth into bills. The consumer-side papers and surveys turned a utility-law question into a public one this week.
What does this mean for Filipino consumers?
The same five mechanisms now apply as hyperscale campuses plug into Metro Manila and provincial grids: concentrated load, transmission upgrades, tariff-class design. The EPIRA framework’s clean separation gives regulators an earlier, cleaner rate-design question – the data-center contracts being negotiated now are the household-bill decisions of the rest of the decade.