Table of Contents
Key Takeaway
- 🏦 SSS LoanLite is SSS’s micro-loan facility (Circular 2026-005) now live on UnionDigital Bank’s app: borrow ₱1,000–₱20,000 digitally, no employer certification, proceeds credited straight to your account.
- ⏱️ Repayment terms run 15, 30, 60, or 90 days at 8% per annum (≈0.67%/month) — the prevailing initial-salary-loan rate, but the clock is weeks, not years.
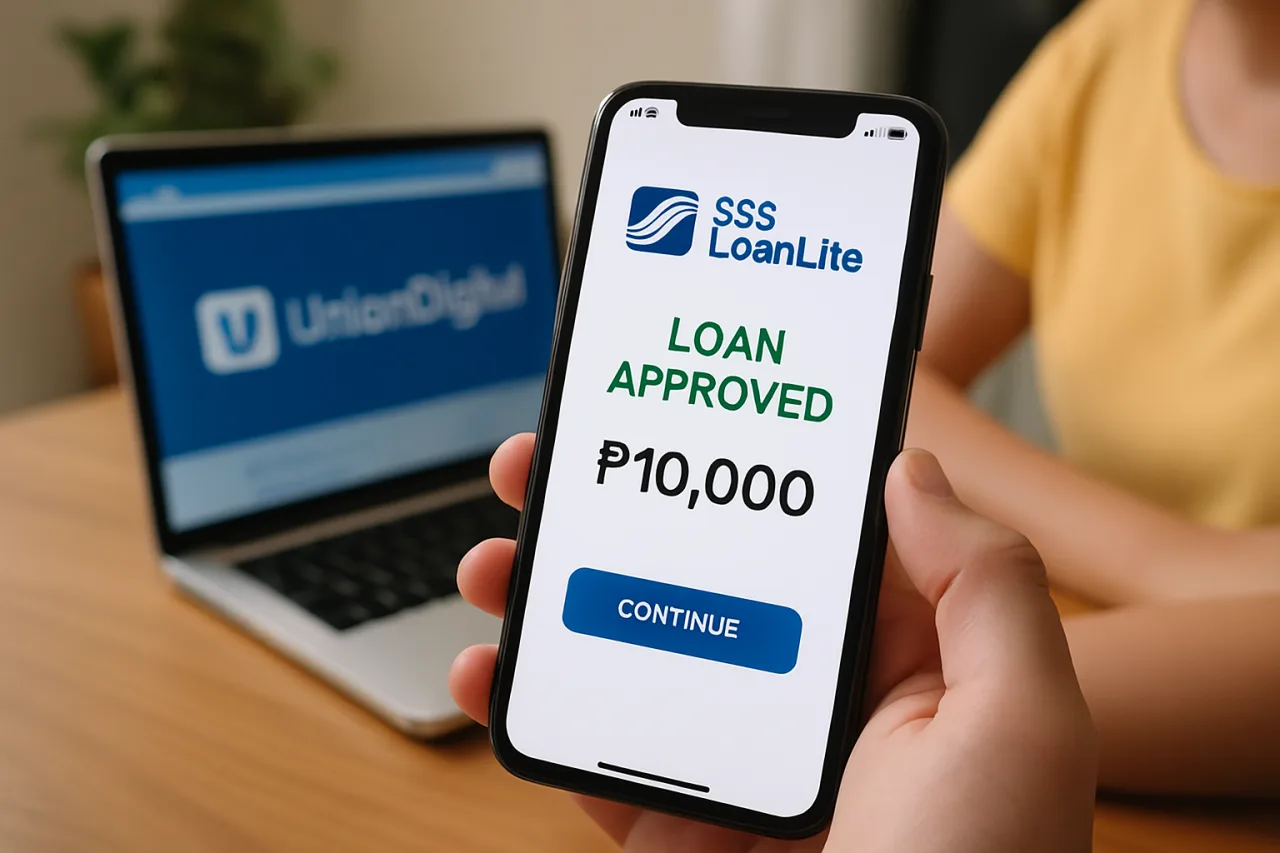
- 📱 The application is six taps in the UD App: banner → SS number → eligibility check → amount and term → disclosures → submit; approval and crediting are digital end-to-end.
- 🇵🇭 Built for the gaps salary loans don’t cover — emergency expenses, medical needs, tuition, home essentials, small-business support — without the fixer economy.
- ⚠️ The discipline note: 8%/year is fair, but a 15–90-day loan that rolls over is expensive — the guide includes the payback math that keeps LoanLite a tool, not a trap.
What SSS LoanLite Is — and What Changed
SSS LoanLite is the retail face of the SSS Micro Loan Facility under Circular 2026-005: short-term loans of ₱1,000 to ₱20,000 offered through the mobile apps of participating financial institutions, with UnionDigital Bank as the launch partner. The SSS frames it for immediate personal needs — emergency expenses, medical costs, education, home essentials, small-business support — and the design goal is visible in every parameter: no employer certification, fully digital application, direct crediting to the borrower’s account at the participating institution.
What changed with the UnionDigital launch is distribution. The salary loan — SSS’s classic product — still runs through the My.SSS portal with employer involvement and longer processing; LoanLite puts the credit decision inside a bank app the way instant lending already works everywhere else. The Philippine Information Agency’s launch report confirms the parameters: 8% per annum (≈0.67% monthly), 15/30/60/90-day terms. For OFW families, the second-order benefit matters as much: a member back home can handle a ₱8,000 emergency without messaging abroad for a transfer that takes a day and costs a fee.
Eligibility and Loan Limits
The SSS-side frame: active members with qualifying contribution records, 18 to under 65 years old, whose records show eligibility when the app queries SSS in real time. The app itself performs the eligibility check — enter your SS number, and the facility returns your maximum loanable amount and available terms. The published range: ₱1,000 up to ₱20,000, with the ceiling tied to your contributions rather than a flat grant. Inquirer’s Cebu Daily News report walks the same eligibility path: apply through the official UnionDigital app, subject to SSS and UnionDigital verification.
Who benefits most: members whose salary-loan eligibility is consumed, whose employers are unreachable for certification, or whose need is too small for a salary loan’s minimum structure to make sense. Who should pause: anyone who cannot name the source of repayment within 90 days — the discipline section below is part of the deal.
How to Apply via UnionDigital (Step by Step)
The six-step flow, straight from SSS’s official page and UnionDigital’s FAQ:
- Install and verify the UnionDigital Bank app (official app stores only — the fake-app warning is in every SGG advisory for a reason), complete eKYC with one valid ID.
- Tap “APPLY NOW” on the SSS LoanLite homepage banner in the UD App.
- Enter your SS number — the app queries SSS directly.
- Review your eligibility: maximum loanable amount and available repayment terms appear in-app.
- Select amount and term (15, 30, 60, or 90 days) and read the disclosures, terms, and consent statements — actually read them; the interest computation is in there.
- Submit and wait for crediting — proceeds land in your UnionDigital account, spendable via card or transfer.
One application reality to expect: eligibility is computed at application time from your live SSS record. If the app returns “not eligible,” the usual causes are contribution gaps or pending employer postings — both fixable at My.SSS, then retry next month.
The Payback Math: What ₱10,000 Really Costs
Run the numbers before tapping submit. A ₱10,000 LoanLite at 8% per annum for a 30-day term costs about ₱67 in interest — genuinely cheap money for an emergency. A 90-day run costs roughly ₱200. The trap is rollover: renewing every 30 days for a year turns the fair rate into a standing debt service (~₱800/year on the same ₱10,000 — cheap per cycle, but only if the principal eventually clears). The rule that keeps LoanLite a tool: borrow once against a named repayment source — next salary, a maturing remittance, a client payment — and close it on schedule. Compare that with the informal 5-6 system at 20% per month, and the 8%-per-year structure is the reason this facility exists.
LoanLite vs Salary Loan vs the 5-6 Trap
- SSS LoanLite: ₱1K–20K, 8%/year, 15–90 days, no employer sign-off, app-speed approval — sized for gaps, not for major expenses.
- SSS Salary Loan: one-month salary credit up to ₱36,000 (two-month with 72 contributions), ~8% over 2 years, employer certification for employed members — the right tool for bigger, planned needs.
- The 5-6 / online-predi trap: 20%/month compounds to triple-digit annual rates; borrowing there is the emergency that creates the next emergency. LoanLite’s whole purpose is to be the better door when the gap appears.
The honest ranking: planned needs → salary loan; sudden small gaps → LoanLite; never → 5-6. And one more SSS-native option deserves its moment: members who qualify for salary loans should compare LoanLite’s 90-day cost against a salary loan amortization — sometimes the bigger loan is the cheaper money.
The OFW Household Layer: When LoanLite Helps Back Home
For OFW households, SSS LoanLite solves a specific, recurring problem: the small emergency that happens back home while the earner is abroad. A ₱6,000 medical copay, a school miscellany, a appliance repair before the family gathering — the old playbook was a remittance marked “urgent”: a day’s delay, a ₱300–500 transfer fee on a small amount, and a workday interruption to send it. With LoanLite on a spouse’s or parent’s phone, the family borrows against the member’s own SSS record at 8% per year, solves the gap in minutes, and repays from the next month’s budget — often for less than the remittance fee would have cost on the same amount.
The eligibility nuance matters here: LoanLite runs on the member’s record, so the member must be the applicant. OFWs maintaining voluntary contributions preserve exactly the record this facility checks — the quiet dividend of years of paying into the system even while abroad. The contribution-discipline tie-in: an OFW who keeps SSS active isn’t just buying a pension; they’re building a credit infrastructure their household can draw on in emergencies.
The budget discipline that makes it sustainable is the “borrow-once” rule: name the repayment source before tapping submit, and if the answer isn’t a specific salary, remittance, or receivable, the answer is no this month. Households that keep a small liquid emergency buffer (even one month of expenses) will rarely need LoanLite at all — which is the ideal. The facility’s real value is as the bridge between the buffer you’re building and the emergencies that arrive before it’s finished.
Frequently Asked Questions
What is SSS LoanLite?
SSS’s micro-loan facility (Circular 2026-005) offering ₱1,000–₱20,000 short-term loans through participating financial institutions’ apps — currently UnionDigital Bank — with no employer certification and digital crediting.
Who is eligible for SSS LoanLite?
Active SSS members aged 18 to under 65 with qualifying contribution records; the app checks eligibility in real time when you enter your SS number. The UD App shows your maximum loanable amount and available terms on the spot.
How much interest does SSS LoanLite charge?
8% per annum (≈0.67% monthly) — the prevailing rate for an initial SSS salary loan. On ₱10,000 over 30 days that is about ₱67; over the maximum 90 days, roughly ₱200.
How do I apply for SSS LoanLite via UnionDigital?
Install the official UnionDigital Bank app, complete verification, tap APPLY NOW on the SSS LoanLite banner, enter your SS number, review your eligibility and terms, choose amount and repayment period (15/30/60/90 days), accept the disclosures, and submit — proceeds credit directly to your account.
Can OFW members use LoanLite?
Membership-based eligibility applies the same to OFW members with active contribution records; the practical requirement is a Philippine mobile number and access to the official app for verification. Many OFWs use it for family emergencies back home instead of wiring emergency funds at remittance fees.
What happens if I can’t repay in 90 days?
Unpaid micro-loans follow SSS’s delinquency rules — and rolling 90-day cycles repeatedly converts cheap credit into standing debt. Borrow against a named repayment source, close on schedule, and treat any second cycle as a signal to revisit the budget rather than the app.