Table of Contents
End of Service Benefits (EOS) in Saudi Arabia: How to Calculate Gratuity Under S — our dedicated guide goes deep on this.
Related: Iqama Renewal in Saudi Arabia: the Steps, the Fees and the Deadlines
Key Takeaway
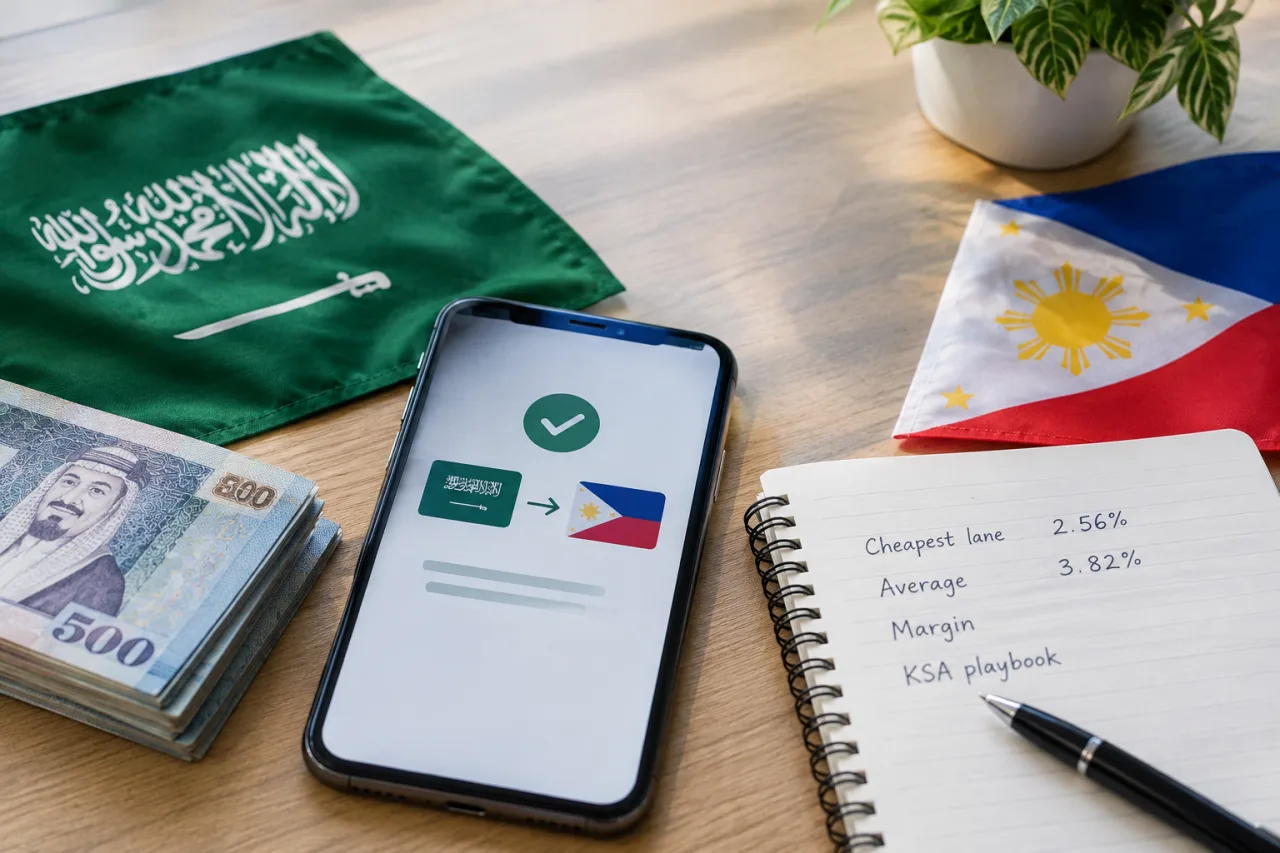
- 🏦 The tracked cheapest list: on the World Bank’s own Saudi remittance corridor table, STC Pay posts the lowest total cost — 2.56% (19.20 SAR on the ₱750-class send) — with its margin math printed in the open: market reference rate 15.11 PHP/SAR against the charged 15.07, a 0.26% exchange-rate margin (Remittance Prices Worldwide, the World Bank’s corridor database).
- 📊 The corridor’s true average: the same table prices the corridor average at 3.82% total cost (fee plus FX margin together, 28.64 SAR class on the standard sums) — so the gap between the best section and the typical group is real money, repeated every single payday.
- 🧾 What the two-line cost means: every Saudi remittance is priced twice — a flat fee and an exchange-rate margin inside the rate; a “cheap fee” with a wide margin still loses, and only the total (fee + margin) tells the truth.
- 📈 The corridor’s weight: Saudi Arabia stays a top-3 remittance source as Philippine cash remittances printed $3.04 billion in June 2026 — the highest monthly figure on record (the BSP’s own announcement) — the reason this corridor’s pricing matters to the whole economy.
- 🛠️ The standing system: two apps tested per send on every Saudi remittance (the “recipient gets” line), receiving into a bank or wallet rather than cash pickup where possible, staged conversions on the peso’s swings — the corridor playbook carries the exact steps.
The Saudi remittance corridor deserves better than folklore: it carries one of the Philippine economy’s lifelines — Saudi Arabia sits among the top sending countries as the BSP’s June 2026 print hit a record $3.04 billion in monthly cash remittances — and the World Bank’s corridor database now gives the fees an auditable shape: the cheapest tracked check (STC Pay, 2.56% all-in) against a corridor average of 3.82%, with the margin arithmetic visible on the page. This piece reads that table the way a payer should: the fee line and the margin line separated, the tracked sections ranked, the receiving side priced, and the KSA-specific playbook built on our own verified material — the BSP data section, the peso staging rules, and the account pieces that make the difference compound. Every figure carries its source; the exchange-rate snapshots carry their dates, because corridor rates move and the fee structures are the stable part.
Related: Philippines GDP Skids to 2.1% in Q3 2026: What the Slowdown Means for Your…
Reading the World Bank’s Saudi Remittance Table Correctly
The Saudi remittance table’s architecture is the lesson. Two cost lines, added: the fee the sender pays (a flat charge per send) and the exchange-rate margin — the gap between the market reference rate and the rate the provider actually applies. On the Saudi→Philippines page the margin math sits in the open for the cheapest tracked group: reference 15.11 PHP/SAR, charged 15.07, a 0.26% margin — and that honesty is the point: STC Pay’s 2.56% total (19.20 SAR on the corridor’s standard sums) beats the tracked field not because its flat fee vanishes but because its margin stays thin. The comparison rows: MoneyGram’s margin class runs to 2.70% with a 20.25 SAR total (5.40 on the same sums), Fawri’s to 2.76% (20.72 SAR, 5.53), and the corridor average lands at 3.82% total (28.64 SAR class, fee average 22.99) — the payer who doesn’t shop pays the difference to that average every payday. this site’s honesty note on periods: the World Bank’s reference rate prints an older snapshot (15.11) than the BSP’s own October 2026 SAR reference (16.9073 on our Gulf-rate board) — corridor rate tables update on release cycles; the fee structures and the margin gaps are the durable comparison, and every live rate gets confirmed on the send day.
The Saudi Remittance sections, Ranked by Structure
- The Saudi-superapp list (STC Pay and its class): in-app international transfer, mada-funded, direct-to-bank payouts — the tracked-cheapest structure because the margin runs inside a system the payer already uses; the barq-class apps advertise free international transfers with their own fee schedules beside them (the Saudi lifestyle guides’ 2026 fee roundups carry the published schedules, SAR 15-class fees at some banks).
- The bank counter section (Enjaz, Al Rajhi’s Telemoney-class, Alinma, Albilad): the branch service many long-time OFWs keep; its fee averages sit above the superapp class and its cash pickup option adds agent-side handling on arrival — the group’s advantages are the physical counters and the document handling (iqama-class enrollments) some payers prefer.
- The global digital check (Remitly, Wise, Xoom, MoneyGram’s digital): app-to-app pricing with published fee schedules; on the Philippines corridor the same structures our Wise vs Remitly comparison verifies run inside the KSA corridor with corridor-specific fee schedules — the “recipient gets” test applies identically.
- The direct-to-bank lines (STC Pay → GoTyme-class Philippine accounts): the payout geometry changing in 2026 — Saudi apps landing directly in Philippine digital-bank accounts (the guides’ own documented flow), which pairs the cheapest send structure with the strongest receiving account (our digital-bank comparison carries the receiving side).
The Saudi Remittance Margin in Pesos: the Worked Ladder
The arithmetic a payer feels. Send ₱10,000-class monthly (about SAR 660 at the corridor’s BSP-side reference): at the tracked-cheapest list’s 2.56% all-in, the cost runs SAR 16.9-class per send — roughly ₱255-260; at the corridor average (3.82%): SAR 25.2-class — roughly ₱385; at a wide-margin legacy quote (the 4-5% class our Western Union caution documents on the US corridor), the same send surrenders ₱450-500. Over a year of twelve sends, the gap between shopping and not shopping runs ₱1,500-2,900 — a class of money that funds a month of the household’s groceries, earned by the two-app routine alone. The receiving side belongs in the same ladder: bank-account and wallet payouts price better than cash pickup in the tracked structures (the WB’s receiving-method lines), which makes the receiver’s account choice (the fee-free digital banks) part of the remittance plan, not a separate topic.
The Standing Saudi Remittance Playbook
- Run the two-app test per send: same amount, same minute, read both “recipient gets” lines — the corridor’s promos (zero-fee months, rate-day boosts) move the winner; the habit catches it.
- Prefer bank/wallet arrival: the tracked structures price cash pickup above account arrival — the receiving account (our digital-bank interest piece carries the earning choices) turns the arrival side into the savings group’s first rung.
- Stage the conversion: the peso’s 2026 record-low run (the peso playbook’s levels and staging rules) applies across every provider — the channel doesn’t rescue a badly timed conversion.
- Keep the corridor data honest: the BSP’s monthly release (the BSP’s own releases; our remittance-data analysis carries the June 2026 record and the country shares) is the section’s scoreboard; the SSS-side obligations run parallel (the SSS-from-Saudi guide carries the contribution mechanics).
- Fund the programs by the same paths: the MP2 ladder and the WISP comparisons (our government-program head-to-head) ride on the same send-day margins — the margin you save is the margin you invest.
Two more Saudi remittance verifications the corridor’s history makes necessary. First, the peso-arrival group’s own record: Saudi-sourced remittances have run among the corridor’s steadiest streams for a decade – the BSP’s country-share releases (our data analysis carries the series) show the Kingdom’s flows holding through both the oil-price slumps and the labor reforms – which is why the check’s pricing innovations (the superapp sends, the direct-to-bank lines) matter at scale: a 1-point margin saving on a top-3 corridor moves real money monthly. Second, the timing layer the guides skip: the corridor’s send-day rhythms (month-end paydays, the Hajj-season travel window, the June-July enrollment spikes) show up in the BSP’s monthly prints – send-day pricing can differ around those windows, and the two-app test catches the promo days. The system holds: structure first, timing second, accounts third – in that order, every payday.
The arrival-account bridge deserves its own paragraph because it is where the corridor’s savings compound. The margin saved at the send line lands best when the receiving side costs zero and earns: the fee-free Philippine digital banks (our comparison piece carries the 3.00-4.00% pre-tax class and the after-tax ladder) turn the received peso into an earning peso the same day – while the cash-pickup route hands the last-mile fee to the agent and the idle peso to nobody. The programs then sit on top: the remittance-funded MP2 ladder (our guide carries the ₱500 entries and the five-year clock), the WISP-side accumulation (the head-to-head’s wrapper logic), and the SSS mandatory line’s own coverage (the Saudi guide’s mechanics) – each funded through the same cheap rail the two-app test found. The corridor’s system, stated as this site teaches it everywhere: cheap send, free arrival, earning account, program ladder – four lines, in that order, and the family’s budget boundary above all of them (the boundary framework’s rules apply before the first line is funded).
What Would Change This Reading: the Invalidation Ledger
- The next World Bank release: the corridor table refreshes on the release cycle — a new cheapest list or a re-priced STC Pay margin updates the ranking same-day the release lands.
- The BSP’s own rate moves: the SAR reference rising or falling with the dollar’s run changes the conversion side, not the fee structure — the step re-runs against each new reference.
- Saudi-side pricing changes: the superapps’ fee schedules (barq, STC-class) and the banks’ published changes — the saudi-lifestyle fee roundups re-verify quarterly.
- A receiving-side change: Philippine banks’ inward-remittance fees or wallet inbound rules moving re-prices the arrival leg — the account comparison re-verifies against the banks’ own pages.
What the Evidence Supports, by Reader Situation
Education desk, not an advisory service — decision inputs, never instructions.
- If you’re a first-time OFW in the Kingdom: the verified entry: the app-route (STC Pay-class) priced 2.56% all-in on the tracked table against the 3.82% corridor average — start there, run the two-app test, receive into a fee-free account.
- If you’re a long-time counter sender: the average’s 3.82% is the counter section’s cost class; the app group’s switch decision (documents, iqama, the family’s comfort) is the one that saves the margin — and the counter’s value (documents, physical help) can be worth paying for; the piece’s job is the price of knowing.
- If you’re planning the peso side: the margin saved plus staged conversions compound — the corridor’s own numbers say the shopping discipline out-earns the differences between most investment alternatives on the household scale.
FAQ
What is the cheapest way to send money from Saudi Arabia to the Philippines?
On the World Bank’s tracked corridor table, the cheapest check is STC Pay-class app transfer at 2.56% total cost (fee plus a 0.26% exchange-rate margin, 19.20 SAR on the standard sums) — with bank/wallet arrival preferred over cash pickup. The corridor average runs 3.82%; every Saudi remittance worth sending runs the two-app test each send and re-verifying same-day quotes.
Why do remittance apps have fees AND exchange-rate margins?
Because the price lines are separable: the fee is the flat charge announced per send, and the margin is the provider’s own rate against the market reference (the WB’s example: reference 15.11 vs charged 15.07). Providers load cost into either line — a zero-fee send can carry a wide margin, which is why only the total cost compares fairly.
How much does the margin difference cost over a year?
this site’s worked ladder on ₱10,000-class monthly sends: the tracked-cheapest list costs roughly ₱255-260 per send against the corridor average’s ₱385 class — a ₱130-145 gap per send, ₱1,500-2,900 over a year of twelve sends, before the receiving-side differences and the conversion staging stack their own effects.
Is cash pickup more expensive than bank transfer?
In the tracked structures, yes generally — the WB’s table prices the receiving methods separately, and account/wallet arrivals run the cheaper class on this corridor; cash pickup buys the last-mile convenience and the agent handling. Where the receiver has no account, the wallet routes (GCash and its class, our setup guide) cover most of the cash lane’s niche at account-arrival pricing.
How big is the Saudi remittance corridor?
Among the largest in the system: Philippine cash remittances printed a record $3.04 billion in June 2026 with Saudi Arabia among the top-3 sending countries (the BSP’s own release, our data analysis carries the series). The corridor’s pricing therefore matters at economy scale — and at the household’s own payday scale.
Financial Disclaimer
This article is for general information and education only. It is not financial, investment, legal or tax advice, and it does not recommend any money-transfer provider, financial product or course of action. Fees, exchange-rate margins and promotional terms change by corridor, provider and day; every figure was verified against the cited dated sources (the World Bank’s corridor database, the BSP’s releases and the providers’ own pages) as of November 2026 and must be re-confirmed on the live quote screens before any transfer. WorldNgayon is not affiliated with any provider or agency named, and no content on this site should be acted upon without independent verification and, where appropriate, advice from a licensed professional.
- remittanceprices.worldbank.org/corridor/Saudi-Arabia/Philippines
- Official bsp.gov.ph — the BSP’s own announcement
- remittanceprices.worldbank.org
- saudilifeguide.com/best-money-transfer-services
External sources linked in this article, in order of first mention. Spotted an error or a broken link? Tell us.
Cite this pagePublished Nov 1, 2026 · Updated Nov 17, 2026
Agron, E. (2026, November 1). Saudi Remittance to the Philippines 2026: Fees, Margins and the Fastest Routes. WorldNgayon. https://worldngayon.com/saudi-remittance-philippines/
Agron, Edmon. “Saudi Remittance to the Philippines 2026: Fees, Margins and the Fastest Routes.” WorldNgayon, 1 Nov. 2026, worldngayon.com/saudi-remittance-philippines/.
Agron, Edmon. “Saudi Remittance to the Philippines 2026: Fees, Margins and the Fastest Routes.” WorldNgayon, November 1, 2026. https://worldngayon.com/saudi-remittance-philippines/.
Agron, E. (2026) ‘Saudi Remittance to the Philippines 2026: Fees, Margins and the Fastest Routes’, WorldNgayon, 1 November. Available at: https://worldngayon.com/saudi-remittance-philippines/.
E. Agron, “Saudi Remittance to the Philippines 2026: Fees, Margins and the Fastest Routes,” WorldNgayon, Nov. 1, 2026. [Online]. Available: https://worldngayon.com/saudi-remittance-philippines/
@online{agron2026saudiremittance,
  author       = {Agron, Edmon},
  title        = {{Saudi Remittance to the Philippines 2026: Fees, Margins and the Fastest Routes}},
  year         = {2026},
  date         = {2026-11-01},
  organization = {WorldNgayon},
  url          = {https://worldngayon.com/saudi-remittance-philippines/},
  urldate      = {}
}TY - ELEC AU - Agron, Edmon TI - Saudi Remittance to the Philippines 2026: Fees, Margins and the Fastest Routes T2 - WorldNgayon PY - 2026 DA - 2026/11/01/ UR - https://worldngayon.com/saudi-remittance-philippines/ Y2 - ER -
Cite the version you read; the page may be updated. Zotero and Mendeley can also import this page directly.