Editor’s Note — November 4, 2026: This article has been updated to clarify the Department of Energy’s role in Philippine fuel pricing under the deregulated regime of Republic Act No. 8479, verify the reporting period of the fuel-price figures cited, and refine explanations of how international oil prices affect households, businesses, and investors.
Table of Contents
Oil Price Hike Effects: How a Brent Spike Reaches Your Budget and Your Portfolio
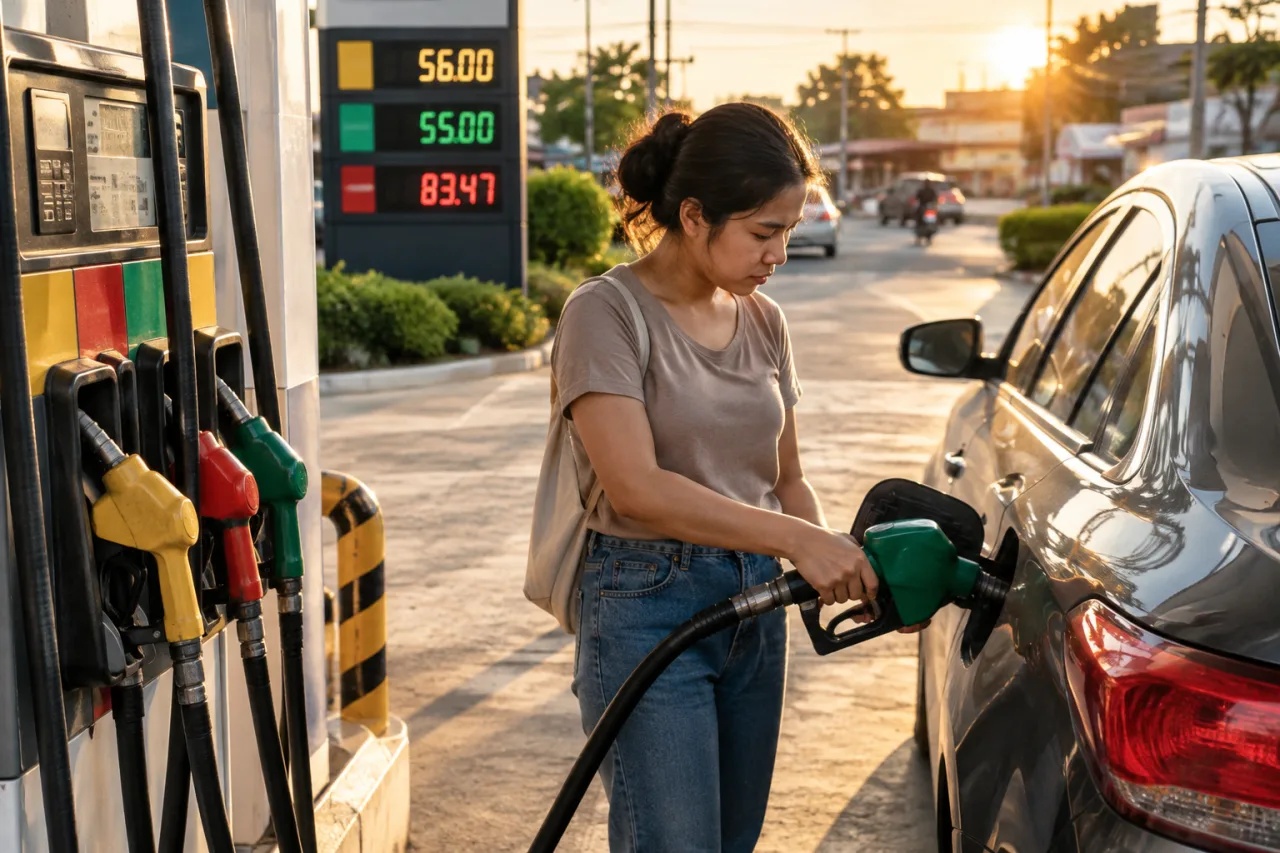
Recent oil-price developments: Brent crude jumped 3.14% to $116.72/barrel on Oct 23 — its highest settlement in nearly six months — and market reporting (CNBC, October 23) had Brent topping the $110 line again | the DOE’s announced pump adjustments for Oct 27–Nov 2: gasoline −₱0.30/L, diesel +up to ₱1.20/L, kerosene −₱0.50/L | the pre-conflict baseline prices (before the fighting that broke out February 28): ₱56/L RON95, ₱55/L diesel, ₱83.47/L kerosene in Metro Manila | the Philippines imports most of its petroleum as finished products — the oil price hike effects’ transmission into Filipino budgets and portfolios, mapped end to end
Practical arithmetic: what a spike means in peso terms
Household transport (hypothetical): a family spends ₱4,000 a month on transportation. A 5% increase in that expense adds ₱200 to the monthly budget — the example illustrates budgeting arithmetic, not a claim that fare tables move proportionally with crude. The same method applies to cooking fuel, delivery orders and any line item with a fuel share: name the amount, apply the change, read the peso effect.
Small-business deliveries (hypothetical): an online seller runs ₱6,000 a month in delivery and fuel costs. If those inputs rise 8%, the monthly figure becomes ₱6,480 — ₱480 that either narrows the margin or has to pass into pricing. The limitation belongs in the plan: raising prices faster than customers notice works until competitors do not match it, so the practical response is a written rule for how much input increase triggers a repricing decision, and how much sits as margin.
Overseas Filipino households (hypothetical): a remittance arrives at the peso equivalent of $300; at a peso-dollar rate of 58 the family receives ₱17,400. If the peso weakens to 59.5, the same dollars convert to ₱17,850. The exchange-rate effect and the oil-price effect are separate mechanisms: the rate moves what each dollar buys, while fuel prices move what those pesos purchase at the store. Neither explains the other, and checking both is a two-minute habit.
Key Takeaway
- ⛽ The transmission chain (the transmission chain): global crude (Brent at $116.72 on the Oct-23 record) → the regional finished-product markets (the Philippines imports most of its petroleum as finished products) → freight and supply pressure → the industry’s weekly price adjustments, which the DOE tracks in its monitoring → the pump and the LPG cylinder. Philippine downstream oil pricing operates under the deregulated regime of Republic Act No. 8479: oil companies set and implement their own retail prices, while the Department of Energy’s function is monitoring the market and publishing the weekly adjustment record — monitoring a price and authorizing it are different regulatory functions. Oil price hike effects are not one number — it is this chain, and the chain’s Philippine end moves weekly.
- 🇵🇭 The domestic record splits by product: the DOE’s Oct 27–Nov 2 window announced gasoline a ₱0.30/L rollback while diesel rose up to ₱1.20/L — the two products move differently because diesel is the freight-and-inflation product (trucks, buses, generators, food chains); what households should monitor is the diesel line, whatever the gasoline banner says.
- 💸 The household-expense effects: transport fares, delivery costs and food prices price diesel in slowly; kerosene-class household fuel and LPG carry the direct hits — the household defense: the fixed-cost audit (commute, deliveries, the cooking fuel) before any investment decision; the money the spike takes from the budget is the same money the emergency floor protects.
- 📈 The portfolio layer cuts both ways: an oil spike pressures oil-importing economies’ stocks (the Oct-30 selloff record: the energy spike compounding the Nasdaq-led wave) while oil producers and energy names benefit — what investors should consider: an energy exposure is a hedge only when it is sized and funded like any other position; the index’s falling days are the wrong time to discover you never had one.
- 🏦 The rate-and-inflation read: sustained Brent above the $110-116 band feeds inflation expectations, which feed rate expectations — the chain that reaches every borrower (our previous coverage of interest rates carries the Fed and BSP decisions on record); for the family budget: spikes pass, but the months underneath them are the budget’s real test — the emergency-month target again.
Oil price hike effects have moved from the finance pages to the family’s transport ledger this month — how oil price hike effects reach household expenses: Brent crude’s $116.72-per-barrel settlement on October 23 (3.14 percent higher, its highest in six months on the record) says the global side, but the practical question a Filipino household asks is smaller and sharper — what will the pump take from the budget this week, and what does the spike do to the money that’s left? The mechanics are knowable end to end: the Philippines imports most of its petroleum as finished products (the structure that carries the freight exposure), so the global price plus freight lands in the regional markets first, then in the industry’s weekly price adjustments, which the Department of Energy monitors and announces — the Oct 27–November 2 window announced gasoline a thin ₱0.30 rollback while diesel rose up to ₱1.20 a liter, following a week where diesel already climbed ₱2.60 and gasoline had eased ₱4.30. This piece maps the whole transmission plainly: the chain from Brent to pump, the household-expense effects (the diesel path for freight, the LPG line for cooking, the kerosene line for off-grid lighting), the inflation-and-rates read that reaches every borrower, the portfolio side (the hedges that may work and the ones better treated with caution), and the budget-defense layer for the household this spike reaches.
Oil Price Hike Effects: the Brent-to-Pump Chain, End to End
- Stage 1 — the global mark: Brent’s settlement ($116.72 on Oct 23, the six-month high per the record; still topping the $110 band into the following week) is the world’s reference for the grades the Philippines buys.
- Stage 2 — the import reality: the Philippines imports most petroleum as finished products — meaning the country’s buying price already includes the refiners’ and shippers’ margins; local pump prices inherit regional fuel-market moves plus freight (the record’s own wording), which is why a Brent day and a Manila pump week connect through a delay, not instantly.
- Stage 3 — the DOE’s weekly adjustments, the official arithmetic: the Energy Department’s announced price changes (the Oct 27–Nov 2 record — diesel +₱1.20, gasoline −₱0.30, kerosene −₱0.50) are the government’s transparency layer on top of the deregulated retail market; the DOE’s own site published the adjustments — that page is the chain’s official receipt.
- Stage 4 — the pump and the kitchen: diesel and gasoline meet the transport and freight lanes; LPG and kerosene meet the household directly — the same spike can reach household expenses at different times and through different routes.
Oil Price Hike Effects on Household Expenses — Where the Spike Actually Lands
- The diesel path (the inflation product): diesel powers the trucks, buses and generators — a sustained diesel climb reaches the family as transport fares and delivered-goods prices with a lag of weeks; higher costs may gradually reach household budgets beyond the pump line, not just the pump line.
- The LPG and kerosene line (the direct product): the kitchen cylinder and the off-grid lighting fuel move with the world price more immediately — the household’s fastest-feeling oil price hike effect, and the first place a budget defense pays.
- The commute math (the worker’s layer): the daily commute’s fuel share (or the fare share it feeds) sets the household’s weekly exposure — the practical fix: the fixed-cost audit (modes, shares, delivery counts) the moment a spike window opens, not after the third consecutive hike week.
- The peso line (the imported layer): fuel is dollar-denominated — a peso easing through the same weeks (the late-October record) compounds every imported liter; the two pressures stack in the pump price and in the family’s remittance arithmetic (the weak peso delivers more pesos per dollar — the other side of the same coin the corridor pieces carry).
Oil Price Hike Effects on Inflation and Rates — How the Spike Reaches Borrowers
- The first hop (prices): transport and energy feed the inflation print in the months after a sustained spike — the mechanism is standard even when the timing is uncertain: waits for the inflation data rather than the mood.
- The second hop (rates): inflation expectations shape what central banks (the Fed’s decision layer on record this month, the BSP’s own cycle) do with policy rates — the chain’s final stop: every floating-rate borrower’s bill, every deposit rate, every mortgage reset.
- the working discipline: one spike is noise, a band (the $110-116 record range) is a signal — the budget defense runs on the sustained level, and the planning rule: plan for the sustained level, not one week’s reading; an emergency-savings target is built for exactly these months.
The Portfolio: Which Investments May Help Manage Energy-Price Risk
- What an oil spike does to an index: the import-side pressure lands on transport, airlines, and manufacturers’ margins while the market’s risk appetite absorbs the shock with everything else — the Oct-30 record (the selloff week compounding the energy spike) is the documented case: spikes and selloffs arrive together when the spike is conflict-driven.
- The energy exposure that IS a hedge: a sized, funded position in producers or diversified energy names rides the spike’s direction — hedged IF sized deliberately and funded from the invested slice; what investors should consider: an unplanned “I should buy oil stocks” impulse in the spike’s worst week buys the top of the fear, not the trend.
- Hedges to treat cautiously: cash under the mattress (the spike is inflation — cash loses quietly), crypto as an oil hedge (the record’s own correlation is unstable — the ring showed the spike-and-Bitcoin lines; the plain reading: correlation that must be guessed is not a hedge), and the “inflation-proof” marketing of any single product — diversification with a written plan remains the hedge class the evidence supports.
Oil Price Hike Effects on Overseas Earnings — the OFW Angle
The reading most pieces skip and our reader needs: the OFW lane — the family earns in one currency (often a Gulf or Western currency) and spends in pesos, and the oil price hike effects run through both books at once. The earning side: a Gulf posting rides oil economics directly (state budgets, project spending and labor demand move with the barrel — the corridor’s own record: the Saudi share of remittances at 6.3 percent); the spending side: the peso household absorbs the pump, the LPG line and the delivered-goods prices exactly as mapped above. The balanced reading: the same spike that taxes the household’s peso books may strengthen the OFW’s earning side (oil-funded economies hire and remit), which is why the family budget reads the barrel from two sides — expenses up on one side, potentially income support up on the other; the balanced reading, not the panic headline, is the way through every spike.
A second consideration for small businesses: the small-business professional (the freelancers and operators WorldNgayon serves) — fuel and power inputs price into service quotes, delivery fees and production costs on a lag; the operating rule: reprice the quote calendar in sustained-spike windows (the band rule again), build the fuel-share transparency into client pricing, and never eat a multi-week input shock silently — the oil price hike effects on a one-person operation are budget arithmetic first and strategy second.
FAQ
Why do oil prices in the Philippines change weekly?
The deregulated retail market re-prices as world crude (Brent at $116.72 on the Oct-23 record), freight and supply move — the DOE publishes the announced price adjustments each week (the Oct 27–Nov 2 window: diesel +₱1.20/L, gasoline −₱0.30/L, kerosene −₱0.50/L on record); the weekly rhythm is the transparency layer’s schedule, not the market’s only movement.
What are the oil price hike effects on the Philippine economy?
Through the import chain: the Philippines buys most petroleum as finished products, so a sustained Brent band feeds transport, freight and production costs first, then consumer prices (inflation), then rate expectations — the oil price hike effects arrive as fares, deliveries and eventually borrowing costs; the pump is step four of a four-step chain.
What was Brent crude’s recent high?
$116.72 per barrel — the October 23 settlement, 3.14% higher and the highest in nearly six months on the record, with the price holding over the $110 line into the selloff week; the driving record: renewed Middle East supply threats (the Saudi infrastructure attacks and the Hormuz tensions on the same record).
Which oil price hike effects should a household defend against first?
Run the fixed-cost audit (commute modes, delivery counts, the LPG/kerosene line), protect the emergency floor (the months-of-expenses target), and avoid panic decisions elsewhere in the budget — the spike’s household damage is weekly and reversible; the floor’s protection is the family’s real hedge.
Are oil stocks a good hedge when prices spike?
A deliberately sized, funded energy position can hedge a portfolio’s import-side exposure — but buying it reflexively in the spike’s worst week buys fear at its peak; a working hedge is planned before the spike (or sized as part of the regular allocation), funded from the invested slice, never from emergency money.
Does an oil spike always mean higher rates?
Not always — one spike is noise and a sustained band is the signal; the chain runs spike → inflation data → central-bank decisions (the Fed layer on record this month), and central banks weigh growth against prices; the careful reading follows the data releases, not the pump headlines.
Financial Disclaimer: This article is an educational energy-economics explainer for general information only — it is not financial advice; no investment, product or hedge mentioned here is a recommendation. Fuel prices, DOE adjustments and market conditions change weekly; figures are cited from sources on record (October–November 2026) and must be verified on the DOE’s official price-adjustment pages before budget or investment decisions. worldngayon.com is not affiliated with the DOE or any oil company named and is not liable for outcomes from actions taken on this content.
Carriers on record: Rappler’s Oct-27 fuel-price report (the DOE adjustments and the Brent settlement, dated on fetch), the DOE’s official price-adjustment page (the DOE’s own page, the source of record) and the Brent-touches-$110 wire read; the supporting pieces: the the remittance data guide, the the emergency-fund mathematics, the the correction playbook, and the the PSEi print episode.
- cnbc.com/2026/10/23/oil-price-brent-wti-iran-war-saudi-arabia.html — market reporting (CNBC, October 23)
- lawphil.net/statutes/repacts/ra1998/ra_8479_1998.html — Republic Act No. 8479
- Official doe.gov.ph — the Department of Energy
- rappler.com/business/fuel-prices-adjustments-october-27-2026 — Rappler’s Oct-27 fuel-price report
- rappler-oct27 — DOE’s official price-adjustment page
- cnbc — the Brent-touches-$110 wire read
External sources linked in this article, in order of first mention. Spotted an error or a broken link? Tell us.
Cite this pagePublished Nov 4, 2026
Agron, E. (2026, November 4). Oil Price Hike Effects: the Brent-to-Pump Chain, Explained. WorldNgayon. https://worldngayon.com/oil-price-hike-effects/
Agron, Edmon. “Oil Price Hike Effects: the Brent-to-Pump Chain, Explained.” WorldNgayon, 4 Nov. 2026, worldngayon.com/oil-price-hike-effects/.
Agron, Edmon. “Oil Price Hike Effects: the Brent-to-Pump Chain, Explained.” WorldNgayon, November 4, 2026. https://worldngayon.com/oil-price-hike-effects/.
Agron, E. (2026) ‘Oil Price Hike Effects: the Brent-to-Pump Chain, Explained’, WorldNgayon, 4 November. Available at: https://worldngayon.com/oil-price-hike-effects/.
E. Agron, “Oil Price Hike Effects: the Brent-to-Pump Chain, Explained,” WorldNgayon, Nov. 4, 2026. [Online]. Available: https://worldngayon.com/oil-price-hike-effects/
@online{agron2026oilprice,
  author       = {Agron, Edmon},
  title        = {{Oil Price Hike Effects: the Brent-to-Pump Chain, Explained}},
  year         = {2026},
  date         = {2026-11-04},
  organization = {WorldNgayon},
  url          = {https://worldngayon.com/oil-price-hike-effects/},
  urldate      = {}
}TY - ELEC AU - Agron, Edmon TI - Oil Price Hike Effects: the Brent-to-Pump Chain, Explained T2 - WorldNgayon PY - 2026 DA - 2026/11/04/ UR - https://worldngayon.com/oil-price-hike-effects/ Y2 - ER -
Cite the version you read; the page may be updated. Zotero and Mendeley can also import this page directly.