

Key Takeaway
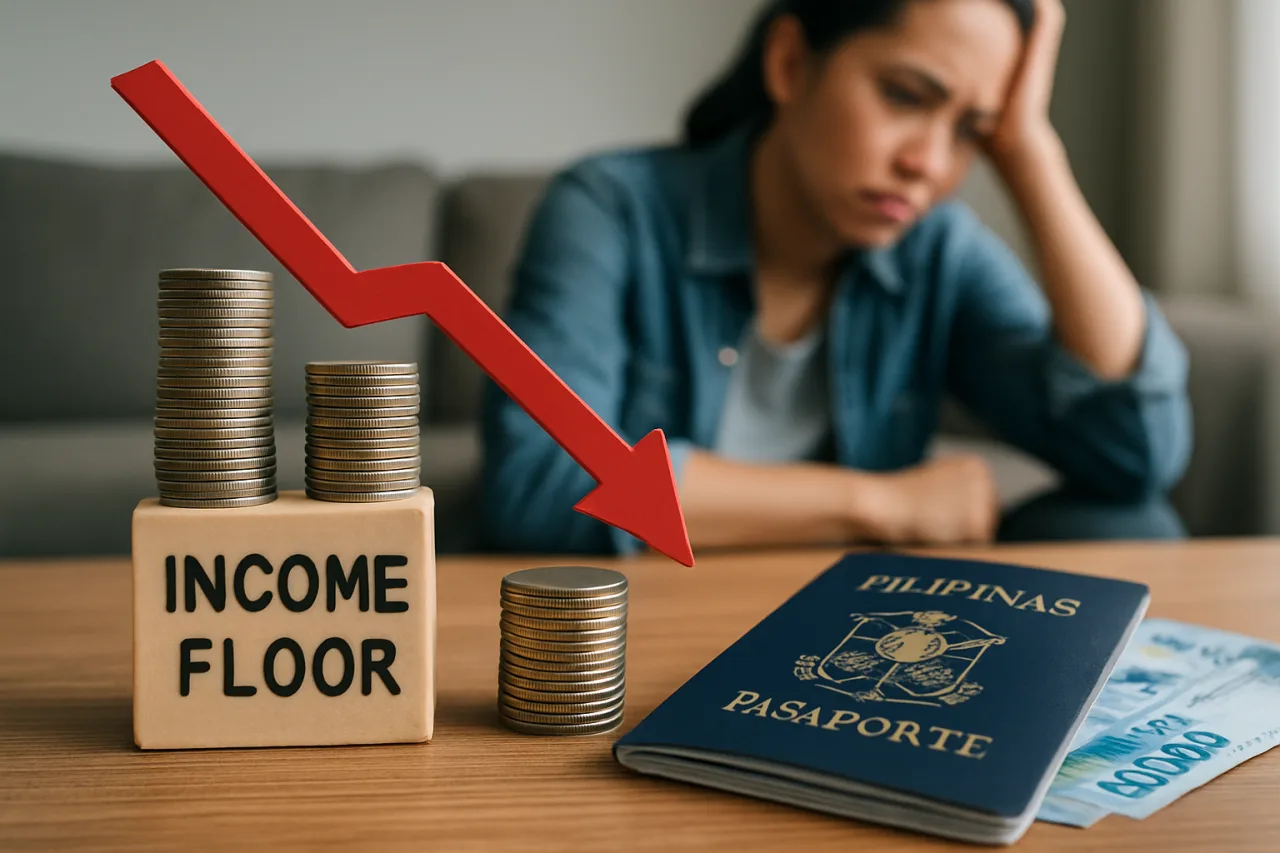
- 📉 Deployments fell 34.04% in the first seven months of 2026 (980,673 vs 1,486,756) — the pipeline of new OFW contracts is the thinnest in years.
- 🏗️ The OFW income floor is a two-layer structure: the OFW salary layer (with contract-gap coverage) plus a home-side income layer that exists independent of any contract.
- 🔢 Step one is naming the floor number — the minimum monthly amount the household needs to survive, not to maintain lifestyle.
- 🧱 The home-side layer builds on what the family already has: a second earner’s certification, a micro-enterprise, dividend-paying savings — anything that pays without a deployment.
- ⏳ Households that build the floor now — before the next contract gap — meet the slump with options; those that wait meet it with arithmetic they cannot change.
The number that should restructure every OFW household budget this year is not a remittance record — it is the deployment figure.
The DMW counted 980,673 workers leaving for overseas jobs in the first seven months of 2026, down 34.04% from the 1,486,756 of the same period in 2025, as the Middle East conflict froze hiring in eight suspended markets and 10,580 workers and dependents came home on repatriation flights.
The installed base of OFWs keeps earning and sending — the remittance data reported by the BSP holds — but the pipeline story is different: the next contract is harder to land, the wait between contracts is longer, and the household that lives entirely on one OFW salary is structurally exposed to a slowdown already underway.
The response is not anxiety. It is architecture: an OFW income floor the household owns before it is needed.
Table of Contents
What an Income Floor Is — and Why It Beats an Emergency Fund
An emergency fund covers an expense surprise; an income floor covers an income problem — the deeper and longer-lasting event this year’s deployment data describes.
The floor is the minimum monthly cash flow a household can count on from sources that do not depend on the OFW’s current contract surviving: the home-side earner’s wages, a micro-enterprise’s profit, dividends from assets already owned, rental income if any exists.
When the floor covers survival, every other decision — accepting a worse contract, waiting out a hiring freeze, funding a certification — gets made from stability instead of fear.
The distinction matters because the OFW salary, however generous, is structurally a temporary income: contracts end, agencies dispute, conflicts repatriate, economies reprice.
The floor is the household’s answer to a question the deployment data just asked loudly: what does the family live on if the deployment income stops for six months? The household that cannot answer owns the risk; the household that can has the floor.
Step One: Name the Floor Number
The floor number is not the family budget — it is smaller and more honest. List the non-negotiables: food, utilities, housing, the children’s school basics, the medicines, the minimum debt service. Exclude the lifestyle layer — the allowances, the upgrades, the subscription economy — because the floor’s job is survival with dignity, not habit preservation.
Most Filipino households discover the number is 40-60% of their actual budget: the spending that feels mandatory is largely the lifestyle layer the OFW salary funds and the floor does not have to.
The exercise has a second function: it reveals what the gap must cover. A household whose floor is ₱35,000 and whose home-side earner can produce ₱20,000 has a ₱15,000 monthly floor gap — a specific, fundable number that turns an anxiety into a project.
The family that writes the number on paper has done the hardest part of income-floor planning, because every subsequent decision has a target.
Layer One: the OFW Salary With Contract-Gap Coverage
The OFW salary layer is not rejected in the floor architecture — it is restructured to acknowledge its true nature: high-value but temporary. Three upgrades convert the salary into floor-worthy income.
First, the contract-gap buffer: three months of the floor number, held liquid, so a between-contracts period is funded by plan rather than panic — distinct from the general emergency fund because it exists to bridge known renewal cycles.
Second, the skills ledger: certifications that survive borders — the careworker’s renewals, the engineer’s licenses, the seafarer’s tickets — because deployability is the salary’s real asset, and this year’s data says the deployable worker with current certifications moves faster through a slow market.
Third, the benefits layer: SSS contributions maintained through gaps (the LoanLite facility this site covered keeps membership continuous), Pag-IBIG I running, OWWA current — the government floor that pays regardless of which agency employed you.
Layer one’s output is a salary that survives its own interruptions: buffered, certified, and government-backed. That is the deployable half of the floor — and it is only half, because the deployment statistics say the salary itself is the uncertain variable in 2026.
Layer Two: the Home-Side Earner That Pays Without a Deployment
The floor’s load-bearing layer is income that flows in the Philippines, without a deployment: a spouse’s second job, the micro-enterprise the family already half-runs, the sari-sari upgrade, the online selling operation, the rented room, the farm plot producing cash crops, the dividend stream from the funds the OFW has been building.
The design principle is redundancy of payer — the home-side income must depend on employers, customers, or assets that do not share a fate with the OFW’s contract. A spouse teaching at the local school fails with the OFW’s employer zero times out of a hundred; that independence is the point.
The build sequence starts from the household’s existing assets, not from fantasy businesses. The spouse with a teaching license who has never formalized private tutoring is a floor-earner waiting for a schedule. The family land idle since the OFW left is a farm-rent conversation.
The remittance stream that funds consumption can redirect ₱2,000-₱5,000 monthly for six months to capitalize a micro-enterprise with proven local demand.
The realistic target for most households: a home-side layer covering 50-100% of the floor number within 24 months — not a fantasy of replacing the OFW salary, but a floor the family can stand on while the OFW finds the next contract or builds the next skill.
The Remittance Restructure That Finances the OFW Income Floor
Here is the part most OFW households skip: the floor is financed from the current remittance, not from future luck. The restructure redirects a slice of every send — commonly 10-15% — from consumption to floor-building: capitalizing the micro-enterprise, funding the spouse’s certification, building the contract-gap buffer.
The discipline is the send-timing system this site covered: automate the floor slice to arrive in a separate account the household budget does not touch, and the floor builds itself at the pace of the remittance calendar.
The sequencing matters: buffer first (because a gap can start next month), certification second (because deployability decays), enterprise last (because businesses need the first two layers stable to survive their slow months).
The households that invert the order — enterprise first, buffers later — meet their first slow quarter with an illiquid business and no buffer, which is the most expensive possible version of the lesson.
The 24-Month Timeline to a Slump-Proof Household
Months 1-3: name the floor number, open the separate floor account, redirect the first 10% remittance slice, list the household’s deployable assets and skills.
Months 4-9: build the contract-gap buffer to three months of floor; start the home-side earner at pilot scale — the tutoring, the plot, the store — and measure its real monthly yield, not its optimism.
Months 10-18: scale what measured well; formalize what the household wants to keep (business registration, the second earner’s credentials); bring the SSS and Pag-IBIG records current. Months 19-24: test the floor — one month of spending it intentionally to verify the number, the accounts, and the flows work when called.
A household that completes the test has converted the deployment data from a headline into a structural advantage: the next 34% drop lands on a floor, not on a family.
The deployment data will keep moving — markets will reopen, quotas will shift, conflicts will end.
The floor is the household’s response to all of those futures at once: built once, maintained cheaply, owned permanently — the OFW income floor is the household structure this deployment year was always going to demand, and the families that build it first will lend the others the playbook.
The Children’s Layer: Why the Floor Is Inheritance, Not Insurance
The quiet beneficiary of an OFW income floor is the next generation’s worldview. Children raised in a household with a home-side earner watch money get made through systems — a business run, a certification earned, an asset managed — rather than through a single heroic salary arriving from abroad.
The financial-socialization effect compounds: the second generation inherits the floor architecture, the buffer habit, and the multiple-payer principle, which is the intergenerational version of what every OFW family says it wants — the remittances to become something permanent.
The estate dimension completes the design: a household with a floor has assets with independent cash flows, which is precisely what makes inheritance manageable — the rental unit passes with its tenant, the store passes with its suppliers, the certificates pass with their renewals.
The OFW income floor is the most inheritance-friendly structure the family can build, because everything in it is already designed to pay without supervision.
The Story Test: What a Floor Changes in a Real Conversation
The architecture becomes real in the conversations it changes. The agency dispute that used to mean a family crisis becomes a calendar problem, because the floor covers the gap the dispute creates.
The parent’s illness that used to trigger a remittance surge and a debt spiral now meets a buffer and a home-side earner already running.
The jobseeker in the frozen pipeline — and the 2026 data says there are thousands — is a family member with a certification schedule and a floor contribution, not a dependent whose anxiety compounds everyone’s. The floor does not change the probability of hard months; it changes what hard months require: planning instead of improvisation.
Frequently Asked Questions
How much should the contract-gap buffer hold?
Three months of the floor number — the minimum non-negotiable budget, not the full lifestyle budget — is the standard starting target for OFW households facing renewal-cycle uncertainty.
What counts as a home-side income layer?
Any income that flows without the OFW’s contract: a spouse’s job or business, rental income, dividends, micro-enterprise profits — the key requirement is that its payer does not share the OFW contract’s fate.
We send everything home now — how do we find the 10-15% to redirect?
Start with 5% and the household budget review it forces; most families discover the lifestyle layer absorbs the cut once it is named and separated — the floor account’s independence is what makes the redirect sustainable.
Is the OFW income floor still worth building if deployments recover?
Yes — the floor protects against all income interruptions (illness, agency disputes, early repatriation, retirement), not only this year’s deployment slump; the 2026 data just made the case urgent.
What should the OFW do while between contracts?
Protect deployability (certifications current, skills ledger maintained), keep SSS/Pag-IBIG contributions running, and operate the home-side earner — the between-contracts period is when the floor pays for its own existence.
How does this connect to the remittance-timing plan?
The remittance calendar funds the floor: the automated floor slice arrives with each scheduled send, so the household builds its floor at the same cadence it pays its bills — one system, two outputs.
Financial Disclaimer: This article is for general information only and is not professional financial advice. Household financial situations vary; consider consulting a registered financial planner for personal decisions.