Table of Contents
Key Takeaway
- 🧠 The shortage is real and dated: the HBM memory shortage began when AI servers started consuming the majority of advanced memory output — SK hynix announced its entire 2026 HBM supply sold out, and the three big makers (Samsung, SK hynix, Micron) are reported fully allocated into 2027.
- 💸 You are already paying for it: consumer DDR5 RAM prices have roughly doubled since mid-2025 — not because of a chip ban or a pandemic, but because fabs reallocated wafer capacity toward data center memory at 3-5x the margin.
- 🏭 The symbol of the shift: Micron formally exited the Crucial consumer brand (announced Dec 3, 2025) to divert silicon to data center customers — the first time a major memory maker has publicly picked AI over PC users.
- 🔬 HBM is a different chip, not a pricier stick: HBM4 doubles the interface to a 2,048-bit width on a JEDEC standard, delivering bandwidth near-TB/s per stack — and it costs roughly 3x the wafer capacity of a DDR5 bit.
- 🕓 When it eases: new fab capacity lands no earlier than 2027; until then, expect gadget prices to keep absorbing AI’s memory bill.
If your next laptop, phone, or GPU price quote made you blink, you have met the HBM memory shortage without knowing it. In mid-2025 a 32 GB DDR5 kit was a routine purchase; by late 2026 the same modules routinely price at two to three times that. The cause is not a demand spike on your side — consumer PC sales are flat — but a quiet reallocation on the supply side: the world’s memory makers are feeding AI data centers first, at margins consumer sticks can never match. This article explains what HBM actually is, why the shortage is structural rather than a hype cycle, how the consumer market is absorbing the shock, and what signals to watch for relief.
What HBM Actually Is: Memory Built Sideways
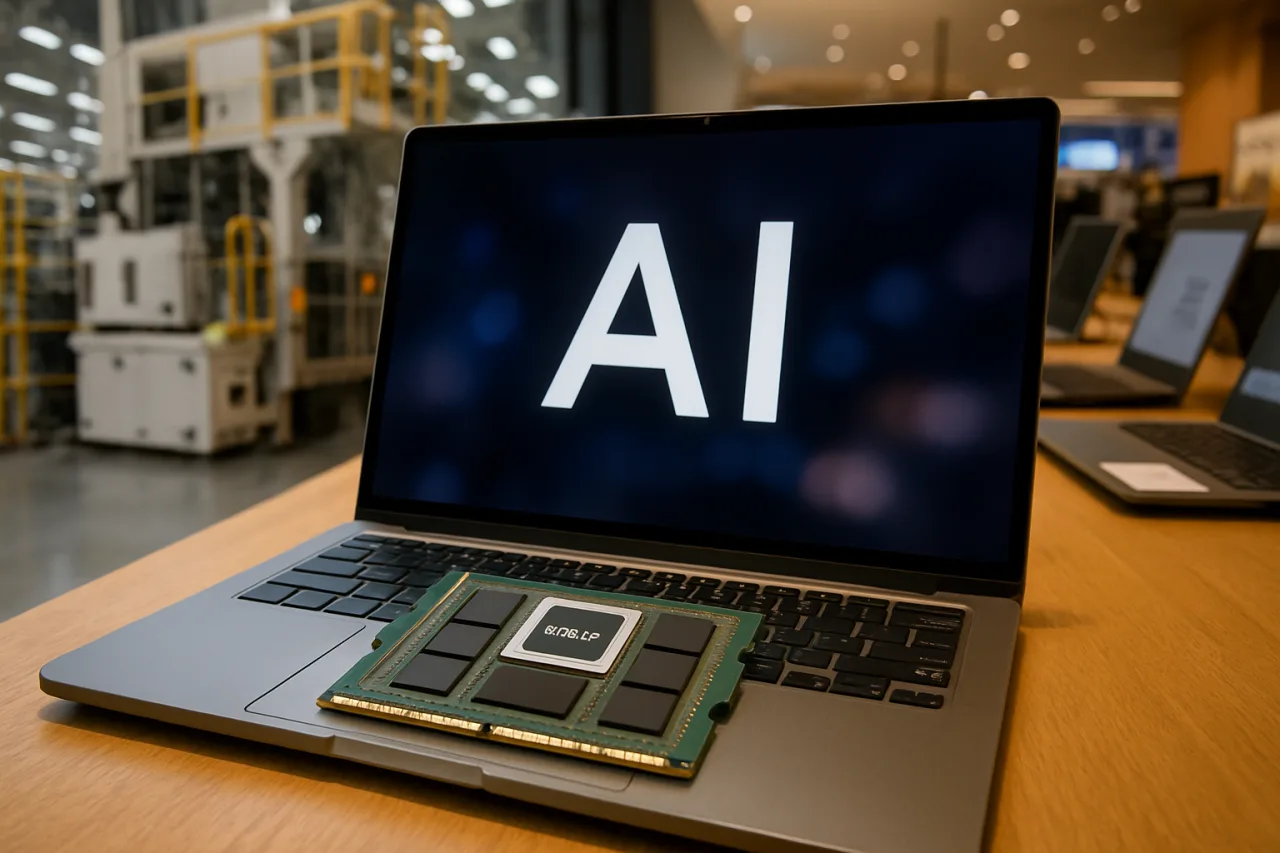
High Bandwidth Memory (HBM) is DRAM engineered vertically. Instead of one flat die wired to a circuit board, HBM stacks eight or more DRAM dies on top of each other and connects them with thousands of microscopic through-silicon vias, then places that stack millimeters from the AI accelerator itself. The HBM memory shortage story starts with that design decision: memory bandwidth measured in terabytes per second rather than gigabytes — roughly an order of magnitude beyond conventional DDR5.
Every major AI accelerator depends on HBM — the product at the center of the hbm memory shortage. A modern flagship GPU or TPU carries its HBM stacks on-package; a fully configured rack of flagship AI servers contains tens of thousands of DRAM dies just in its HBM modules, before counting the system’s main memory. That dependence is why a shortfall in one specialized product can reprice the entire electronics market: HBM is the memory AI cannot run without.
Why the HBM Memory Shortage Is Structural, Not a Hype Cycle
Memory markets have always cycled — gluts and shortages on a rough two-to-three-year rhythm. The current shortage breaks the pattern in three verifiable ways.
1. The customer changed. For decades the marginal buyer of DRAM was a consumer upgrading a PC. Today the marginal buyer is a hyperscaler building an AI campus, and hyperscaler demand is famously insensitive to price: a company training a frontier model does not defer its build because DRAM got expensive. CSIS’s analysis of the shift notes AI demand’s price inelasticity as the core structural break — and quotes industry leaders expecting AI demand to “overwhelm all other sources of demand” through the end of the decade.
2. The arithmetic of HBM production eats the wafer. Producing a given bit capacity of HBM consumes roughly three times the wafer capacity of producing the same capacity in standard DDR5, thanks to stacking yield losses and a doubled interface that needs more silicon per bit. That is why SK hynix reported holding less than ten days of finished DRAM inventory at one point in 2026 — the tightest position since the last pricing crisis — while global DRAM industry revenue still hit record levels. Scarcity and record revenue coexisting is the signature of a structural shift, not a demand lull.
3. The capacity is contracted years out. SK hynix stated it has “already sold out our entire 2026 HBM supply” (CFO statement) — the anchor data point of the hbm memory shortage — Micron confirmed full bookings through 2026 with long-term agreements beyond, and trade reporting puts all three makers’ DRAM and HBM allocation effectively sold out into 2027. New fabs — SK hynix’s M15X, Samsung’s Pyeongtaek expansions — take three to five years and tens of billions of dollars; capacity lands in 2027-2028, not now. A shortage with contracted supply and multi-year capacity lead times is a queue, not a mood.
The Hard Part: Why HBM Is So Difficult to Manufacture
Understanding the HBM memory shortage requires understanding why this particular product resists the classic memory-industry fix of “just build more fab lines.”
Yield compounds downward. A conventional DDR5 die either works or it does not; a bad die is discarded and the rest ship. In HBM, eight to sixteen dies must each function, then survive the bonding process that fuses them vertically. If each die yields 90 percent and stacking success adds its own loss, the finished-stack yield falls far faster than any single layer’s — math that makes every new fab’s effective output grow much more slowly than its wafer count suggests.
Every stack needs a brain. Each HBM stack sits on a base die that routes signals and manages heat — and starting with HBM4, that base die increasingly requires leading-edge logic manufacturing rather than simple memory-class silicon. SK hynix formalized a partnership with TSMC precisely for this: memory companies now depend on the same advanced foundry capacity that every AI accelerator maker is fighting for, adding a second bottleneck behind the first.
Assembly is part of the product. SK hynix’s advanced packaging technique (MR-MUF) is cited across the industry as a durability and throughput advantage; packaging floors, not just wafer fabs, set the ceiling on output. The result is an industry where capacity expansion means coordinating cleanrooms, foundry slots, and packaging lines at once — the slowest of the three governs, and none moves quickly.
The Micron Exit: The Day the Consumer Market Got the Memo
The clearest single symbol of the shift arrived on December 3, 2025, when Micron announced it would exit the Crucial consumer business, discontinuing its own retail RAM and SSD brand so the silicon could be redirected to its larger, faster-growing data center customers, as Chief Business Officer Sumit Sadana explained in the announcement. Consumer shipments run through the end of Micron’s fiscal Q2 (February 2026); warranty support continues, but the message is permanent: when memory gets scarce, the data center eats first.
The consequences did not stay corporate: the hbm memory shortage reached store shelves within months. DDR5 retail prices roughly doubled (and on some kits tripled) between mid-2025 and late 2026; smartphone makers began trimming memory configurations to defend margins; and industry analysts began downgrading PC makers on memory-cost exposure. A shortage in one product class re-priced devices that never mention HBM anywhere on the box — the same memory math behind server rental increases our coverage tracked when AI server prices jumped 15 percent.
What HBM4 Changes: The Next Round of the Same Race
The HBM memory shortage has a paradoxical second act: the industry’s answer to scarcity is a bigger, faster product — and it repeats the same dynamics at higher stakes. SK hynix completed the world’s first HBM4 development and mass-production readiness (September 2025), with 2,048-bit interfaces, more than double the bandwidth, and over 40 percent better power efficiency than its predecessor; JEDEC ratified the HBM4 standard (doubling the interface width to 2,048 bits) in April 2025. Both Samsung and SK hynix began HBM4 mass production in 2026, each sold out, with Micron certified as the third qualified supplier on NVIDIA’s next-generation Rubin platform.
But HBM4 intensifies rather than relieves the fundamentals: a 2,048-bit interface with more layers per stack consumes even more cleanroom capacity per bit, deepening the wafer squeeze while the money gets better. UBS projects SK hynix holding roughly 70 percent of the HBM4 market on NVIDIA’s Rubin platform — a concentration story with real supply-chain implications. The deeper lesson for readers: every generation of AI hardware raises the memory bill underneath it. Our data center power analysis shows the same pattern on the electricity side — each acceleration generation multiplies facility demand.
The Workarounds: What Buyers and Makers Are Doing Now
Shortages breed adaptation, and the memory crunch is no exception — the responses themselves are worth watching.
Substitution. Server makers are re-specifying designs around what is actually procurable: trimming per-node memory, adopting DDR5 variants built on squeezed processes, and in some AI-adjacent systems substituting LPDDR server modules (originally a phone technology) where bandwidth demands allow. None of it is free — each substitution trades some performance for availability — but it keeps product lines shipping.
Contract re-shaping. The industry’s pricing model has shifted from spot market to long-term agreements: hyperscalers pre-pay for capacity years ahead, converting memory from a commodity into something closer to contracted infrastructure. That is precisely why record revenues and empty shelves coexist — the queue is priced, not just filled.
Sunset of the old world. Legacy DDR4 production — the memory of the pre-AI PC era — is being retired early, pushing any remaining value to DDR5 platforms and accelerating upgrade cycles. For the HBM memory shortage to ease, all three responses have to mature simultaneously: new capacity, substitution designs, and a demand curve that finally grows slower than supply.
How Long Will the HBM Memory Shortage Last?
Three defensible answers, by information class:
Established engineering facts: fab lead time (3-5 years), the 3x wafer penalty of HBM production, JEDEC interface standards — stable knowledge.
Slow-changing figures: quarterly inventory days, price indices, maker market shares — verify at each refresh.
Fast-moving claims to treat skeptically: “fully sold out through 2027” statements (vendor communications can overshoot their own order books) and every projection attached to a product roadmap. Nothing in this article should be read as investment advice on any memory stock — for the market-side view, our World Investment Watch on Micron’s $61.5 billion memory signal covers the numbers investors actually quote, with the market’s own disclaimers attached.
Base case: the pressure holds through 2026-2027 until new fab capacity (M15X, Pyeongtaek, Micron’s US expansions) and slower customer growth rebalance the market. Structural shifts of this kind typically relax in stages — consumer pricing first, then enterprise allocation windows — not all at once.
What Readers Can Actually Do About It
Practical guidance for the pricing reality:
- Buy RAM now if you need it this year; waiting prices out nobody — every credible forecast has memory costs staying elevated through 2027, and no announced fab changes that before 2028.
- Do not overbuy capacity you will never use — higher densities carry the largest percentage increases, and 2027 re-balancing should let mid-capacity kits (32-64 GB class) drop first.
- Phone buyers: expect less RAM at the same price point through 2027 — makers absorbing memory costs usually trim configurations before raising flagship prices.
- Builders of local AI rigs: the math still works — one 32 GB DDR5 kit at 2026 pricing still costs less than a year of cloud inference for a daily-use local model, and the NPU/LPDDR platform trend favors machines that hold their value.
- Watch the used market for a temporary premium inversion: 2024-2025 DDR5 modules now carry a resale premium — checking both before buying new is worth minutes.
FAQ: HBM Memory Shortage Questions
What is the HBM memory shortage?
The HBM memory shortage is the global supply crunch in high-bandwidth memory — the stacked DRAM used by every major AI accelerator — that began when AI data center demand outgrew available production capacity. Its effects spill over to all memory prices: makers reallocate fab capacity to HBM and server DRAM, constricting consumer DDR5 supply even though consumer demand never rose.
Why is DDR5 RAM so expensive in 2026?
Because memory makers shifted wafer capacity toward higher-margin AI and server products (HBM takes about three times the wafer per bit of DDR5), while legacy DDR4 lines are being sunset. Consumer demand is unchanged — the supply available to it shrank, so prices doubled.
Why did Micron stop selling Crucial RAM?
Micron announced on December 3, 2025 that it would exit the Crucial consumer business to prioritize supply for data center customers, with consumer shipments ending by February 2026. It is the clearest example of a memory maker publicly reallocating scarce capacity from the PC market to AI.
Is HBM the same as DDR5?
No. HBM stacks DRAM dies vertically and connects them to the processor at terabyte-per-second speeds over a very wide interface; DDR5 is a conventional module for system memory. HBM4’s interface is 2,048 bits wide — double DDR5’s channel width — which is why it is manufactured differently and priced accordingly.
When will RAM prices go back down?
New memory fab capacity starts contributing in 2027-2028; most industry forecasts expect pricing pressure through 2026-2027 with relief staged thereafter. Anyone promising a specific month is forecasting, not reporting — watch inventory days, maker capacity announcements, and quarterly price lines rather than headlines.
Does the HBM shortage affect my phone or my new laptop?
Yes, indirectly: handset makers trim memory configurations (some cut RAM on mid-range models) as LPDDR prices rise, and laptop pricing has absorbed DDR5 increases since mid-2025. The effect is one component cost among several — but it is currently the fastest-moving one in device BOMs.
Sources and Further Reading
- Micron — Micron Announces Exit from Crucial Consumer Business (Dec 3, 2025): investors.micron.com
- SK hynix Newsroom — World’s First HBM4 Development/Mass Production Readiness (Sept 2025): news.skhynix.com
- SK hynix Newsroom — 2026 Market Outlook: HBM-led supercycle: news.skhynix.com
- CSIS — Beyond the Memory Cycle: AI, HBM, and the New Semiconductor Shortage: csis.org
- JEDEC — HBM4 standard (JESD270-4, April 2025): jedec.org
- Introl — South Korea’s HBM4 moment (industry tracker): introl.com
If this intelligence helps you, you can add WorldNgayon as a preferred source on Google — free, one click, and it helps other readers find the answers faster.