Table of Contents
Key Takeaway
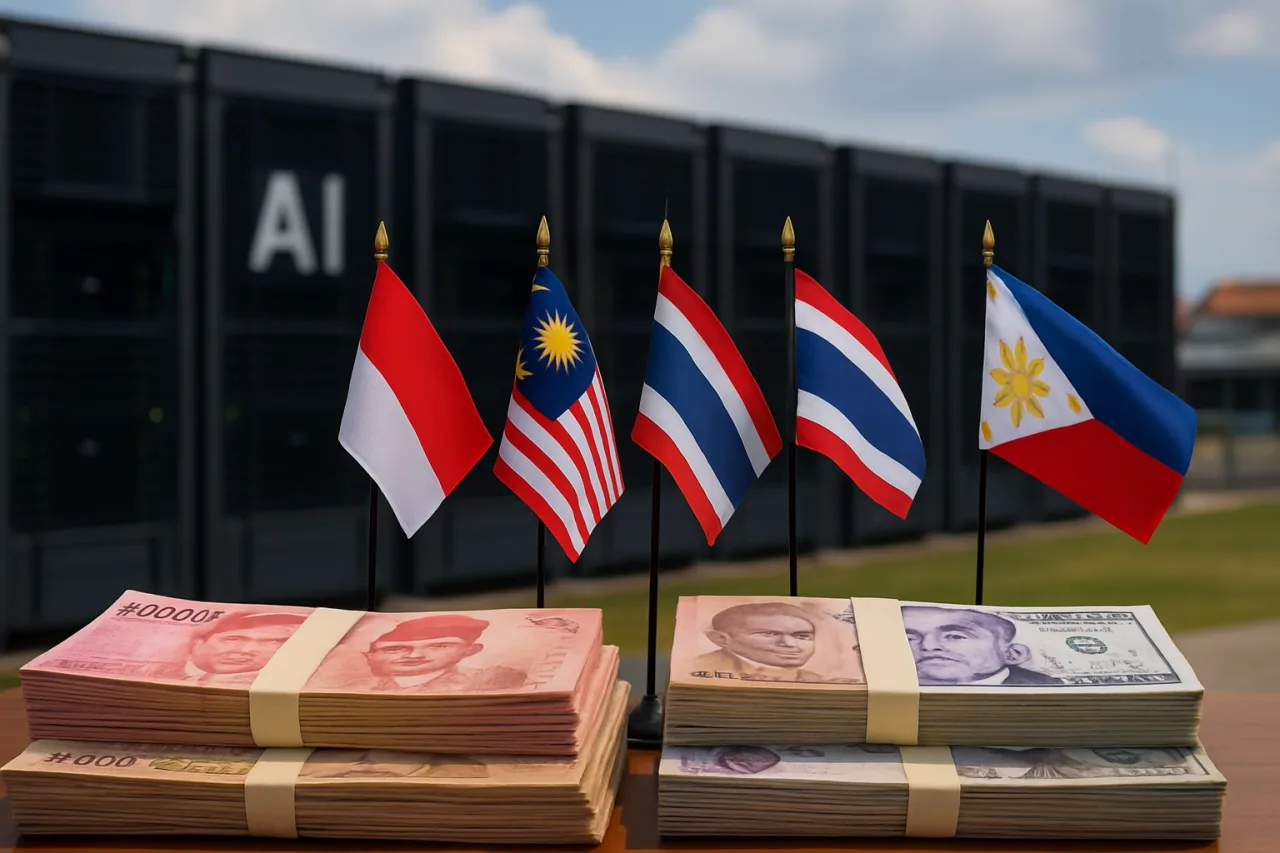
The Southeast Asia AI infrastructure race stopped being a software story and became a land, power and financing story in one week. Indonesia locked a $3.1 billion loan (dated October 6, 2026, eWeek/Zankore financing announcement) to build its first 100MW of Nvidia-powered compute. Thailand’s Board of Investment approved four data centers worth $3.1 billion on the same beat (Thai Times, October 7, 2026) and moved to unblock $9.2 billion more. Singapore confirmed a $7.8 billion chip fab (EDB, October 7, 2026). The Philippines opened an AI-ready data center in Pampanga with the President on stage (Manila Times, October 7, 2026). Five countries, one auction: whoever has the megawatts gets the models.
SOUTHEAST ASIA AI INFRASTRUCTURE: THE GIGAWATT RACE
Southeast Asia AI infrastructure now runs on gigawatt math, not app math
The week’s numbers belong in one table because they share one logic: compute capacity, priced in dollars, built on land and electricity.
| Country | Announced this week | Capacity | Date |
|---|---|---|---|
| Indonesia | Zankore $3.1B senior term loan (Citi advised) | 100MW initial, 1GW target | Oct 6, 2026 |
| Thailand | BOI approves 4 DCs ($826M + $1.7B + $234M + $306M) | 376MW combined | Oct 7, 2026 |
| Singapore | Vanguard + NXP $7.8B fab (EDB-confirmed) | capacity undisclosed | Oct 7, 2026 |
| Philippines | Converge ICT AI-ready DC, Angeles City | capacity undisclosed | Oct 7, 2026 |
Read the table as one auction for Southeast Asia AI infrastructure. The countries are bidding for the same pool of GPU dollars, and the bidding has moved from press releases to loan documents. Zankore’s financing is the proof: a $3.1 billion senior term loan facility, with Citi as exclusive debt adviser, means banks now underwrite Southeast Asia AI infrastructure the way they underwrite ports and power plants.
Why Indonesia’s $3.1 billion Zankore loan is the week’s anchor
Zankore is the AI infrastructure platform launched by Indosat Ooredoo Hutchison with Ooredoo Group, Nvidia and Nokia. In August the group announced a target of up to 1 gigawatt of Nvidia DSX AI Factory capacity. The loan moves from target to concrete. About 100 megawatts come first, serving AI companies, enterprises, startups, developers and institutions inside Indonesia and across Southeast Asia. The first 200 megawatts are slated for the first half of 2027, powered by Nvidia GB300 NVL72 systems, with construction in Batang, Central Java, targeted to begin in the first half of 2027.
The Indonesian numbers sit inside a national ambition. Jakarta has tied the project to its goal of becoming a regional AI hub, and analysts have tracked national data center capacity racing past 2 gigawatts by 2030. The constraint is no longer appetite; it is power, land and predictable permitting.
Thailand’s Board of Investment is buying speed
Thailand answered the Southeast Asia AI infrastructure race with administrative horsepower. The Board of Investment approved four data-center projects worth roughly US$3.1 billion: NextGen Data Centre and Cloud Services, a subsidiary of Dubai’s DAMAC Digital, gets an 84-megawatt facility at Navanakorn Industrial Estate in Pathum Thani valued at THB 26.7 billion (about US$826 million). Local investor Zenith plans a 200-megawatt hyperscale facility on the same estate, worth THB 54.9 billion (about US$1.7 billion). Japan’s Telehouse adds a 12-megawatt Bangkok project (THB 7.55 billion, about US$234 million), and Vistas Technology — a subsidiary of China’s ZDATA — builds 80 megawatts in Amata City Chonburi (THB 9.9 billion, about US$306 million).
The parallel move matters more: six new licences to expedite roughly US$9.2 billion in previously stalled projects, aimed at bottlenecks in power supply, industrial land access and visa and work-permit processing. BOI Chairman Narit Therdsteerasukdi framed the combined strategy as strengthening investor confidence. In a buildout where the scarcest input is regulatory predictability, that is a competitive weapon.
Singapore plays a different game: the $7.8 billion fab
While its neighbors court GPU megawatts, Singapore answered with silicon. The Singapore Economic Development Board confirmed that Vanguard International Semiconductor, a TSMC affiliate, will build a $7.8 billion semiconductor plant with NXP Semiconductors. Details remain thin — no construction timeline, capacity figures or process node disclosures came with the announcement — but the signal is not subtle: the city-state is doubling down on being the region’s stable, geopolitically neutral manufacturing anchor while it caps greenfield data center growth on power and land grounds.
Singapore’s second Data Centre Call for Application adds at least 200 megawatts of capacity, explicitly balancing AI demand against energy-efficiency and sustainability requirements. The city-state is not trying to win the megawatt auction. It is trying to host the chips and the capital markets that the megawatt countries need.
The Philippines enters with sovereignty, not scale
President Ferdinand Marcos Jr. visited a newly opened AI-ready data center in Angeles City, Pampanga, operated by Converge ICT Solutions — the government’s data-sovereignty and digital-economy push made physical. The Philippine entry is smaller in dollar terms than Indonesia’s loan or Thailand’s approvals, but it carries the domestic political weight of an actual ribbon-cutting: local enterprises and government bodies getting compute on Philippine soil instead of queues in Singapore.
The Southeast Asia AI infrastructure scoreboard still prices the Philippines as a challenger. The pattern to watch is whether power pricing and land availability convert the sovereignty narrative into gigawatt commitments in 2027, or whether the country remains a services and talent story feeding its neighbors’ data centers.
Taiwan’s supply chain is the connective tissue
None of these Southeast Asia AI infrastructure plans build themselves. Nikkei Asia reported October 7 that TSMC and other Taiwanese companies have stepped up overseas investment — the same hyperscaler capex wave we tracked on the Nvidia capex wall as they rush to build out supply chains able to handle surging AI computing demand, with spending concentrated in the US and Southeast Asia. Siam.AI Cloud’s Thailand plan reads the same way: 70 billion baht this year, 10 billion baht already invested, and a Nvidia GB200 NVL72 supercomputer module — Siam.AI says it is the first Nvidia Cloud Provider in Asia running that module — hosted at ST Telemedia’s STT Bangkok 1 facility.
The Taiwan connection of the Southeast Asia AI infrastructure buildout cuts both ways for the region. It supplies the hardware that makes national ambitions real, and it concentrates the region’s dependencies: whoever hosts the next-generation modules first — GB200 in Bangkok now, GB300 in Indonesia by 2027 — holds a real advantage for enterprise workloads that care about latency and data residency.
The power problem: why electricity decides the Southeast Asia AI infrastructure map
Every commitment announced this week converts into the same three inputs: reliable megawatts, water or cooling, and land close to demand. Singapore turned its scarcity into policy — the second Data Centre Call for Application adds at least 200 megawatts while explicitly balancing AI demand against energy-efficiency and sustainability requirements. That cap is the engine behind its neighbors’ booms: when the region’s financial capital stops accepting greenfield builds, the GPU dollars overflow into Johor, Batam, Patum Thani and Java. Indonesia’s Zankore buildout in Batang and Thailand’s Navanakorn cluster are downstream of that single Singapore decision, made years ago.
The data-center buildout wave also redraws the regional threat map — see our Philippines data breach statistics hub. The electricity economics explain the geography. A one-gigawatt AI campus draws the continuous load of a mid-sized province, and the countries that can price industrial power predictably — rather than just cheaply — are the ones lenders will finance. Citi’s decision to advise the $3.1 billion Zankore facility as exclusive debt adviser is a bank pronouncing Indonesia’s power and permitting risk acceptable for a decade-long asset. That is the real grading system of the Southeast Asia AI infrastructure race: not headline dollars, but loan tenor.
Financing tells the truth press releases don’t
Look at how each project is moneyed. Indonesia: a senior term loan with a global bank advising — institutional debt. Thailand: Board of Investment approvals that unlock tax breaks, land privileges and expedited permits — state-backed attraction of mostly private capital. Singapore: a fab commitment by two established chipmakers inside a stable manufacturing base — corporate balance sheets. The Philippines: a ribbon-cutting on domestic capital from a listed telecom-infrastructure company — local equity. Four different capital structures, one shared race, and each betrays what its backer believes the risk actually is.
That framing matters for anyone tracking Southeast Asia AI infrastructure numbers: a $3.1 billion loan facility, a $9.2 billion unblocking program and a $7.8 billion fab are three different kinds of certainty. The loan is signed intent with a schedule. The unblocking program is administrative hope with a target. The fab is a commitment whose timeline remains undisclosed. Treating them as interchangeable dollars is how regional tech coverage inflates — and why dates and instruments belong in every sentence about the race.
Batam and the Penang lesson Indonesia is racing to apply
Regional reporting has already drawn the historical parallel: economists warned in early October that unilateral regional shutdowns could repeat the policy failures that pushed global semiconductor investment out of Indonesia decades ago — when Penang captured the assembly and test business that Batam’s geography had courted. Indonesia today holds at least 182 operational data centers, 94 of them in Jakarta and 16 in Batam, with national capacity projected past 2,000 megawatts by 2030 at compound annual growth the World Bank pegs near 16.8 percent. The industry association IDPRO has asked for unified single-window licensing, formal pre-consultation before groundbreakings and binding regulatory service-level timelines — precisely the predictability instruments whose absence once redirected chip investment across the strait.
Batam’s advantage is structural: a 7 percent local growth rate, proximity to Singapore’s capped market, and space to absorb between $15 billion and $20 billion in dedicated compute facilities, anchoring roughly 1.3 gigawatts of national capacity. If Jakarta keeps its permitting predictable, the island becomes the default overflow valve for Singapore-exiled demand. If it doesn’t, the same capital that just signed Indonesia’s loan will price the unpredictability and route through Thailand instead.
DATES AND DISCIPLINE: READING THE WEEK CORRECTLY
| Item | What is actually confirmed | What is aspiration |
|---|---|---|
| Zankore, Indonesia | $3.1B senior term loan; initial 100MW | 1GW DSX AI Factory capacity within three years |
| Thai BOI approvals | Four projects, ~$3.1B, licensed | Jobs and full construction schedules |
| Thai BOI expedite licences | Six licences announced | The $9.2B actually moving |
| Singapore fab | $7.8B commitment, EDB-confirmed | Timeline, node, capacity |
| Siam.AI, Thailand | GB200 NVL72 running at STT Bangkok 1 | 70B baht invested this year; 200MW own-build |
READ-THROUGH: WHAT IT MEANS FOR FILIPINO READERS
Jobs follow the megawatts, not the press releases
Thailand’s BOI explicitly tied its approvals to employment and broader economic development. Indonesia’s Ministry of Communication and Digital Affairs described Zankore as a major step toward the regional Southeast Asia AI infrastructure hub ambition, projected to reach up to 1 gigawatt within three years. For Filipino engineers, technicians and data professionals, the signal is directional: the compute jobs of 2027-2030 are being located now, and the region that wins capacity will import talent as readily as power.
The OFW read is the same one that applies to every infrastructure boom: these projects hire construction workers, electrical and cooling engineers, security staff and network operators long before they hire AI researchers.
The window to re-skill into data-center-adjacent trades is open while the concrete is still wet.
Costs of electricity in the Philippines against regional rivals stay decisive.
For the Philippines, the strategic question is blunt: Southeast Asia AI infrastructure momentum is being financed this month, and the countries writing signed loan documents are the ones that will set latency prices in 2027. The Converge facility in Pampanga gives the country its first real entry ticket into that conversation. Converting it into gigawatt-scale commitments — the way Indonesia converted an August announcement into a $3.1 billion October loan — is the difference between hosting national workloads and renting regional capacity forever.
For regional watchers, the Southeast Asia AI infrastructure finance checkpoints are three: whether Zankore’s first 100 megawatts actually energize on schedule; whether Thailand’s six expedite licences move the $9.2 billion from stalled to steel; and whether the Vanguard-NXP fab discloses a construction timeline that anchors Singapore’s silicon play in reality. Those three checkpoints decide the region’s compute map by early 2027.
Southeast Asia AI infrastructure is no longer a prediction. It is a construction schedule with names on it, and this week every major economy in the region put its name on the same list. The megawatts are being allocated now — the question for 2027 is only which flags fly over them.
Primary reporting followed for this scoreboard: eWeek on Zankore, Thai Times on the BOI approvals, Die Signal on the Singapore fab, Manila Times on Pampanga, and Thai Times on Siam.AI — each linked figure dated in the text above.
Sources for this week’s Southeast Asia AI infrastructure scoreboard: Zankore financing announcement ($3.1 billion senior term loan, reported by eWeek October 6, 2026); Thailand Board of Investment approvals and six expedite licences (Thai Times, October 7, 2026); Vanguard International Semiconductor and NXP $7.8 billion Singapore fab, confirmed by the Singapore Economic Development Board (Die Signal, October 7, 2026); Converge ICT Solutions AI-ready data center in Angeles City (Manila Times, October 7, 2026); Taiwan overseas AI supply-chain spending (Nikkei Asia, October 7, 2026). Figures are as announced; no capacity estimates were added where primary sources did not disclose them.