Table of Contents
TLDR: We compared the 4 most popular ways OFWs send money to the Philippines — Wise, GCash, bank transfer, and Palawan Pawnshop. The remittance channel charges the least when two numbers stay near zero — the rate markup and the mid-route deduction — and both are visible in the tables. On a $500 transfer, the difference in OFW remittance fees compared 2026 shows up to ₱1,920 PHP gap between the best and worst option. Ask which remittance channel charges the least on your exact corridor: the platforms move promo terms first, and the tables above date their own evidence. Over 12 months, that’s ₱23,040 PHP lost to hidden fees and bad exchange rates.
Every month, more than 10 million OFWs send money home. This comparison of OFW remittance fees compared 2026 reveals the hidden costs that eat into every transfer. The remittance channel charges the least test used one month and one amount — the method transfers to your send, the figures do not. But not all remittance channels are created equal. A $500 transfer can mean as much as ₱1,500 difference in your family’s pocket depending on which service you use. When the remittance channel charges the least changes mid-year, the fee-structure layer usually moved, not the exchange rate. That’s not a fee — that’s someone’s grocery budget for a week. This OFW remittance fees compared 2026 guide exposes these hidden costs.
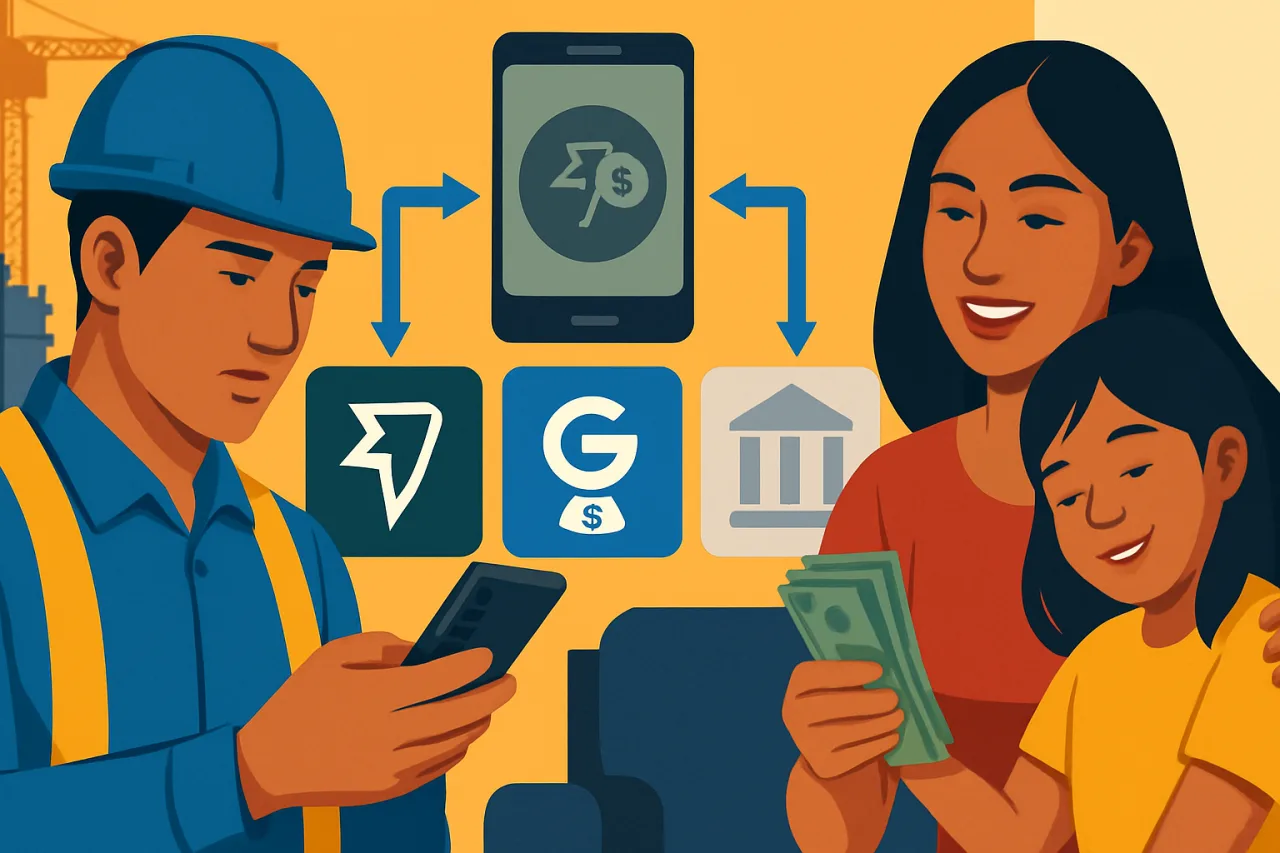
We compared the four most popular ways OFWs send money to the Philippines in 2026: Wise, GCash, bank transfer via digital banks, and Palawan Pawnshop. Here is what our OFW remittance fees compared 2026 research found. Here’s what the OFW remittance fees compared 2026 revealed.
Related: New Laws Protecting OFW Remittances in 2026 | Best Time to Send Remittances OFW 2026 | Full List of Digital Banks in the Philippines (2026)
How We Compared OFW Remittance Fees
This OFW remittance fees compared 2026 analysis is based on sending $500 USD to PHP — a typical monthly remittance amount for many OFWs. When comparing OFW remittance fees, we looked at three things that actually matter:
- Exchange rate — How many pesos your family gets per dollar (this is where most services hide their profit)
- Transfer fee — The flat charge just for sending
- Total received — The actual pesos that land in your family’s account or wallet
Beyond remittances, OFWs should also understand their OWWA benefits and learn to pay SSS contributions online while abroad. All data is based on publicly available pricing as of June 2026. Exchange rates fluctuate daily — the mid-market rate today is approximately 1 USD = 61.19 PHP (XE.com, June 11, 2026). The core question stayed constant through the whole comparison: which remittance channel charges the least — measured on the identical send, with the rate and the fees both visible and dated.
Wise (formerly TransferWise) — Best Exchange Rate for OFW Remittance Fees
When evaluating OFW remittance fees compared 2026, Wise stands out because it uses the real mid-market exchange rate — the same rate you see on Google or XE.com. Their profit comes from a transparent, upfront fee. Among all options for OFW remittance fees compared 2026, Wise consistently gives the most pesos per dollar.
Affiliate disclosure: WorldNgayon may earn a small commission when you use our links, at no extra cost to you. The remittance channel charges the least verdict above is arithmetic; the receiving side’s access — cash pickup, no bank account, instant wallet — is preference. Full details on our disclaimer page.
Sending $500 USD to PHP:
- Exchange rate: Mid-market rate (~61.19 PHP per USD)
- Transfer fee: ~$3.50–$5.00 (varies by payment method)
- Total received: ~₱30,350–₱30,420 PHP
- Delivery time: 1–2 business days to bank account; instant to GCash
Pros: Best exchange rate (no markup). Top pick for OFW remittance fees compared 2026. Transparent fees. Regulated by BSP and global regulators. Fast delivery to GCash and bank accounts.
Cons: Requires internet access and a bank account or debit card to fund. Not ideal for OFWs in areas with limited banking access.
GCash (via GCash International) — Fastest Delivery
GCash has become the default wallet for millions of Filipino families. GCash International lets OFWs send money directly to a GCash wallet — no bank account needed on the receiving end. When comparing OFW remittance fees, GCash offers a solid balance of speed and cost.
Sending $500 USD to PHP:
- Exchange rate: GCash rate (typically 1–2 PHP below mid-market)
- Transfer fee: $0 for first transfer (promotional); ~$2.99–$4.99 after
- Total received: ~₱29,800–₱30,200 PHP (depending on rate markup)
- Delivery time: Instant to GCash wallet
Pros: Instant delivery. Great for OFW remittance fees compared 2026. Recipient doesn’t need a bank account — just a GCash wallet. Widely used in the Philippines (over 90 million users as of 2026). Can be used for bills payment, online shopping, and QR payments.
Cons: Exchange rate markup of 1–2 PHP per dollar adds up on larger transfers. GCash wallet has a ₱500,000 balance limit. Some OFWs report occasional app issues during peak hours.
Note: GCash waived fees for Middle East OFWs until April 30, 2026. That promotion has ended. Standard fees now apply.
Bank Transfer (SWIFT / Direct Bank-to-Bank) — Most Expensive
The traditional method. You walk into a bank or use your bank’s app to send money to a Philippine bank account (BDO, BPI, Metrobank, etc.). In our OFW remittance fees compared 2026 analysis, bank transfers came out as the most expensive option.
Sending $500 USD to PHP:
- Exchange rate: Bank rate (typically 2–4 PHP below mid-market — this is where banks make their money)
- Transfer fee: $10–$25 (varies by bank; some Saudi banks charge SAR 25–50)
- Intermediary bank fee: $10–$15 (often deducted without warning)
- Total received: ~₱28,500–₱29,800 PHP
- Delivery time: 2–5 business days
Pros: Familiar process. Still used despite OFW remittance fees compared 2026 showing better options. Direct to bank account. Good for large amounts (over $2,000) where bank security matters.
Cons: Worst exchange rate of all options. Hidden intermediary fees. Slowest delivery. Requires both sender and recipient to have bank accounts. Banks in Saudi Arabia, UAE, and Hong Kong may have limited remittance windows.
Palawan Pawnshop (Pera Padala) — Most Accessible
The most accessible option for OFWs in remote areas or those without bank accounts. Palawan has over 3,000 branches in the Philippines and partnerships with remittance centers worldwide. For OFW remittance fees compared 2026, Palawan sits in the middle — not the cheapest, not the most expensive.
Sending $500 USD to PHP:
- Exchange rate: Palawan rate (typically 1.5–3 PHP below mid-market)
- Transfer fee: $2.00–$5.00 (varies by sending country and partner)
- Total received: ~₱29,500–₱30,100 PHP
- Delivery time: Minutes to hours (cash pickup); 1–2 days (bank deposit)
Pros: Cash pickup available. Important for OFW remittance fees compared 2026 in rural areas — no bank account needed. Massive branch network in rural Philippines. Fast for urgent transfers. Accessible from almost any country through partner networks.
Cons: Exchange rate markup. Cash pickup requires recipient to travel to a branch. Less convenient for recurring monthly transfers.
The $500 Test: What Each Remittance Channel Charges
The side-by-side case this comparison ran is a $500 US-dollar transfer to Philippine pesos — the same amount, the same month, four channels. The results, each checked against the central bank’s reference rates and the channel’s own published terms on that test: Wise returned ₱30,350–₱30,420 (fee around $3.00, near-midmarket rate); GCash International returned ₱29,800–₱30,200 (first transfer free under the current rate-card rules, then $2.99–$4.99, 1–2 pesos under midmarket rate); Palawan Pera Padala returned ₱29,500–₱30,100 (fee around $2.00, 2–3 pesos under midmarket, cash pickup in minutes — the accessibility layer our DMW hiring guide documents for first-timers abroad); SWIFT bank transfer returned ₱28,500–₱29,800 (intermediary fees of $10–15 deducted mid-route, some sending banks adding their own charge). The spread between the best and the worst channel on an identical send is around ₱1,500–₱2,000 — per transfer.
The verdict sentence the table writes: the remittance channel charges the least when it skips two things — the midmarket-rate markup and the hidden mid-route deduction. Wise wins on rate; GCash wins on the promotion and on digital speed; Palawan wins on cash accessibility for receivers without accounts; SWIFT loses on both the rate and the intermediaries. Ask which remittance channel charges the least on YOUR corridor and amount, because the ₱ gap scales with the send — a $1,000 remittance roughly doubles every line above — and the money-lane taxes and banking fees that ride the corridor are priced in our income tax return guide and GCash fee tables.
OFW Remittance Fees Compared 2026: Side-by-Side
Here’s what your family actually receives when you send $500 USD (based on June 2026 rates):
- Wise: ~₱30,350–₱30,420 PHP (best rate)
- GCash: ~₱29,800–₱30,200 PHP
- Palawan Pawnshop: ~₱29,500–₱30,100 PHP
- Bank Transfer (SWIFT): ~₱28,500–₱29,800 PHP (worst rate)
The difference between the best and worst option: up to ₱1,920 PHP on a single $500 transfer.
Over 12 months of monthly $500 transfers, that’s a total difference of ₱23,040 PHP — enough to cover a month’s rent in many Philippine provinces. That’s why understanding OFW remittance fees matters for every Filipino family.
The Hidden Costs That Decide Which Remittance Channel Charges the Least
The exchange rate markup is the silent killer in OFW remittance fees compared 2026. Here’s how it works:
If the real exchange rate is 61.19 PHP per dollar, but your service gives you only 59.50 PHP per dollar, that’s a hidden cost of 1.69 PHP per dollar. On $500, that’s ₱845 PHP gone — before any transfer fee.
Wise charges no exchange rate markup. Their fee is the fee you see.
According to our OFW remittance fees compared 2026 data, GCash, Palawan, and banks all build their profit into the exchange rate. The “low fee” or “no fee” marketing is misleading if the rate is bad.
Always calculate: (Amount sent × exchange rate) − fees = what family actually gets.
Which Remittance Channel Charges the Least — and Which Fits You? OFW Remittance Fees Guide
Use Wise if: You want the best rate, you have a bank account or debit card, and 1–2 day delivery is acceptable. Best for regular monthly remittances.
Use GCash if: Your family uses GCash daily (bills, online shopping, QR payments), you need instant delivery, and you’re sending smaller amounts.
Use Palawan Pawnshop if: Your family doesn’t have a bank account, you need cash pickup in rural areas, or you’re sending from a country with limited digital options.
Use Bank Transfer if: You’re sending a large amount ($2,000+), you need the security of a direct bank-to-bank transfer, or your employer only processes salary through bank channels.
FAQ: OFW Remittance Fees Compared 2026
Q: What is the cheapest way to send money to the Philippines from Saudi Arabia? the remittance channel charges the least when the rate markup and the mid-route deductions both stay near zero — on the $500 test that was Wise, and the ranking shifts only when your corridor changes.
A: Based on our OFW remittance fees compared 2026 research, Wise typically offers the lowest total cost for Saudi-based OFWs sending to the Philippines, thanks to the mid-market exchange rate and low transfer fees. However, if your family needs cash pickup in a rural area, Palawan Pawnshop through a local partner may be more practical despite a slightly higher cost. On big sends the spread matters more: at $1,000, the ₱1,500–₱2,000 gap between the best and worst remittance channel charges the least comparison becomes a real budget line.
Q: Is GCash safe for receiving OFW remittances?
A: Yes. For OFW remittance fees compared 2026 purposes, GCash is regulated by the Bangko Sentral ng Pilipinas (BSP) and is the largest mobile wallet in the Philippines with over 90 million users as of 2026. Funds are held in partner banks and covered by deposit insurance. The main risk is user error (sending to the wrong number) — always double-check the recipient’s GCash number. Small sends favor the flat-fee channels, but the remittance channel charges the least overall still depends on the receiver — Palawan wins where cash pickup and no bank account matter.
Q: How much are OFW remittance fees in 2026?
A: Fees vary widely by service. Wise charges $3.50–$5.00 per transfer with no exchange rate markup. GCash charges $0–$4.99 but marks up the exchange rate by 1–2 PHP. Bank transfers cost $10–$25 plus intermediary fees and the worst exchange rates. Palawan Pawnshop charges $2–$5 with moderate rate markup. The remittance channel charges the least question re-prices with every corridor change — recheck the tables each quarter, since the platforms move promo terms first.
Q: Can I send remittances to the Philippines for free?
A: Some services offer free first transfers as promotions (GCash, Remitly, and others run these regularly). However, “free” doesn’t mean zero cost — the exchange rate markup is still built in. For recurring transfers, Wise’s transparent pricing usually results in the lowest total cost even with its small fee.
Q: What is the best time to send remittances to the Philippines?
A: Exchange rates fluctuate daily based on global markets. The USD/PHP rate has ranged from 55 to 62 PHP over the past 12 months (as of June 2026). Track rates using XE.com or Google Finance. When the peso is weak (higher PHP per USD), your family gets more pesos for the same dollar amount. Some OFWs send more when the rate is favorable and hold dollars when the rate is poor.
Q: Are OFW remittances taxed in the Philippines?
A: Personal remittances from OFWs are generally not taxed in the Philippines. Under the Tax Reform for Acceleration and Inclusion (TRAIN) Law, remittances for personal use are exempt from tax. However, if you’re investing the funds (in stocks, UITF, or real estate), the investment income may be subject to tax. Consult a tax professional for your specific situation.
Disclaimer: This article is for informational purposes only and does not constitute financial advice. Exchange rates and fees change frequently. Always check the current rate and fee structure of your chosen remittance provider before sending money.
Affiliate Disclosure
Some channels referenced above — including Wise — carry affiliate arrangements with WorldNgayon; if you sign up through a tracked link, the site may earn a commission at no cost to you. The comparison itself remains independent: the figures come from each channel’s published terms on the same test transfer, and no channel paid for its ranking.
- xe.com/currencyconverter/convert?Amount=1000&From=USD&To=PHP — XE.com, June 11, 2026
- Official bsp.gov.ph/SitePages/Statistics/ExchangeRate.aspx — central bank’s reference rates
External sources linked in this article, in order of first mention. Spotted an error or a broken link? Tell us.
Cite this pagePublished June 11, 2026 · Updated Nov 4, 2026
Agron, E. (2026, June 11). Which Remittance Channel Charges the Least? The Complete 2026 Comparison. WorldNgayon. https://worldngayon.com/ofw-remittance-fees-compared-2026/
Agron, Edmon. “Which Remittance Channel Charges the Least? The Complete 2026 Comparison.” WorldNgayon, 11 June 2026, worldngayon.com/ofw-remittance-fees-compared-2026/.
Agron, Edmon. “Which Remittance Channel Charges the Least? The Complete 2026 Comparison.” WorldNgayon, June 11, 2026. https://worldngayon.com/ofw-remittance-fees-compared-2026/.
Agron, E. (2026) ‘Which Remittance Channel Charges the Least? The Complete 2026 Comparison’, WorldNgayon, 11 June. Available at: https://worldngayon.com/ofw-remittance-fees-compared-2026/.
E. Agron, “Which Remittance Channel Charges the Least? The Complete 2026 Comparison,” WorldNgayon, June 11, 2026. [Online]. Available: https://worldngayon.com/ofw-remittance-fees-compared-2026/
@online{agron2026ofwremittance,
  author       = {Agron, Edmon},
  title        = {{Which Remittance Channel Charges the Least? The Complete 2026 Comparison}},
  year         = {2026},
  date         = {2026-06-11},
  organization = {WorldNgayon},
  url          = {https://worldngayon.com/ofw-remittance-fees-compared-2026/},
  urldate      = {}
}TY - ELEC AU - Agron, Edmon TI - Which Remittance Channel Charges the Least? The Complete 2026 Comparison T2 - WorldNgayon PY - 2026 DA - 2026/06/11/ UR - https://worldngayon.com/ofw-remittance-fees-compared-2026/ Y2 - ER -
Cite the version you read; the page may be updated. Zotero and Mendeley can also import this page directly.