Table of Contents
Stablecoins explained without the hype: a stablecoin is a digital token engineered to hold a fixed value — usually one US dollar — backed by reserves rather than by belief | the big issuers (Tether’s USDT, Circle’s USDC) run combined markets measured in the hundreds of billions | payment rails (Visa, Mastercard, banks, remittance firms) now move them because settlement is minutes and cost is cents | the risks are just as real: peg breaks, reserve opacity, and regulatory rewrite (BSP’s own peso-stablecoin vision: internal link below) | read the reserve section before the yield section
Key Takeaway
- 🪙 Stablecoins explained simply: a crypto token designed to always be worth one unit of something boring — usually the US dollar — issued against reserves of cash and short-term assets, redeemable back to normal money.
- ⚙️ Three engine types exist: fiat-backed (dollars and T-bills in reserve), crypto-collateralized (over-collateralized loans on-chain), and algorithmic (code-managed supply — the type that infamously broke in 2022 and wiped tens of billions).
- 💳 The payments industry adopted them for plumbing, not speculation: Visa and Mastercard settlement pilots, bank pilots, and remittance corridors now use them because settling in a stablecoin takes minutes and costs cents — our own coverage tracked BSP’s peso-stablecoin vision aimed at remittances.
- ⚠️ The risks are structural, not theoretical: a peg is a promise, reserves vary in quality and disclosure, algorithmic designs have already failed catastrophically, and every yield farm is lending your deposit to someone you cannot see.
- ⚠️ Not advice: this is an explainer. It names mechanisms and risks; it does not tell you to buy, hold, or avoid anything.
The term gets thrown around enough that stablecoins explained is now a genuine beginner search: half the marketing promises digital dollars that never break, the other half warns of an imminent collapse, and almost nothing in between explains the actual machinery. So here is the machinery, in the order a careful reader would build it: what a stablecoin is engineered to do, the three engine types that keep pegs (each with different failure modes), who issues the big ones and how the reserves behind them are supposed to work, why the formal payments industry adopted them, and the specific risks that remain even in the best-run versions. By the end you will be able to read any stablecoin’s claims and check the two things that matter: what backs it, and who would make you whole if the peg slips — stablecoins explained in full, without the hype.
Stablecoins Explained From the Ground: What the Token Actually Is
A stablecoin is a cryptocurrency token whose supply the issuer manages against a reserve, with the goal of holding the token’s market price at a peg — most commonly one US dollar. You do not buy a stablecoin hoping it grows; you buy it to park value, move it, and pay with it, the way a bank account moves money but without a bank in the middle. Mechanically it is a two-way door: you give the issuer a dollar (or equivalent), they mint you a token; you return the token, they burn it and hand the dollar back. The design goal is that the market never has a reason to price the token away from the dollar, because anyone holding it can always exchange it for the reserve asset — the peg is an arbitrage loop, not a slogan.
Why the world wants this in crypto form: normal money moves at banking speed — banking hours, correspondent chains, cut-off windows and correspondent fees; a stablecoin is a token on a public ledger that settles in minutes, around the clock, at close-to-zero marginal cost, and can sit in a self-custody wallet instead of an account that a single institution controls. That combination — dollar-like stability with internet-speed settlement — is the entire product. That is stablecoins explained at the machine level — the rest of the discussion, the issuer brands, the reserve debates, the regulation, is about how reliably each version of the machine keeps that promise.
Stablecoins Explained by Engine Type: Three Ways to Keep a Peg
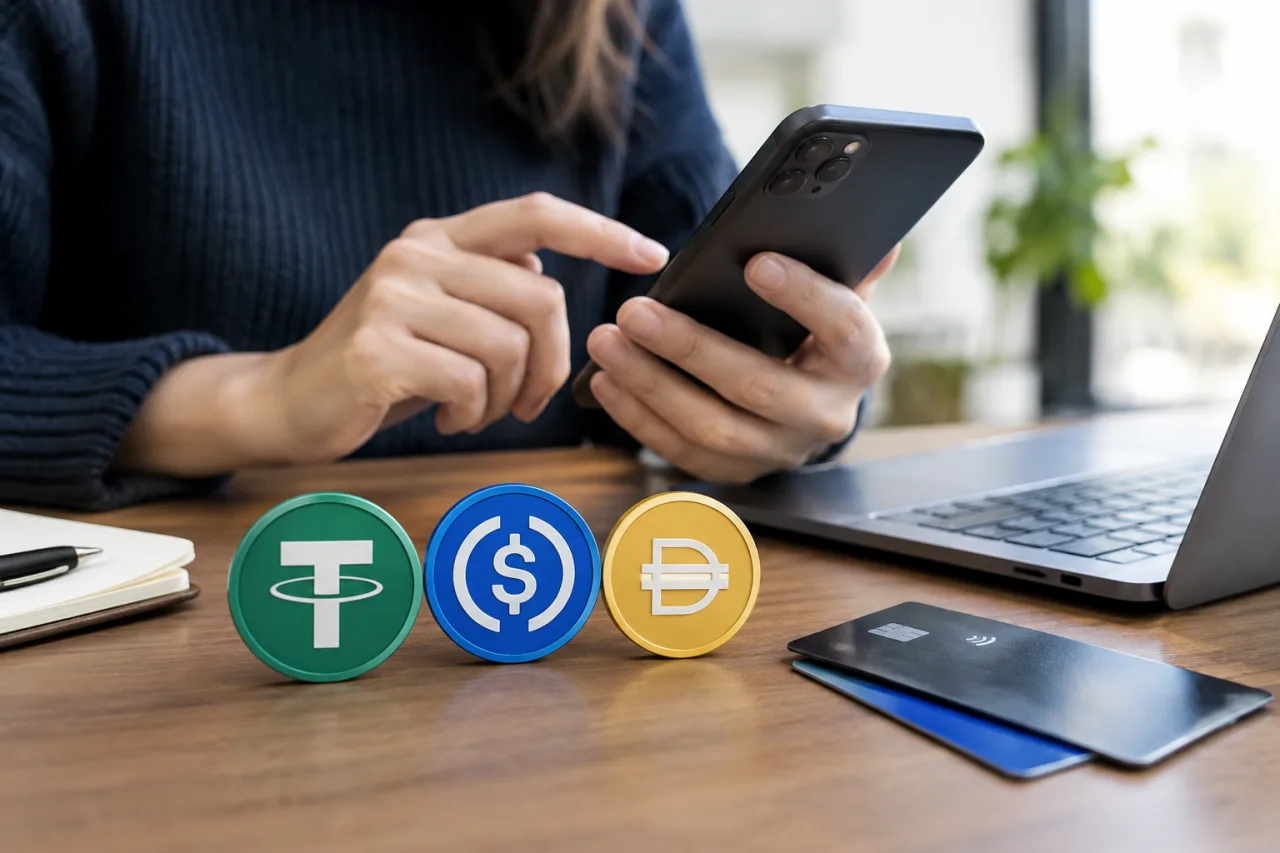
- 1. Fiat-backed — the dominant design. The issuer holds cash, short-term government bills, or reserve repurchase agreements equal to the tokens outstanding, promises redemption at par, and publishes attestations of the reserves. Tether (USDT) and Circle (USDC) are the biggest examples; Circle discloses its reserve composition and regulatory posture publicly. Failure mode: reserve quality and redemption discipline — if the market doubts the reserves or the issuer’s willingness to honor redemptions, the token can trade below its peg even if no asset is actually missing.
- 2. Crypto-collateralized. Instead of dollars, the pool holds other crypto assets — locked in smart contracts — usually at a large over-collateralization margin, precisely because the collateral itself is volatile. MakerDAO’s DAI is the canonical, longest-running example. Failure mode: a fast crash in collateral value can cascade through the liquidation machinery faster than it can refill the buffer.
- 3. Algorithmic. No full reserve is held at all; pegs are defended by code — typically a second token whose supply expands and contracts to absorb pressure. The 2022 TerraUSD (UST) collapse is the case study held up in every serious explainer: the mechanism worked in calm markets and annihilated tens of billions of dollars of value in a week of stress, dragging a companion token (LUNA) into a death spiral. Every version of “stable, without reserves” deserves the same verdict: the design has already been stress-tested by reality, and reality was brutal.
One design detail separates the professional versions from everything else: redemption is the peg. Prices can wobble on exchanges for minutes at a time; what matters is whether the issuer will still hand you a dollar at par when you ask. A stablecoin with credible redemption holds its peg through ordinary turbulence; a coin whose redemption door is closed, slow, or conditional owns nothing but branding.
Who Issues What — and How the Reserves Are Supposed to Work
The market’s center of gravity is two issuers. Tether (USDT) is the oldest and largest stablecoin by circulation, and the most scrutinized: its reserves historically include a mix of cash, government bills and other assets, and disclosure has been a running public controversy in the sector. Circle (USDC) is the transparency-forward version — reserves in cash and short-dated US Treasuries, with regular attestations and a regulatory posture aimed squarely at becoming the institutional settlement dollar. Between them, the two tokens float the majority of stablecoin transaction volume, and issuers of this class earn their keep largely on the interest those reserves yield — a business model worth noting, because it explains why stablecoins exist even where trading activity is thin: the float is the profit.
The reserve question is where stablecoins explained by issuers diverges from stablecoins explained by auditors. The correct beginner habit: before trusting any stablecoin, find three published things — what the reserves consist of, how often they are attested and by whom, and what the redemption process actually involves (timing, minimums, who can redeem — everyone or only partner institutions). A coin that answers all three in writing is in a different risk class from one that answers none.
Why Visa, Mastercard and the Banks Came to the Party
The payments establishment did not adopt stablecoins as a bet on crypto prices; it adopted them as settlement plumbing. In 2026 the adoption wave is fully visible: Visa and Mastercard both switched on stablecoin settlement and card rails, Stripe’s Tempo chain was built with the big networks alongside it, money-giant remittance pilots moved from slides to production, and Samsung Wallet added USDC transfer features to its wallet stack — each tracked in our own coverage of the payments shift. The consistent reason: settlement time and cost. A cross-border payment that takes two banking days and several intermediary hops can settle same-day in a stablecoin at a fraction of the cost, with the reserve asset giving both sides a stable unit to invoice in. Central banks took the same lesson: the BSP’s own peso-stablecoin vision is explicitly aimed at cutting the OFW remittance bill — the same two-way-door machinery, issued in pesos, with regulatory custody.
For a household, the practical meaning is narrower and clearer: stablecoins are the dollar-like asset that already inside the apps some families will encounter — a remittance corridor that quotes in stablecoin, a savings product that pays its yield “in USD” — and the questions to ask become the questions from the reserve section, not the price chart.
The Risks, Ranked by How Often They Actually Happen
- 1. Peg wobble and depeg. Every major fiat-backed coin has traded a few percent off peg during panic windows; algorithmic coins have lost everything. Check the coin’s worst-day print in its history before trusting it in a payment.
- 2. Reserve opacity. The reserve is the trust anchor, and its composition changes: bills versus banks versus affiliated entities make the difference between a bank-like product and a marketing claim. Issuers that publish more get audited more — that correlation is the beginner’s compass.
- 3. Redemption friction. Stablecoins explained honestly put this first: The peg survives only if redemption is honored: minimums, geographic restrictions, bank-account requirements, or “partner-first” redemption access can all turn theory into a queue at exactly the wrong moment.
- 4. Regulatory rewrite. The rules of the game are being written now — jurisdictions from Hong Kong’s licensing regime to France’s tax regime to the BSP’s own project show the map is still being drawn. Issuer-level compliance risk lands on holders.
- 5. The yield trap. High “stablecoin yields” do not come from the coin — they come from lending your deposit to someone (borrowers, exchanges, counterparties) who may not pay it back. The coin can be fine while the yield program burns. Five risks, in order of historical frequency — stablecoins explained by failure mode, in one list.
A Practical Reading Guide Before You Touch One
For the reader who now meets a stablecoin inside an app — a remittance quote, a savings dash, a payroll pilot — the desk’s five-minute check runs in this order: (1) which issuer, and is the issuance structure named; (2) what backs it, per published attestations — cash-and-bills is the gold standard, vague “assets” is the warning sign; (3) is redemption described concretely, including timing and who qualifies; (4) does the coin have a history of holding its peg on the worst days, not the best ones; (5) if a yield is being offered, who is paying it and from what lending activity. Five answers worth having beats any amount of hype — in either direction. Deeper dives continue on the desk’s own rails: our three-test guide to stablecoin payments, the Visa-Mastercard adoption wave, and the fee-free remittance era via Samsung Wallet each cover a corner of the machine this piece opened — with stablecoins explained fully only once reserves and redemption are both on the page in writing.
FAQ
What is a stablecoin in simple terms?
A digital token built to always be worth one unit of a stable reference asset — usually one US dollar — backed by reserves the issuer holds, and exchangeable back to normal money. You use it to park, move and pay with digital dollars, not to speculate on price.
How are stablecoins explained to beginners — backed, collateralized, or algorithmic?
Those are the three engine types. Fiat-backed coins (USDT, USDC) hold dollar reserves; crypto-collateralized coins (DAI) lock other crypto at over-collateralized ratios; algorithmic coins manage supply with code. Fiat-backed dominates the market, and algorithmic designs carry the worst recorded failure history (TerraUSD’s 2022 collapse).
Are stablecoins safe?
They carry a different risk set from ordinary savings: reserve opacity, redemption friction, peg wobble in panic windows, and issuer regulatory risk. The strongest versions publish reserve attestations and honor redemptions at par under stress; the weakest have already failed completely. Stablecoins explained honestly answer issue-by-issue — safety is issuer-specific, not category-wide — check reserves, attestation frequency and redemption terms before trusting any coin.
What happened to TerraUSD (UST)?
In May 2022, the algorithmic stablecoin TerraUSD broke its peg and collapsed in days, wiping out tens of billions of dollars alongside its companion token LUNA. It remains the reference case for why “stable without reserves” designs are treated as structurally fragile by the desk and by virtually every regulator since.
Why do companies like Visa and Mastercard use stablecoins?
For settlement plumbing: stablecoins settle in minutes, around the clock, at near-zero marginal cost — versus banking rails that take days and multiple intermediary fees. With reserves in dollar-equivalent assets, both sides of a payment can invoice in a stable unit. The same logic is why remittance firms and even central banks (BSP’s peso-stablecoin project) test the rails.
Can a stablecoin lose its dollar peg?
Yes — every major stablecoin has wobbled at least temporarily during market panics, and algorithmic ones have failed outright. The peg is an arbitrage promise backed by redemption; it holds only as long as the issuer’s reserves and redemption door do. Check a coin’s worst-day history, not its best-day marketing.
Financial Disclaimer: This article is an educational explainer for general information only — it is not investment advice, a recommendation, or an offer to buy, sell or hold any token or product named. Digital assets carry significant risk, including total loss; stablecoin mechanisms, reserve compositions and regulatory treatments change without notice and vary by jurisdiction. Figures and issuer details are cited from sources on record (October 2026) and should be verified on the issuer’s own publications before any decision. Consult a licensed financial adviser before acting on any of this content. worldngayon.com holds no position in any asset named and is not liable for outcomes from actions taken on this content.
Sources: the market’s principal issuers’ published materials (Circle’s USDC disclosures; Tether’s reserve reports and attestations); MakerDAO’s DAI mechanism documentation; the TerraUSD/May 2022 collapse as recorded in Wikipedia’s stablecoin entry and contemporary coverage; the desk’s own filings-based pieces on Visa-Mastercard adoption, the BSP peso-stablecoin project, Samsung Wallet USDC rails and the stablecoin-payments test framework.