Editor’s Note — November 4, 2026: This article has been updated to clarify PSEi market figures, Philippine brokerage commission rules, and the limitations of several investment-screening indicators. We also revised the examples and improved the article’s explanations.
Table of Contents
PSEi Bargain Hunting: How Smart Investors Work a Philippine Stock Correction
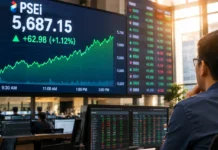
Recent PSEi performance (November 2026): the PSEi closed October in the red — the Oct 30 session, which closed at 5,680.35 per exchange-linked records — after the global tech-selloff wave and the peso easing; mid-month, a bargain-hunting session lifted the index to 5,663 (the Inquirer’s documented rebound), and the latest session carried financial-feed values near 5,687.15 (+1.12% over the official Nov 3 close of 5,624.17) — provisional at writing, pending the exchange’s own report (the PSE’s official Nov 3 close: 5,624.17, −0.99%) | bargain hunting in a Philippine stock correction, the full mechanics + the checklist a serious investor runs before buying — inside
Key Takeaway
- 🧾 Bargain hunting is a process, not a verb: in the PSEi’s corrections, psei bargain hunting’s core promise: the investors who actually win (the record: the documented mid-month rebound session where ‘investors snapped up bargains’ after consecutive down-days) are the ones who arrive with a written checklist — valuation lines, liquidity floors, balance-sheet screens, position sizing — not a mood; this piece is that checklist, applied to the live Philippine correction file review.
- 📉 Cheap is a price, cheapness is a reason: the correction’s fallen names split into three classes — cyclical pressure on solid balance sheets (the genuine bargains), structural breaks (the permanently-cheap), and momentum casualties (neither); the PSEi bargain hunt’s real work is sorting which is which before the buy — the screens below do exactly that.
- 💰 Liquidity is the Philippine correction’s special hazard: a PSE bargain that can’t be sold (thin board lots, wide spreads, a name trading at very low value) is a stock that looks inexpensive but carries real risks — the liquidity ladder (board lots, average daily value, the spread check) runs before any valuation screen in this playbook.
- 🏦 The funding rule protects the family: PSE bargain money comes from the invested slice only — remittance-funded accounts follow the corridor-first sequence (priced rails → funded account → sized exposure), and the emergency floor never converts into ‘one more bargain’; the discipline outsells the deal every time.
- ⚖️ The foreign-flow answer changes the play: the same rebound records show institutions alternating between distributions and bargain-class buying — a dip with institutions selling into it is weaker than a dip with flows turning; the PSE’s official market reports are the accountability source, and every bargain decision reads them first.
PSEi bargain hunting has become the hottest phrase in a market that just lived through a red month: the index ended October in the red (the Oct 30 close at 5,680.35 on the exchange-linked record), the month carried the global tech-selloff wave and the peso easing, and the tapes already showed the behavior the phrase describes — the documented mid-month session where investors snapped up bargains after consecutive down-days and the November-4 bounce that printed 5,687.15 (+1.12%). But the phrase hides the difference between hunting and hoping: bargain hunting, done the way the PSEi’s survivors do it, is a screening process — a liquidity check before any valuation line, a balance-sheet pass before any price line, a foreign-flow read before any decision, and a position-size discipline that assumes the dip gets deeper before it ends. This piece builds the full Philippine-stock-correction checklist from the live file review: the bargain-hunting mechanics that actually transfer from record to portfolio, screen by screen, with the notes about what each screen cannot tell you.
Recent PSEi Sessions and What They Illustrate
The November market hands this playbook a complete teaching file in three sessions: the Oct 30 close (5,680.35, lower on the exchange-linked record — the October 30 decline, where the global tech wave and the peso easing did the selling); the mid-month rebound (the Oct 15 session, where the Inquirer’s record shows the PSEi recovering to 5,663 because ‘investors snapped up bargains after two straight sessions of losses’ — the documented bargain-hunting print); and the Nov 4 bounce (5,687.15, +1.12% per financial feeds — provisional at writing, pending the exchange-side confirmation). Same index, three different behavioral moments — and the bargain-hunting skill is knowing which moment the market is in: the October 30 decline belongs to watchlist drafting (names whose screens pass but prices haven’t broken), the rebound session belongs to running the checklist (the five screens below), and the recovery phase belongs to the follow-through question (is the flow turn real?). Investors who skip step-ordering buy at the wrong moment in the right name — the file review’s lesson.
The deeper note the file review carries: the three sessions also document who was buying — the rebound record’s own reporting credits the recovery to bargain-seeking buyers reacting to price, not to any news catalyst; that is the pattern the method trains you to expect and to check against the exchange’s flow reports. A rally with no catalyst is price-driven; price-driven rallies are exactly where a checklist earns its keep — because the checklist’s psei bargain hunting balance-sheet pass (Step 2) works identically whether the ticker is green or red, and that is the whole advantage the disciplined keep. The file also settles the temperament question: the two most dangerous sessions for a checklist runner are the panic print and the euphoria print — the first because survival screens get skipped in the rush to ‘get out’, the second because valuation screens get skipped in the rush to ‘get in’. The file review’s three days show both temptations within a single month; the runner who keeps the sequence (liquidity, sheet, valuation, flows, sizing) regardless of weather is the runner the method actually protects. PSEi bargain hunting, in the end, is analysis plus temperament: a spreadsheet for the screens, discipline for the decisions.
Step 1 — the Liquidity Ladder (the Philippine Correction’s First Screen)
- Board-lot reality: PSE trading runs in board lots (the trading-day piece carries the machinery: pre-open, matching windows, the T+2 settlement on record) — a low-priced name trades in more shares per lot and a high-priced one in fewer; the bargain hunter’s first job: know the lot size your entry price buys into, because liquidity is priced into the structure, not the quote.
- Average daily value screen: the name must trade enough pesos a day to absorb your exit — the practical floor: your full position ≈ a small fraction of one day’s traded value; anything thinner converts a ‘bargain’ into an illiquid commitment the market can reprice against you at exit.
- The spread check: the best bid to the best offer is the exit tax — wide spreads in a correction widen further on red days exactly when you need out; the liquidity test’s rule: if the spread alone eats your expected rebound, the bargain is not a bargain.
Step 2 — the Balance-Sheet Pass: Which Fallen Names Can Survive the Winter
- The survival screen: corrections end; balance-sheet mistakes don’t — the pass: cash and receivables against the debt wall, the interest bill against operating cash, and the covenant tripwires that force equity raises (a correction-quarter rights issue is how a ‘bargain’ dilutes its own buyers).
- The three classes the pass sorts into: (1) cyclical pressure on solid sheets — the genuine PSE bargain class where the earnings dip is the market’s fault; (2) structural breaks — secular decline dressed as a discount, the permanently-cheap trap; (3) momentum casualties — the crowded-favorite unwind where price discovery hasn’t finished; each demands a different response, and only the first deserves the bargain bid.
- The Philippine-specific hazard: family-controlled and conglomerate-linked names carry related-party transactions and obligations that a simple screen misses — the careful investor reads the disclosures (the exchange’s filings layer) for guarantees, deposits with affiliates and the related-party loans that turn a solid sheet into a soft one.
Step 3 — Valuation Without the Trap Words
- P/E against its own history: a fallen name’s multiple means nothing against a market ‘average’ and everything against its own five-year corridor — the valuation line: where does this name’s P/E/EV-EBITDA sit inside its own range, and what earnings scenario holds that multiple defensible?
- The dividend floor: for the PSE’s income names, the cash dividend through a red month is the valuation’s strongest test — a maintained, funded dividend while the price falls may signal a genuine bargain; a dividend cut announced mid-correction can signal a structural break (the two often differ by one disclosure).
- The trap phrases: ‘it used to be 8,000’ (price anchors are not evidence), ‘it can’t go lower’ (it can), and ‘the market is wrong’ (maybe — for longer than you can hold); the valuation screen’s discipline runs on ranges and scenarios, never on anchors.
Step 4 — the PSEi Bargain Hunting Flow Read: Institutions First, Retail Second
- Read the foreign-flow report before the buy: the PSE’s official market reports separate the money classes; the pattern the corrections show — foreign selling pressing the index through the global waves (the October record), bargain-class and domestic flows into the repair days (the documented rebound sessions) — is official trading and flow data a checklist runs first.
- The two-week confirmation rule: one session can show pressure releasing; two weeks of consistent breadth and flows prove behavior changed — the bounce day is information, the follow-through is the evidence; the series’ framework exists precisely so a green day doesn’t get mistaken for a turn.
Step 5 — Position Sizing: the Assumption the Checklist Ends On
- Tranche, don’t declare victory: the a staged entry runs in tranches with written add-down lines — the correction’s habit is deeper lows after the first bargain bid (the month’s own record: bounce sessions inside falling weeks); the sizing assumes error, which is why survivors outlast heroes.
- The total-exposure ceiling: the invested slice caps at the amount the household can hold through a worse month (the emergency-floor mathematics stay untouched); the ceiling is written before the bargain appears — the discipline that keeps a market session from becoming a budget casualty.
- The cost line: commissions are not fixed by regulation — SEC Memorandum Circular No. 7 (2024) removed the prescribed minimum, so the Securities and Exchange Commission confirms no universal rate exists (the removal, reported April 2024; PSE circular CN-2024-0029) — 0.25% describes a common broker schedule, not a rule. A straight-percentage broker costs the same total whether you split or not; per-order minimums plus VAT and exchange/clearing fees are what can make many small orders cost more than one large order — hence fewer, pre-written tranches.
FAQ
What is PSEi bargain hunting?
The documented behavior of investors buying quality names at correction-depressed prices after consecutive down sessions — the mid-month rebound print captured it directly (‘investors snapped up bargains’); done properly it is a screening process (liquidity, balance sheet, valuation, flows, sizing) — not a reflex buy at every red candle — the psei bargain hunting screens earn the right to buy.
Is it good to buy the dip in the Philippine stock market?
The balanced frame: only with the checklist run and only from the invested slice — the PSEi’s red October (the 5,680.35-linked record) shows dips can deepen; the tranches-plus-ceiling discipline exists because the dip’s bottom is only certain in hindsight.
How do I find bargains for psei bargain hunting as a beginner?
The five-screen ladder: liquidity (daily traded value vs your position), balance-sheet survival (cash vs debt walls), valuation inside the name’s own history, the institutional-flow read from the exchange’s official reports, and written position sizing — the sequence matters: liquidity first, price last.
Why is liquidity so important in psei bargain hunting?
Because a thin name reprices against its own sellers: wide spreads and small daily volumes turn an intended quick rebound-trade into an unpriced exit — the liquidity ladder (board lots, average daily value, the spread check) is the Philippine market’s special hazard screen, run before any valuation line.
What is the biggest mistake in bargain hunting?
Anchoring on the old price: ‘it used to be 8,000’ is the trap phrase the screens refuse — bargains are priced by survival screen + valuation range + flow evidence; the name’s past quote is history’s opinion, not the market’s present one.
Can OFWs join PSEi bargain hunting while abroad?
Yes — the rails are built for it: the broker layer opens remotely (the comparison pieces carry the documented commissions), the remittance corridor funds the account (the corridor-first pricing sequence), and the time zone favors evening order-entry after the session — the same five screens apply, executed on schedule rather than on impulse.
Financial Disclaimer: This article is an educational investing-framework guide for general information only — it is not investment advice; no stock, screening result or decision mentioned here is a recommendation. Market conditions, filings and rules change; figures are cited from sources on record (November 2026) and must be verified on the exchange’s official reports and the issuers’ filings before any decision. worldngayon.com is not affiliated with the PSE, any broker or issuer named and is not liable for outcomes from actions taken on this content.
Carriers on record: the Inquirer’s mid-month bargain-hunting rebound report (the documented behavior, dated Oct 15) and the TradingEconomics live PSEi record (the November-4 close); the desk’s own layers: the the November-4 print episode, the the correction 2026 guide, the the trading-day machinery, the the beginners’ playbook, the the PSE IPO walk, and the the remittance data guide.
A worked screening example (hypothetical, illustrative figures only)
Suppose a Philippine-listed retailer falls 30% in a market correction and a reader wants to assess it. Liquidity: the names trade in ₱1,000 board lots and the reader’s intended ₱80,000 position is spread across a month — if recent daily value turnover runs in the tens of millions, entry at one-tenth per week is realistic; on a stock that trades single-digit millions, the same plan may move the price against you. Balance sheet: debt-to-equity and interest coverage from the latest PSE Edge annual filing decide whether a red quarter is survivable — an illustrative screen: total debt within two times equity, interest covered five times by operating cash flow. Valuation: the trailing P/E of 9 against a five-year band of 12-18 only means something if forward earnings hold; the correction may have cut both price and earnings prospects. Flows: two weeks of net foreign buying may indicate renewed participation — it does not confirm a bottom. Sizing: ₱20,000 tranches with a written ₱80,000 ceiling, entered only at pre-set prices, keep one bad name from becoming one bad portfolio. The one-line discipline: a price decline is a fact; undervaluation is a conclusion the reader must support from the filing, not from the red candle.
- Official sec.gov.ph — the Securities and Exchange Commission
- mb.com.ph/2024/4/17/sec-removes-minimum-stockbrokers-commission — the removal, reported April 2024
- documents.pse.com.ph/CircularOPPDF/CN-2024-0029.pdf — PSE circular CN-2024-0029
- business.inquirer.net/616083/psei-rebounds-to-5663-on-bargain-hunting — Inquirer’s mid-month bargain-hunting rebound report
- tradingeconomics.com/philippines/stock-market — TradingEconomics live PSEi record
External sources linked in this article, in order of first mention. Spotted an error or a broken link? Tell us.
Cite this pagePublished Nov 4, 2026
Agron, E. (2026, November 4). PSEi Bargain Hunting: How Smart Investors Work a Philippine Stock Correction. WorldNgayon. https://worldngayon.com/psei-bargain-hunting/
Agron, Edmon. “PSEi Bargain Hunting: How Smart Investors Work a Philippine Stock Correction.” WorldNgayon, 4 Nov. 2026, worldngayon.com/psei-bargain-hunting/.
Agron, Edmon. “PSEi Bargain Hunting: How Smart Investors Work a Philippine Stock Correction.” WorldNgayon, November 4, 2026. https://worldngayon.com/psei-bargain-hunting/.
Agron, E. (2026) ‘PSEi Bargain Hunting: How Smart Investors Work a Philippine Stock Correction’, WorldNgayon, 4 November. Available at: https://worldngayon.com/psei-bargain-hunting/.
E. Agron, “PSEi Bargain Hunting: How Smart Investors Work a Philippine Stock Correction,” WorldNgayon, Nov. 4, 2026. [Online]. Available: https://worldngayon.com/psei-bargain-hunting/
@online{agron2026pseibargain,
  author       = {Agron, Edmon},
  title        = {{PSEi Bargain Hunting: How Smart Investors Work a Philippine Stock Correction}},
  year         = {2026},
  date         = {2026-11-04},
  organization = {WorldNgayon},
  url          = {https://worldngayon.com/psei-bargain-hunting/},
  urldate      = {}
}TY - ELEC AU - Agron, Edmon TI - PSEi Bargain Hunting: How Smart Investors Work a Philippine Stock Correction T2 - WorldNgayon PY - 2026 DA - 2026/11/04/ UR - https://worldngayon.com/psei-bargain-hunting/ Y2 - ER -
Cite the version you read; the page may be updated. Zotero and Mendeley can also import this page directly.