Table of Contents
Key Takeaway
- 🛡️ Protect elderly parents from scams with one working agreement: any request for money, gift cards or account numbers gets stopped and verified through a second channel before anything moves, a rule that beats tech-support callers and fake-grandson voices alike.
- 🗣️ Start with the script, not the lecture: scammers script shame on purpose, so the conversation works when it promises no blame for falling for one.
- 🔐 Build the protection together: view-only bank access, a trusted contact person on file, and call-screening settings protect the money without touching anyone’s password.
- 🚩 Gift cards and wire requests are the fire alarm: gift-card scams and wire transfers move the money outside normal dispute windows, which is why both get their own family rule.
- ⏱️ If money already went out, the first 48 hours decide what a bank can still pull back: call the bank, freeze what you can, and file the report the same day.
If this is the year to protect elderly parents from scams, the number that matters is the year before the call, when the defenses get built. The FBI’s internet crime center logged $4.885 billion in reported losses from Americans over 60 in 2024, across 147,127 complaints, a 43 percent jump in losses and a 46 percent jump in complaints in a single year. Seven thousand five hundred complainants lost more than $100,000 each, and the average loss crossed $83,000. The FTC’s own tracking shows reported losses among older adults climbing from roughly $600 million in 2020 toward $3 billion in 2025, and it says plainly that the true cost is higher because most fraud never gets reported.
Protect Elderly Parents From Scams Before the Phone Rings
Protection that works starts before any scammer dials, for two reasons. First, the defenses that survive are the ones built into accounts and phones, not the ones that depend on remembering advice mid-call. Second, the most reported schemes against older adults are not exotic: tech-support and government-impersonation calls, investment pitches, romance builds and family emergencies, the same families the FTC’s Pass It On catalog covers in thirteen plain-language sheets.
The scale matters for planning, not panic. Investment scams alone accounted for about $1.8 billion of the FBI’s older-adult losses in 2024, with tech-support scams near $1 billion. Those are operations with call centers, scripts and patient follow-ups, not a lucky cold caller. A family that has agreed on the rules below is not avoiding every attempt; it is removing the two things the attempts need: instant payment and silence afterward.
The Conversation That Stops the Shame Spiral
Most families wait until after money is gone, which is the wrong order. The quiet week to protect elderly parents from scams is any week when the phone is not ringing. Scammers script shame deliberately: they isolate, flatter, hurry and warn the caller not to tell anyone, because the lie dies the moment a second person hears it. The FTC’s materials for older adults carry the same three verbs for a reason: stop, talk to a person you trust, confirm what actually happened. Your conversation with a parent installs those verbs in advance, so they exist before the phone rings.
Keep the no-blame rule explicit. Say you have read that people your age and mine get these calls every day, that the callers are professionals with research and scripts, and that anyone can be taken in, including the family member doing the talking. Describe one of your own near-misses if you have one; it does more than any statistic. The FTC’s 2026 older-adults report adds an insight that changes the outreach plan: older adults report money losses at lower rates than younger adults and file no-loss reports at higher rates, while six-figure single losses drove the aggregate rise, and people over 80 reported a median loss near $2,000. The quiet takeaway for a family: expect the small, patient scam call as much as the dramatic one. Then agree on the working rule: any request for money, gift cards, codes or account numbers, no matter who supposedly sent it, waits while both of you verify through a different channel. Frame it as teamwork, not supervision.
The code word that beats a cloned voice
Voice cloning ended the era when a familiar voice could be proof of anything. A short personal code word, agreed in person and never discussed by phone or text, survives every fake. When an urgent call claims to be a grandchild, an attorney or a hospital, the code word is the only password that counts, and the alternative check is a call to the person’s known number. Our AI voice cloning scam guide covers the clone mechanics and the family code word in detail, and it pairs well with the wrong-number entry route that starts so many of these operations.
Make the screen do the filtering
Phone-level settings carry real weight: enable scam-call and spam filtering on your parent’s phone, turn on unknown-caller screening where the phone offers it, and register the number with the federal do-not-call list so the volume drops to the persistent actors. Landline-heavy households can ask the carrier for call-blocking or screening options. None of it blocks a determined caller; all of it slows the volume that wears a person down.
The Setup That Guards the Money Without Taking It Over
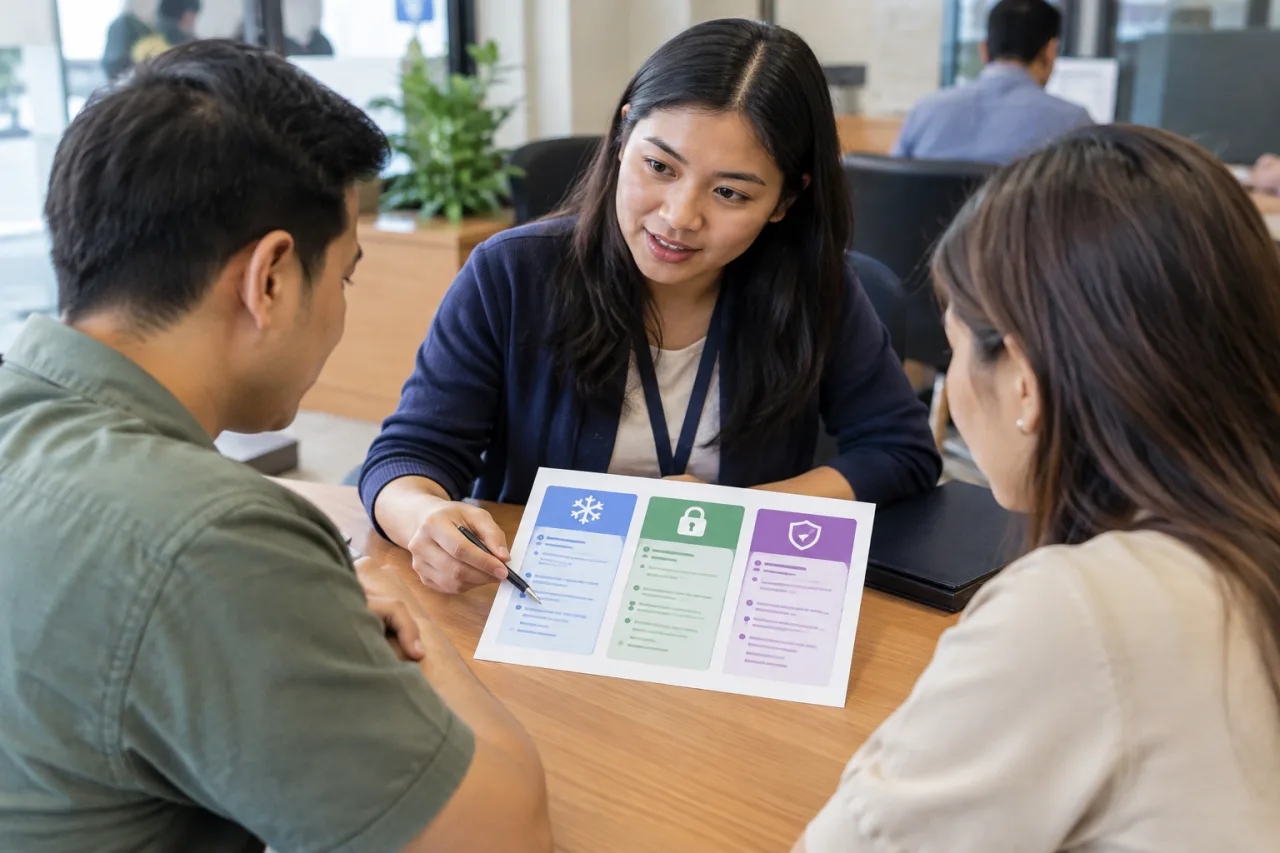
This is the layer most families skip when they set out to protect elderly parents from scams, and it is the difference between worrying and having a working defense. Banks and brokerages offer tools precisely for this situation, and none of them require the parent to surrender control.
View-only access. This is also where you protect elderly parents from scams at the account level without touching a password: many banks let a family member receive read-only visibility into balances and transactions. You see the outflow; you cannot move it. The point is detection speed, not gatekeeping: a $15,000 wire or a stack of gift-card purchases shows up the same day, when recall is possible, instead of at statement time.
The trusted contact person. Brokerage accounts are required to ask customers for a trusted contact they can reach when something looks off, and several banks offer the same flag. Give your own name and number for your parent’s accounts with their agreement, so an unusual withdrawal request gets one more call before it completes.
Alerts on both phones. One of the simplest ways to protect elderly parents from scams is speed of awareness, Turn on transaction notifications for their accounts and yours. Alerts are the cheapest tripwire in this whole defense, and they arrive in minutes.
The documents conversation, on the record. At some point the family needs clarity on who can act if a parent cannot: a financial power of attorney drawn with an attorney, plus the bank’s own durable authorization forms where they exist. Raising it during a calm week, framed as ordinary planning every family does, keeps the conversation free of suspicion; the document conversation belongs to a lawyer, and this guide stops at naming it.
The Scams Most Likely to Reach Them
The routes that reach a parent are the same routes you can break in advance, which is how a family keeps working to protect elderly parents from scams without hovering. The FBI’s older-adult complaint data for 2024 ranks the money: investment pitches on top, tech-support and customer-support schemes next, then romance and confidence builds, personal data breaches and government impersonation. The FTC adds the urgency riders most older adults meet by phone: impersonation of agencies and bank-security calls, and the grandchild emergency that a code word ends in seconds.
Two payment routes deserve their own family rule because they erase the normal safety nets. Prepaid gift cards are the first: no card number entered under pressure can be clawed back, and our gift card scam guide walks both the scripts and the freeze-the-first-hour response. Bank wires and peer-to-peer apps are the second: speed is the product, and the recall window is measured in hours. The working rule covers both: no gift-card codes, no wire details, no app transfers to anyone whose identity was not verified through the second channel that day.
Remind parents of the caller-side tells that repeat across every family of scam: pressure to stay on the phone while money moves, instructions to lie to the bank if asked, demands for secrecy, and any claim that a government agency wants payment by phone, card, gift card, wire or cryptocurrency. Real agencies correspond in writing and never collect money that way.
If Money Is Already Gone: the First 48 Hours
Work the sequence, not the panic. Call the bank or card issuer first and report fraud, asking for a recall attempt on any wire and a fraud claim on any card charge; wire recalls succeed when the receiving bank still holds the money, which makes hours matter. Freeze the card involved, and change anything the caller might have harvested, from email passwords to remote-access software the technician talked them into installing.
The same paperwork protects elderly parents from scams that repeat, because the operations rotate targets through the same lists. Paper the record the same day: report to the FTC at reportfraud.ftc.gov, keep the confirmation, and file a police report that carries the transaction details. Our global reporting routing guide lists the other channels by country, including the FBI intake most wire cases use. If the caller posed as a government official, the FTC and FBI both want the impersonation noted, because those cases feed enforcement actions. When the parent resists reporting out of embarrassment, bring the federal numbers back: 147,000 older adults filed in 2024, which makes reporting the normal move, not the shameful one.
Where the loss involves a caregiver, a family member or anyone the parent trusted with authority, the goal now includes protecting elderly parents from scams on the second attempt,’s money, state adult protective services is the added door, and banks often have internal elder-fraud units that coordinate with them. Money routed through cryptocurrency raises the difficulty further, and a realistic family conversation beats a promise the banks cannot keep.
Help Without Taking Over
The line between guarding and controlling is real, and your parent will feel it. Every tool in the setup above protects elderly parents from scams at exactly that line: view-only access sees without moving, alerts inform without restricting, the code word protects without policing. What hands over actual control, the power of attorney and formal authorizations, is a separate legal decision for a separate calm day, made with the parent’s consent and a lawyer’s help, precisely because those instruments remove options rather than add witnesses.
Keep the shared rule alive between calls: one short message a week, one recent example traded, one near-miss laughed off together. The families that lose least are the ones where the scammer cannot isolate the caller, and isolation is what this whole architecture quietly prevents.
FAQ
How can I protect elderly parents from scams without controlling them?
Build the defenses into accounts and phones rather than their decisions: view-only bank access, a trusted contact person on file, transaction alerts, call screening and the family code word. You gain detection speed and second-channel verification without holding anyone’s passwords or a power of attorney.
What is the most common scam targeting older adults?
Families who protect elderly parents from scams should know both rankings. By complaint volume, tech-support and impersonation calls lead the reports; by dollar loss, investment pitches dominate, with about $1.8 billion in reported 2024 losses from older adults per the FBI. Romance builds, government impersonation and fake family emergencies fill out the list.
Should my parents use a code word, and what kind works?
Yes, if everyone agrees it in person and never sends it by phone or text. Pick a two-word phrase tied to something only your family knows, and make it the only acceptable proof when any caller claims to be family, a lawyer or a hospital. Any failure to produce it means hang up and call the person back on their known number.
What is a trusted contact person on a bank account?
For families working to protect elderly parents from scams, it is a person, usually a family member, whom the bank or brokerage may call when something unusual happens on the account, like an out-of-pattern withdrawal. Brokerages are required to ask for one, many banks offer the same flag, and the contact cannot touch the money; the role is a second pair of eyes.
My parent already sent money to a scammer. What now?
Call the bank or card issuer immediately and request a fraud recall or dispute, freeze the affected cards, then file with the FTC at reportfraud.ftc.gov and with local police the same day, keeping every confirmation and transaction detail. If the money went by gift card or crypto, tell the bank anyway: the paper record still matters for follow-up, and the same sequence helps protect elderly parents from scams the second time and for the parent’s own recovery process.
How do I bring this up without sounding like I think they are helpless?
Trade stories rather than warnings: describe a near-miss of your own, mention the federal loss numbers so the topic feels like news, and agree on the money rule as something the whole family follows, including you. The FTC’s Pass It On materials exist for exactly this kind of conversation and give you something concrete to hand over.
- Official ic3.gov — internet crime center
- Official ftc.gov/system/files/ftc_gov/pdf/2026-older-adults-report-10192026.pdf — own tracking
- Official ftc.gov/passiton — FTC’s Pass It On
External sources linked in this article, in order of first mention. Spotted an error or a broken link? Tell us.
Cite this pagePublished Nov 21, 2026
Agron, E. (2026, November 21). How to Protect Elderly Parents From Scams (Without Taking Over Their Money). WorldNgayon. https://worldngayon.com/protect-elderly-parents-from-scams/
Agron, Edmon. “How to Protect Elderly Parents From Scams (Without Taking Over Their Money).” WorldNgayon, 21 Nov. 2026, worldngayon.com/protect-elderly-parents-from-scams/.
Agron, Edmon. “How to Protect Elderly Parents From Scams (Without Taking Over Their Money).” WorldNgayon, November 21, 2026. https://worldngayon.com/protect-elderly-parents-from-scams/.
Agron, E. (2026) ‘How to Protect Elderly Parents From Scams (Without Taking Over Their Money)’, WorldNgayon, 21 November. Available at: https://worldngayon.com/protect-elderly-parents-from-scams/.
E. Agron, “How to Protect Elderly Parents From Scams (Without Taking Over Their Money),” WorldNgayon, Nov. 21, 2026. [Online]. Available: https://worldngayon.com/protect-elderly-parents-from-scams/
@online{agron2026protectelderly,
  author       = {Agron, Edmon},
  title        = {{How to Protect Elderly Parents From Scams (Without Taking Over Their Money)}},
  year         = {2026},
  date         = {2026-11-21},
  organization = {WorldNgayon},
  url          = {https://worldngayon.com/protect-elderly-parents-from-scams/},
  urldate      = {}
}TY - ELEC AU - Agron, Edmon TI - How to Protect Elderly Parents From Scams (Without Taking Over Their Money) T2 - WorldNgayon PY - 2026 DA - 2026/11/21/ UR - https://worldngayon.com/protect-elderly-parents-from-scams/ Y2 - ER -
Cite the version you read; the page may be updated. Zotero and Mendeley can also import this page directly.