Table of Contents
Key Takeaway
- 📉 The verified print: a peso record low again — the peso closed at ₱64.17:$1 on October 27 — the 33rd record low of its year, the first-ever close past ₱64, with an intraday weakness of ₱64.20 (GMA News; Bankers Association of the Philippines data).
- 🏛️ The policy frame: the BSP delivered a fourth straight hike on October 22 — 50 basis points to 5.50% — and Governor Eli Remolona said the bank is not defending the peso at any level (Rappler).
- 💵 Who actually gains: families receiving dollars convert into more pesos per dollar than ever before — the advantage a former BSP analyst’s own column confirms for remittance households (Daily Tribune).
- 🔥 Who pays: peso earners and import-linked households — September inflation already ran 7.2%, and power and fuel costs are the named next losers (Philstar; BSP data).
- 🧭 The playbook in one line: split your remittance conversions, chase the effective all-in rate instead of the headline, park your peso surplus at the new higher yields, keep a deliberate dollar reserve, and never chase a floor the central bank refuses to defend.
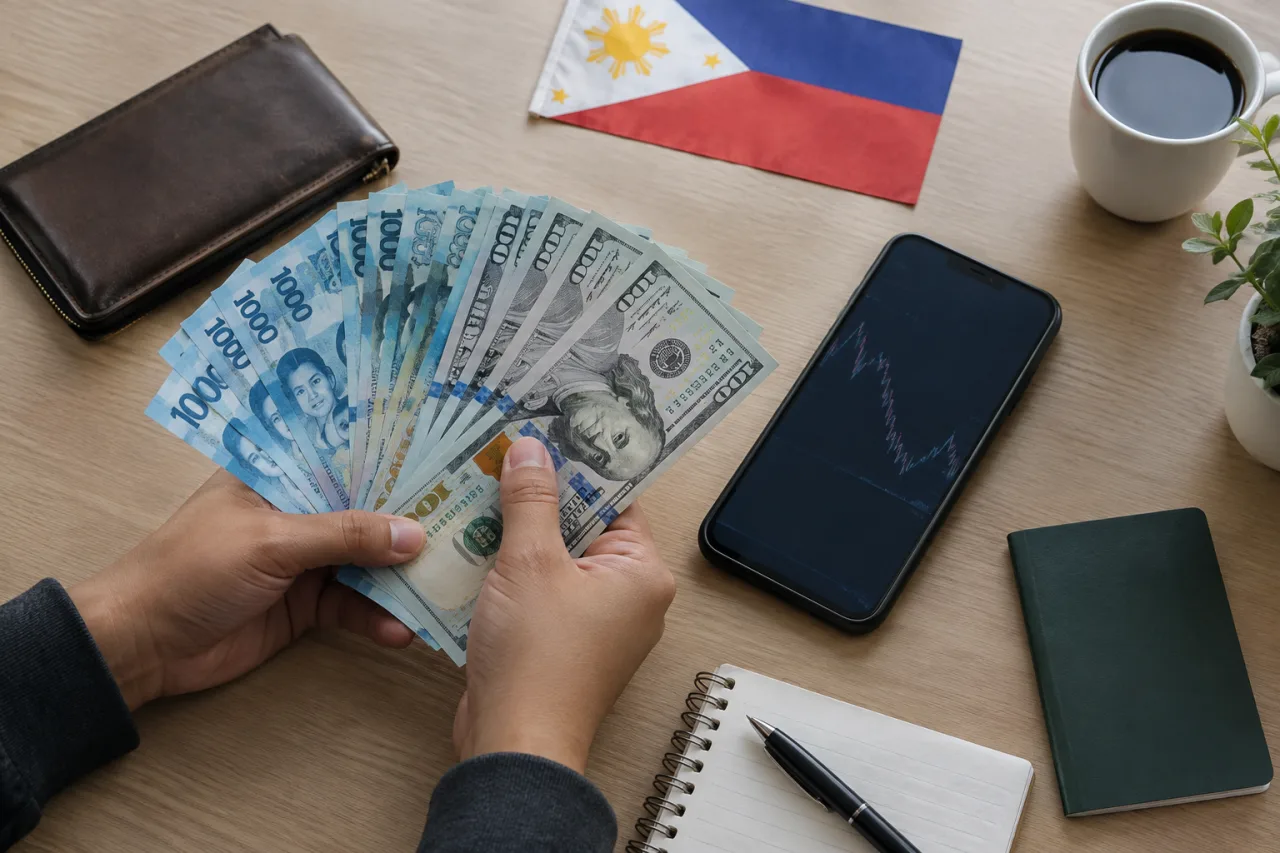
A peso record low has never been just a number for overseas Filipino families: it is the arithmetic that decides what your remittance buys this month. On October 27, 2026, that arithmetic changed again — the peso closed at ₱64.17 to the dollar, its 33rd record-setting close of 2026 and the first time it ever finished beyond ₱64. The Bankers Association of the Philippines data showed it opening at ₱63.95, briefly firming to ₱63.90, then sliding past the barrier with an intraday low of ₱64.20, on volume that grew about 4.7% to $1.73 billion (Philstar). Twelve days earlier, on October 15, the currency had closed above ₱63 for the first time in history. This is not a drift; it is a controlled slide with a policy engine behind it — the BSP jumbo-hiked 50 basis points on October 22 to battle inflation that already ran 7.2% in September, while publicly refusing to defend any exchange-rate level. For OFWs and their families, both halves of that sentence matter, and this playbook turns them into moves. Every number in the trail below is dated and sourced, and every option in the playbook is checked against what is actually available — because a record-low week spawns both real decisions and very loud bad advice.
The Peso Record Low Trail: October 15 to October 27
The slide has a sequence, and the sequence tells you who moved what.
- October 15: the peso closes above ₱63:$1 for the first time on record, its 29th all-time closing low of the year (Philstar).
- October 22: the Bangko Sentral ng Pilipinas Monetary Board raises the target reverse repurchase rate by 50 basis points — a jumbo, fourth consecutive hike, lifting the policy corridor to 5.5% deposit-side and 6.0% lending-side. That afternoon the peso sets its 30th record low at ₱63.52, citing inflation “accelerating further in the coming months” and Middle East oil pressure after Houthi attacks pushed Brent crude past $110 (the desk’s BSP jumbo-hike breakdown covers the full corridor math and the one outlier wire that printed 5.25%).
- October 23–26: ₱63.615, then ₱63.95 — the 32nd record close — as oil pressures compound: Brent at $116.72 by the 23rd. The PSEi drops 1.53% on the 26th, and the BSP posts a September balance-of-payments deficit of $3.144 billion — more than five times August’s $596 million and a sharp reversal from the $82 million surplus a year earlier (Asia Daily’s BSP data pull). That deficit is the mechanical weight pulling the currency down.
- October 27: ₱64.17 at the close — the 33rd record low per GMA’s print, the historic barrier gone, ₱64.20 the intraday floor. September’s inflation print of 7.2% (core 4.7%) does the explaining: imports, fuel and food pressures spread beyond the volatile basket, the BSP’s average-inflation forecast for 2026 stands at 6.1%, and the 2027 forecast was just raised from 5.4% to 6.0% (Rappler; Asia Daily).
Read the trail honestly and one conclusion follows: this is not a wobble that mean-reverts next week. The BSP has told you its method — hike for inflation, not for the exchange rate — and the country’s external balances are bleeding dollars. Any remittance plan built on “the peso bounces back soon” is a forecast, not a plan.
The Two-Sided Math of a Peso Record Low
Weakened currency is not one story; it is two, and OFW families sit on both sides.
The receiving side gains. Dollar remittances convert into more pesos per dollar than at any point in history. A former BSP analyst writing for the Daily Tribune puts the advantage directly: “For families receiving OFW remittances, the stronger dollar brings an advantage because money sent home converts into more pesos.” At ₱64.17, every $100 of remittance carries roughly ₱640 in additional pesos compared with the ₱58 zone where the year began — before fees. That is real money, and it is the one unambiguous win in this whole episode.
Everything peso-based pays a little more each week. The Philippine Star names the immediate next losers: electricity, fuel, and imported goods, all priced against a weaker currency. September’s 7.2% inflation was already the fastest spread beyond food and energy (core at 4.7%), and the BSP’s own projections say elevated inflation stays through 2027. A peso record low therefore quietly erodes the peso-denominated savings and salary that did not move — the purchasing power of the ₱100,000 sitting in a generic savings account is shrinking in real terms roughly as fast as the currency falls.
In our view, the honest family framing is this: the remittance inflow is your hedge arrival; the peso savings are your exposed position. The playbook below manages both sides.
Playbook Move 1: Split the Conversion, Don’t Chase the Rate
The single most durable move for remittance receivers in a peso record low week: convert in tranches tied to needs, not to headlines. A family that converts every dollar as it arrives at today’s ₱64.17 locks in the historic rate — genuinely good. A family holding dollars waiting for 65 or 66 is making a forecast the central bank itself has declined to make. The middle path: convert what the budget needs now, keep a tranche in dollars or a dollar-denominated account, and convert the rest on a schedule (weekly or monthly) rather than on emotion. This mirrors the dollar-cost-average discipline, applied to remittance timing — and it converts a currency question back into a budget question.
Playbook Move 2: Chase the Effective All-In Rate, Not the Billboard
In a peso record low environment, the difference between providers is no longer rounding. Remittance apps, banks, and exchange kiosks set their own spreads, and on a week when the mid-market moved 22 centavos in a day, a spread of one peso is a 1.6% real cost on every dollar sent. The move: before any send, compare the final pesos received — after every fee — against the ₱64.17 BAP reference, and compute your true all-in rate. Providers publish their rates differently; some quote a “zero fee” headline with a wider embedded spread. Western Union’s own guide to rate-shopping holds the universal mechanics — compare final amounts, watch the embedded spread, prefer transparent rates (Western Union). For OFW routes specifically, the desk’s digital remittance explainer breaks down how app-based rails, bank corridors and wallet-to-wallet transfers each take their cut, and why the same $500 can differ in received pesos across the three lanes.
Playbook Move 3: Put the Peso Surplus Where the New Rate Floor Lives
A peso record low plus a jumbo hike raises the yield on peso cash — and the market repriced fast. Before the decision, digital banks ran Maya promos at up to 15% p.a. conditions on the first ₱100,000 and 8% on Goals through year-end, with standard rates near 3% at SeaBank, GoTyme and Tonik; after 5.5% policy, term-deposit demand thickened and average BSP term-deposit rates climbed (BusinessWorld’s October 21 print, via the desk’s jumbo-hike piece). Bank ladder rates now run 5.375%–5.585% gross for 36–121 day placements at the largest lenders. The moves, in order of durability: (1) the emergency fund is the first parking spot — three to six months of peso expenses earning the new floor, per the desk’s emergency-fund guide; (2) time deposits and money-market funds capture the rate above that; (3) government securities (treasury bills, retail treasury bond windows) price off the 5.5% policy rate — watch the next RTB announcement via the Bureau of the Treasury rather than borrowing fixed-rate promises from group chats. One warning that comes with all of it: a higher rate floor also tempts unsolicited “guaranteed yield” pitches; the scam pressure of a stressed-rates week is covered in the desk’s global scam-reporting guide.
Playbook Move 4: Keep a Deliberate Dollar Reserve
In a peso record low stretch, the receiving family’s natural hedge is the dollar itself — held deliberately, not accidentally. A USD account or dollar-denominated time deposit (the BDO dollar money-market sleeve illustrates the product class at 3.26%) preserves the remittance option to convert when the family budget needs pesos rather than when the market’s mood changes. The proportion is a household decision; the principle is structural: dollar income + peso expenses = currency mismatch, and a small dollar residual is the cheapest hedge a remittance family owns. When the Bureau of the Treasury opens its next retail dollar bond window — the instrument built for exactly this mismatch — that is the moment to compare its yield against bank dollar deposits, not before.
Playbook Move 5: Don’t Bet Against a Peso Record Low With No Floor
Remolona’s line has two parts that matter: “We’re not hiking the policy rate to defend the peso,” and — the part fewer noticed — “We have estimates of how much the peso has to move before it becomes inflationary, and that’s when we tend to intervene.” Translation for households: intervention exists, but it is inflation-triggered, not level-triggered. There is no announced floor at ₱64, ₱65, or ₱66 to lean against. The speculative position — holding pesos idle while waiting for a bounce, or over-borrowing to time a convert — has no policy backstop. The desk’s de-dollarization map shows the global context the market is trading against; the household version of that map is simpler — match your currency exposure to your currency bills.
What Would Change This Peso Record Low Playbook
Every analysis on this desk ships with the prints that would break it, and a “no-floor” reading is no exception. The playbook assumptions fail if:
- The BAP prints a close back below ₱63.95 with the BSP’s dollar-selling visible in reserves data — a level-defended episode would revive the bounce forecast the current reading excludes.
- Inflation breaks the forecast path — if October’s print comes in below the 6% trajectory, the hiking cycle pivots and the yield-floor move needs re-pricing.
- A BSP intervention escalation — forward contracts, new foreign-currency rules, or a surprise retail-dollar-bond window — each changes which parking spot pays best.
- The Middle East oil premium unwinds — Brent’s $110–117 pressure band was a named driver; a durable de-escalation would deflate the slide’s main engine (verify via GMA/BSP statement updates).
What the Evidence Supports, by Reader Situation
This is an education desk, not an advisory service — the verdicts are decision inputs for different situations, never instructions.
- If your family receives remittances: the verified math favors converting on time, in tranches, at the best all-in rate — and the record rate itself is a tailwind the peso has never offered you. Inflation is the counterweight: convert what the household plan needs, yield the surplus at the new floor, hold the tranche in dollars.
- If you earn in pesos: the named cost pressures (power, fuel, imports) plus a 7.2% September print mean idle peso cash loses ground fastest; the emergency fund at digital-bank rates, then deposits and government securities, are the defensible parking order — and imported-cost budgets should be re-checked monthly, not quarterly.
- If you’re deciding whether to wait for a better rate: the central bank has said it is not defending a level, the external balances are the weight, and no published forecast supports a date. Waiting is a market position; splitting is a plan. Choose the one you can explain to the family budget.
FAQ: the Peso Record Low and OFW Remittances
What is the peso’s record low right now?
₱64.17 to the dollar at the October 27, 2026 close per BAP-sourced GMA reporting — the 33rd all-time closing low of 2026, the first close past ₱64, with ₱64.20 the intraday low. It came twelve days after the currency first closed past ₱63.
Does a weak peso mean OFW families earn more from remittances?
On conversion, yes — dollars convert into more pesos than ever, exactly as the Daily Tribune’s former-BSP analyst column states. The catch is downstream: the same weakness feeds the 7.2% September inflation (core 4.7%) through fuel, power and imports, so the gained pesos buy less than the headline suggests.
Should we convert all dollars now while the rate is high?
In a peso record low stretch, converting on needs and budget, in tranches, is the defensible plan because it requires no forecast. Holding all dollars for a bounce — or converting everything at once — are both market positions. The BSP has said it will not defend any level, so there is no policy floor to wait for.
Where do peso savings earn after the BSP jumbo hike?
The policy rate at 5.50% (deposit corridor 5.0–6.0%) pulled up digital-bank rates (promos up to 15% p.a. conditional at Maya, ~3% standard elsewhere), bank time deposits (roughly 5.4–5.6% gross at large lenders), and government securities that price off the policy rate. Parking order: emergency fund first, then deposits/UITFs, then securities windows as they open.
Will the BSP defend the peso?
Governor Eli Remolona’s October 22 briefing says the bank hikes for inflation, not for the exchange rate, and intervenes only when the peso’s move becomes inflationary — “We’re not hiking the policy rate to defend the peso” (Rappler). No defended level exists in the current policy.
What single mistake should families avoid this week?
During a peso record low stretch, chasing rate headlines with full conversions in one shot, and unsolicited “guaranteed yield” or “FX arbitrage” pitches that spike during stressed weeks. Verify every provider rate against the ₱64.17 reference and treat any guaranteed-arbitrage pitch as a scam flag until proven otherwise.
Financial Disclaimer
This article is for general information and education only. It is not financial, investment, legal or tax advice, and it does not recommend the purchase, sale or holding of any asset, currency or instrument. Foreign exchange rates move quickly and every figure cited was sourced on October 26–28, 2026; rates and policy may have changed since publication. WorldNgayon does not hold any position in the currencies or instruments discussed, and no content on this site should be acted upon without independent verification and, where appropriate, advice from a licensed professional.
- philstar.com/business/2026/10/28/2566128/peso-sinks-past-64-1-barrier — Philstar
- philstar.com/business/2026/10/26/2565848/peso-sinks-record-p6395-doll… — Philstar
- Official bsp.gov.ph — Bangko Sentral ng Pilipinas
- gmanetwork.com/news/money/economy/1007351/peso-dives-to-33rd-record-l… — record low per GMA’s print
- rappler.com/business/philippine-peso-dollar-exchange-rate-record-low-… — Rappler
- br.asiadaily.org/news/16657 — Asia Daily
- tribune.net.ph/2026/10/25/when-the-peso-buys-less — Daily Tribune
- westernunion.com/blog/en/best-exchange-rate — Western Union
- Official treasury.gov.ph — Bureau of the Treasury
External sources linked in this article, in order of first mention. Spotted an error or a broken link? Tell us.
Cite this pagePublished Oct 29, 2026
Agron, E. (2026, October 29). Peso at 64.17 Record Low: the OFW Remittance Playbook for a Weakening Peso. WorldNgayon. https://worldngayon.com/peso-record-low-ofw-playbook/
Agron, Edmon. “Peso at 64.17 Record Low: the OFW Remittance Playbook for a Weakening Peso.” WorldNgayon, 29 Oct. 2026, worldngayon.com/peso-record-low-ofw-playbook/.
Agron, Edmon. “Peso at 64.17 Record Low: the OFW Remittance Playbook for a Weakening Peso.” WorldNgayon, October 29, 2026. https://worldngayon.com/peso-record-low-ofw-playbook/.
Agron, E. (2026) ‘Peso at 64.17 Record Low: the OFW Remittance Playbook for a Weakening Peso’, WorldNgayon, 29 October. Available at: https://worldngayon.com/peso-record-low-ofw-playbook/.
E. Agron, “Peso at 64.17 Record Low: the OFW Remittance Playbook for a Weakening Peso,” WorldNgayon, Oct. 29, 2026. [Online]. Available: https://worldngayon.com/peso-record-low-ofw-playbook/
@online{agron2026pesorecord,
  author       = {Agron, Edmon},
  title        = {{Peso at 64.17 Record Low: the OFW Remittance Playbook for a Weakening Peso}},
  year         = {2026},
  date         = {2026-10-29},
  organization = {WorldNgayon},
  url          = {https://worldngayon.com/peso-record-low-ofw-playbook/},
  urldate      = {}
}TY - ELEC AU - Agron, Edmon TI - Peso at 64.17 Record Low: the OFW Remittance Playbook for a Weakening Peso T2 - WorldNgayon PY - 2026 DA - 2026/10/29/ UR - https://worldngayon.com/peso-record-low-ofw-playbook/ Y2 - ER -
Cite the version you read; the page may be updated. Zotero and Mendeley can also import this page directly.