Table of Contents
The De-Dollarization Map: What BRICS Built, What Broke, and What the Peso Should Watch
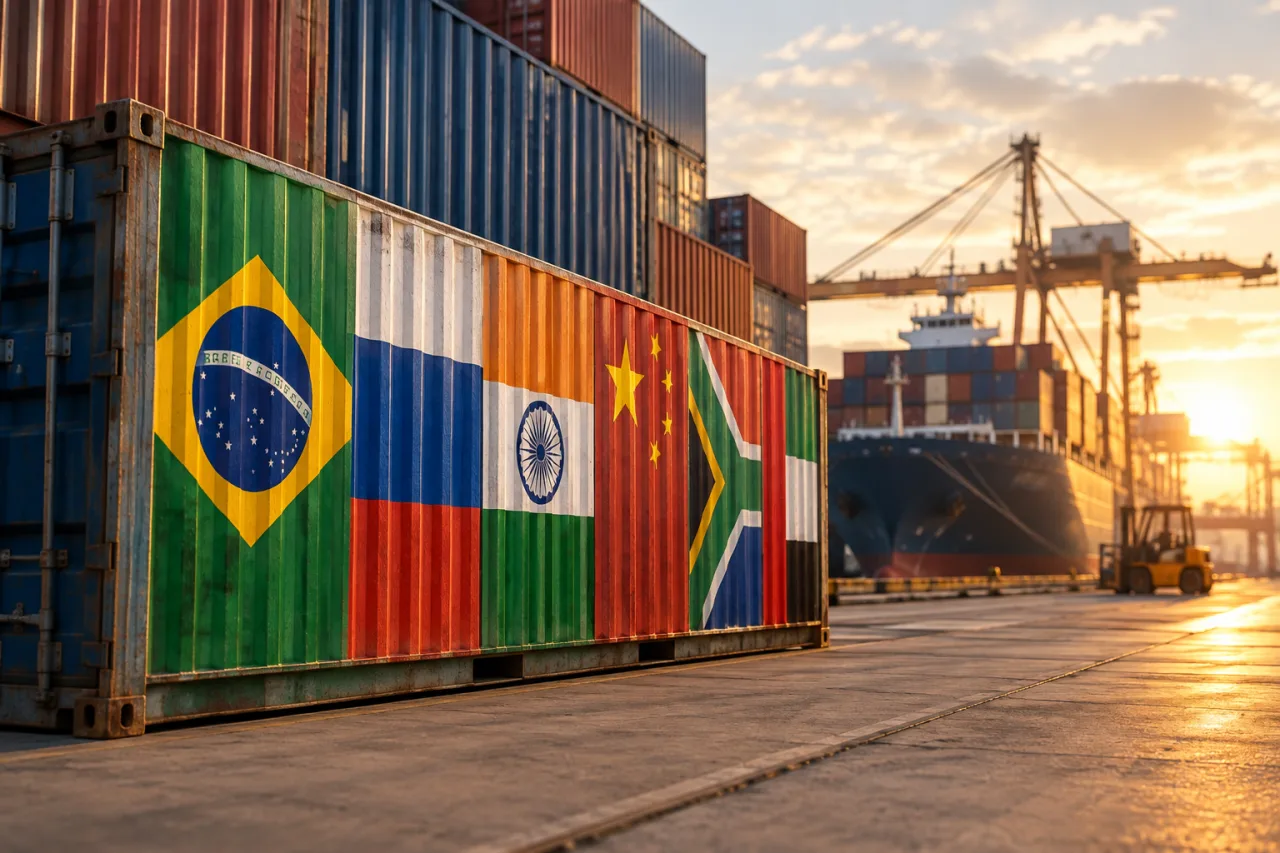
De-dollarization mapped (October 2026): the dollar still holds 58% of world foreign reserves and the euro just 20% (Atlantic Council’s monitor on record) — the throne is not lost | what BRICS built: local-currency trade channels, development-bank rails, settlement platforms (and the region’s peso-relevant lesson: our mbridge coverage traced the project’s contested exit), plus the largest gold accumulation wave in decades | what “broke”: the common-currency prophecy — the promised single BRICS currency never shipped | what the peso should watch: reserve flows and corridor settlement costs, not headlines
Key Takeaway
- 🗺️ De-dollarization today is a map of small shifts, not a coup: the dollar still anchors 58% of global reserves (euro 20%) — the honest read measures the margins: which corridors settle locally, which reserves diversify, which banks accumulate alternatives (gold foremost).
- 🏗️ What BRICS actually built: local-currency trade lines, the development-bank layer, payment/settlement pilots (the mbridge project this desk traced — including the contested exit stories), and the fastest gold-buying run in modern central-banking history. Real infrastructure, slow adoption.
- 🪙 What broke: the single BRICS currency — the launch-date prophecy that powers the headlines never shipped, and the honest explainer says so plainly: coordination, convertibility and reserve-trust don’t arrive by summit communiqué.
- 🇵🇭 What the peso should watch: three things, not twenty — the reserve-allocation trend (how other central banks price the dollar’s stability), settlement-cost trends on the corridors the OFW economy runs on, and gold’s role in the region’s reserves (our China-gold piece traced the investor-facing corner).
- ⚠️ Explainer, not forecast: no currency calls; the map reports what shipped, what stalled and what the data says — decisions belong to licensed advisers.
De-dollarization is the decade’s most quoted word and its least examined process: half the commentary announces the dollar’s funeral, the other half pretains nothing is happening, and the honest map shows a third thing — a slow, real, structural reshaping of the margins around a leader that remains far ahead. The numbers on record frame it: the dollar holds 58% of global foreign reserves against the euro’s 20% — no other currency clears single digits with the same liquidity — while the BRICS grouping builds alternative rails, diversifies reserves, and talks a bigger game than it ships. This piece is the desk’s map, built for the Filipino professional whose salary, remittances and savings all still touch dollar rails: what de-dollarization actually means, what BRICS built (and how fast it’s adopting), what broke (the common-currency story, honestly told), what stayed untouched (the plumbing that prices your corridor), and the three watch-factors the peso should track without prophecy.
What De-Dollarization Actually Means — the Four Layers
- Layer 1 — Reserve allocation: central banks shifting reserve mixes (away from pure dollar stacks toward gold and a basket) — the slowest layer, measured in years, and the one the 58%-share number tracks.
- Layer 2 — Trade settlement: countries pricing bilateral trade in local currencies — real, growing on specific corridors (energy being the headline), still marginal on the global ledger.
- Layer 3 — Payment infrastructure: the rails themselves — alternative messaging systems, settlement platforms and project pilots (mbridge among them) — the engineering layer that decides whether “local-currency trade” runs at scale or stays a pilot.
- Layer 4 — The propaganda layer: the launch-date announcements, the summit symbolism, the forecast chart-memes — the layer that produces the word “de-dollarization” as a headline rather than a measurement. A map is only honest when it tells the four layers apart.
What BRICS Built — the Infrastructure That Actually Runs
- Local-currency settlement corridors. The grouping’s economies pushed yuan, rupee, ruble, real and rand pricing into bilateral trade where sanctions pressure or corridor economics made dollars awkward — the visible wins concentrate in the energy lanes and among the sanctioned members; the honest read is corridor-by-corridor, not global.
- The development-bank and fund layer. The New Development Bank’s local-currency lending gave the grouping an institution-shaped piece of the alternative architecture — slow, real, budget-sized rather than headline-sized.
- Settlement-platform pilots. The mbridge project — the multiple-central-bank digital-currency settlement platform this desk covered through the Saudi exit story — is the layer’s flagship experiment: a working platform with contested membership, the pattern that defines the whole lane.
- Gold accumulation. The central banks of the grouping added gold at the fastest modern pace — the reserve-diversification signal in its purest form, and the layer our China-gold-vs-bitcoin piece traced on the investor side.
- What they did NOT build (yet): a common currency, a unified settlement standard adopted by all members, or an alternative to the dollar’s deep-liquidity markets. The build list is real; the to-do list is longer.
The Timeline: How the Margin Actually Moved, Era by Era
A map without a timeline invites prophecy, so the desk’s version pins the real eras — stated honestly, with the record’s uncertainty limits:
- 1944-1971 — the fixed-dollar era. The Bretton Woods gold-dollar peg ran the postwar system; the peg broke in 1971, and the dollar kept the reserve throne without gold — the first lesson: reserve status survives the removal of its original anchor, because the substitute anchors (markets, treasury depth, invoicing habit) proved stickier.
- 1971-1999 — the floating era consolidates. Dollar markets deepened, commodity pricing standardized in dollars, and the reserve share held near its highs. De-dollarization talk existed here too — inflation-year talk, oil-shock talk — and it faded; the honest precedent for modern prophecy.
- 1999-2008 — the euro era’s ceiling. The euro launched (the only modern challenger with full institutional architecture) and plateaued at its ~20% share — the ceiling that tells you what a genuine challenger’s realistic decade-pace looks like: institutional plumbing, not summit announcements.
- 2008-2018 — the diversification signal starts. The global financial crisis planted the diversification instinct; central banks began pricing reserve risk beyond yield (the sanction-era caution was still hypothetical), and the gold-buying habit re-emerged as a policy instrument.
- 2018-2022 — sanctions and the freeze test. Reserves froze (the Afghan central bank’s assets), sanctions weaponized SWIFT access — and the diversification instinct turned from prudent to urgent across the non-allied world: this is the era the modern de-dollarization headlines date from, and the layer’s real acceleration (local-currency corridors, gold runs) is its honest product.
- 2022-2026 — the infrastructure era. Settlement pilots (mbridge among them), BRICS expansion talks, the common-currency prophecy cycle — and the reserve record’s honest verdict: the dollar’s 58% moved only at the margins while the margins’ infrastructure multiplied. The era’s story is not collapse; it is optionality being built.
Read the six eras in a row and the honest pattern shows: every de-dollarization wave so far produced infrastructure and habit-changes at the margins while the core held — the map’s job is measuring each layer’s speed so the prophecy layer can be priced at zero.
What Broke — the Common-Currency Promise, Honestly Filed
The single BRICS currency — the “launch date” the search bars keep asking about — never shipped: no currency was launched, no launch date exists, and the honest answer to the prophecy is structural, not political. A reserve currency needs three things no summit has manufactured: deep, open markets for the currency’s debt; convertibility that foreigners trust at size; and a legal-institutional anchor that survives political weather between members. The euro took decades inside one legal system with democratic institutions on its shoulders — the BRICS grouping spans five economies with different capital controls, different political systems and different interests in the dollar system itself (several members are among the dollar system’s largest beneficiaries). The prophecy layer broke on arithmetic; the infrastructure layer keeps building; and the map keeps the two in separate rooms — where they belong.
The Dollar’s Moat, Measured — Why 58% Is Deader Than It Looks
The honest case for the dollar’s durability is not complacency; it is plumbing. The dollar clears the deepest, most liquid markets on record (the treasury market’s liquidity is the world’s shock absorber), it is the unit almost every commodity ledger prices in, the cross-border credit system’s contracting currency, and the invoicing habit inside half the world’s trade paperwork. Reserves reflect that — 58% is the record-keeping echo of the plumbing, not a popularity vote. De-dollarization at the margins is real precisely BECAUSE the core is so large: corridors shift where sanctions force them, diversifiers buy gold where yields don’t pay, and the margin’s movement is measurable without ever flipping the core. The map’s first honest rule: never read the margin as the headline, and never read the headline as the margin.
What the Peso Should Watch — the Filipino Professional’s Three-Factor Board
- 1. Reserve-allocation trend lines. The share numbers (58%/20% and their yearly prints) + the gold-share trend = the stability backdrop every emerging-market currency borrows its risk premium from. Slow-moving, worth a quarterly glance — and the honest reason the peso’s dollar-peg anxiety and the de-dollarization debate are only loosely coupled.
- 2. Corridor settlement costs. The OFW economy’s real exposure is the corridor, not the reserve share: the rails our remittance pieces cover — and the reason settlement-layer engineering (including stablecoin and CBDC pilots on those corridors) matters more to a Filipino professional’s monthly bill than any summit’s currency talk.
- 3. Gold’s role in the region’s reserves. The neighboring central banks’ diversification signals price the region’s hedge behavior — the layer our China-gold piece turned into practical investor reading. Watch the reserve print; skip the meme-print.
FAQ
What is de-dollarization in simple terms?
The slow reduction of the US dollar’s dominance at the margins of world finance — countries diversifying reserves (gold), settling some trade in local currencies, and building alternative payment rails — while the dollar itself still anchors 58% of world reserves. It is a margin story, not a coup. De-dollarization measures three layers at once: how much value central banks park outside the dollar stack, how much trade prices in local currencies on specific corridors, and how much settlement runs on non-dollar rails — each layer moving at its own speed, and none of them flipping overnight.
Is the BRICS currency real?
A single BRICS common currency was never launched — no launch date exists despite years of headline prophecy. What is real: the grouping’s local-currency trade settlements, its development bank, settlement-platform pilots (mbridge), and the fastest central-bank gold buying in modern records. The prophecy broke; the infrastructure builds.
What percentage of world reserves is still in dollars?
58% of world foreign reserve holdings per the Atlantic Council Dollar Dominance Monitor’s data on record — with the euro at 20% and no other currency near single-digit-plus liquidity at scale. The share moves slowly; the margin shifts matter more than the headline level.
Why is de-dollarization so slow?
Because a reserve currency is plumbing, not a preference: deep liquid markets (the treasury complex), commodity invoicing conventions, credit-contracting habits and legal anchors all reinforce the incumbent. De-dollarization at the margins (corridors, gold, pilots) is faster — those layers move with politics and pricing — while the core requires markets and institutions no grouping has assembled yet, and a fallback liquidity the alternatives haven’t shown. The honest pace-set is the euro’s own history: a full legal, institutional and market architecture took decades to reach its 20% share — and it never displaced the incumbent.
Should Filipinos worry about de-dollarization?
Worry is the wrong frame — watch instead: the reserve-share prints (quarterly), the settlement costs on the corridors the OFW economy actually uses (the real peso exposure), and the region’s gold-allocation signals. De-dollarization affects the peso through those three channels, each slow, each measurable — and none of them a reason to time a savings decision. The honest household strategy in every reserve regime: earn in the corridor’s currency, keep the emergency fund in the currency the bills are paid in, and let investments diversify on their own evidence — the de-dollarization map is context for decisions, not a decision.
What is mbridge and why did it matter?
The multi-central bank digital-currency settlement platform built with BIS participation and the region’s largest economies — the de-dollarization lane’s flagship engineering experiment, covered on this desk through the Saudi exit story that showed the project’s contested membership reality. Read the desk’s mbridge piece for the full trail.
Financial Disclaimer: This article is a macro-education explainer for general information only — it is not investment, currency or financial advice, and no content here is a forecast or trading guidance for any currency. Reserve data and program facts are cited from sources on record (October 2026) and change; verify current figures on the official data pages before decisions. Currency markets carry substantial risk; consult a licensed financial adviser for personal decisions. worldngayon.com holds no position in any currency named and is not liable for outcomes from actions taken on this content.
Sources: the Atlantic Council Dollar Dominance Monitor (58% dollar reserve share; euro 20%; the BRICS-infrastructure indicator framework); the desk’s own pieces — the mbridge exit trail, the China gold-vs-bitcoin analysis, and the remittance-corridor pieces for the peso-side plumbing — all on record as of October 2026; reserve-share prints per IMF COFER data as reported by the monitor.
- atlanticcouncil.org/programs/geoeconomics-center/dollar-dominance-mon… — Atlantic Council Dollar Dominance Monitor
External sources linked in this article, in order of first mention. Spotted an error or a broken link? Tell us.
Cite this pagePublished Oct 29, 2026
Agron, E. (2026, October 29). The De-Dollarization Map: What BRICS Built, What Broke, and What the Peso Should Watch. WorldNgayon. https://worldngayon.com/de-dollarization-map/
Agron, Edmon. “The De-Dollarization Map: What BRICS Built, What Broke, and What the Peso Should Watch.” WorldNgayon, 29 Oct. 2026, worldngayon.com/de-dollarization-map/.
Agron, Edmon. “The De-Dollarization Map: What BRICS Built, What Broke, and What the Peso Should Watch.” WorldNgayon, October 29, 2026. https://worldngayon.com/de-dollarization-map/.
Agron, E. (2026) ‘The De-Dollarization Map: What BRICS Built, What Broke, and What the Peso Should Watch’, WorldNgayon, 29 October. Available at: https://worldngayon.com/de-dollarization-map/.
E. Agron, “The De-Dollarization Map: What BRICS Built, What Broke, and What the Peso Should Watch,” WorldNgayon, Oct. 29, 2026. [Online]. Available: https://worldngayon.com/de-dollarization-map/
@online{agron2026dedollarization,
  author       = {Agron, Edmon},
  title        = {{The De-Dollarization Map: What BRICS Built, What Broke, and What the Peso Should Watch}},
  year         = {2026},
  date         = {2026-10-29},
  organization = {WorldNgayon},
  url          = {https://worldngayon.com/de-dollarization-map/},
  urldate      = {}
}TY - ELEC AU - Agron, Edmon TI - The De-Dollarization Map: What BRICS Built, What Broke, and What the Peso Should Watch T2 - WorldNgayon PY - 2026 DA - 2026/10/29/ UR - https://worldngayon.com/de-dollarization-map/ Y2 - ER -
Cite the version you read; the page may be updated. Zotero and Mendeley can also import this page directly.