Table of Contents
Key Takeaway
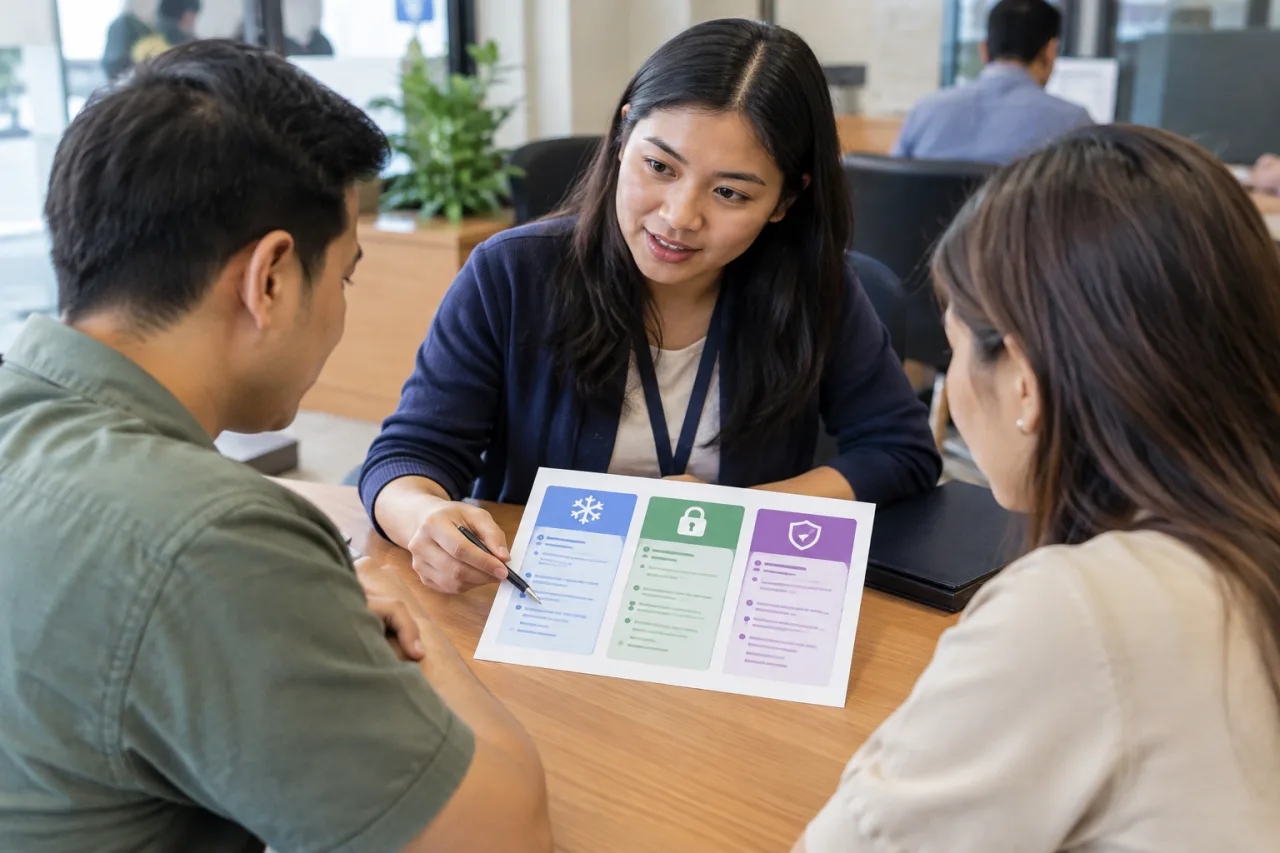
- 🧊 The credit freeze is the default: it blocks new credit at all three bureaus, costs nothing under federal law, and lasts until you lift it, which makes it the answer for anyone who is not actively applying for credit.
- 🔒 The credit lock does the same job as the freeze: the bureaus’ paid lock products work similarly but carry no federal-law guarantee, so paying monthly buys convenience, not protection.
- 🚨 The fraud alert is the layering tool: it lets lenders see your file but requires them to verify identity first; one year for the initial alert, seven years for identity-theft victims.
- 🧒 Children get this protection too: a free credit freeze covers any child under 16, and guardians or conservators can freeze an adult’s file with the right documents.
- ⏱️ The legal clocks matter in practice: freezes land within one business day by phone or online, and lift within one hour, so the freeze is also workable on the day a car loan or apartment application comes due.
Credit protection has a vocabulary problem, and it costs people money every month. Three products share one shelf: the security freeze, the credit lock and the fraud alert. Two of them are free, and one of them you have a right to by law. The Bureau’s consumer page states it in one line: credit locks are no more effective than security freezes, which are free. This guide separates the three, shows who each one fits, and walks the placement steps with the timing rules that make them usable on a deadline.
Credit Freeze: the Block That Starts From the Law
A security freeze restricts access to your credit file, so a lender that cannot pull the file cannot open the account. The Consumer Financial Protection Bureau describes the mechanism plainly and notes the trade you accept: legitimate applications stall too, which is why the freeze includes a lift process on demand. While the freeze is in place, a short list of viewers still gets through, including creditors you already owe, certain government agencies such as child-support enforcement, and monitoring services you personally hired, so the freeze targets new credit, not your existing life.
The federal rules give the freeze its schedule. Place a request by phone or secure electronic means and the bureau must act within one business day; a lift request must be honored within one hour by those channels; mail requests get three business days. Written confirmation of the freeze arrives within five business days, along with the removal instructions. The freeze costs nothing to place, nothing to lift, and it never expires on its own.
One nuance matters for job hunters and renters: the free-freeze law does not apply to requesters who pull your file for employment, tenant screening or insurance purposes. Those inquiries move differently, and they belong in the review you do when the freeze first goes on.
Credit Lock: the Same Wall, Sold as a Product
The bureaus sell credit locks under brand names, often bundled into monthly credit-monitoring subscriptions. A lock and a freeze do similar work: both aim at the same door, and the bureau apps make toggling a lock feel faster than filing a freeze. What the lock does not carry is the law. The federal freeze statute guarantees the timing rules above at no charge; a lock is a contractual product that can change price, terms and features. The CFPB’s phrasing exists to end the upsell: if you want a free freeze guaranteed by federal law, opt for the freeze, not the lock.
That does not make locks useless. An app-based lock is fast to toggle from a phone, which matters for an aging parent who wants one big obvious switch, or for a household that prefers to manage access from an app rather than a PIN-protected process. The fair comparison is about ownership of the rules: the freeze protects you by statute, the lock protects the vendor’s subscription revenue, and households that understand the difference stop paying for a shadow of the free tool.
Fraud Alert: the Floor That Asks Lenders to Call First
A fraud alert works on a different mechanism: it does not block access to the file, it obligates businesses that view it to take reasonable steps to verify identity before issuing credit, which in practice means a call or extra verification before the account opens. It comes in three flavors. The initial alert lasts one year and can be renewed, and placing it at one bureau requires the bureau to notify the other two. The extended alert lasts seven years and belongs to confirmed identity-theft victims who can supply the FTC or police report, and it adds two extra free credit reports per bureau per year. The active-duty alert, built for deployed service members, lasts one year, renews for the deployment, and removes the member’s name from prescreened marketing lists for two years.
The alert also stacks. A household can carry a freeze and an alert on the same file, which is exactly what the recovery sequence in our stolen Social Security number guide recommends: freeze first, then layer the alert, because the two mechanisms fail differently and cost nothing to run together. The alert’s call-first step is also what defeats a cloned family voice, which our AI voice cloning scam guide unpacks
Place It, Lift It, and Keep the Proof
Run the placement as a small project and it stays invisible afterward. Set aside thirty minutes, open each bureau’s freeze page, and place the security freeze online at Equifax, Experian and TransUnion one at a time, since the law treats each as its own filing. Phone and mail work too, at the statutory speeds, but the online route returns a confirmation on the spot.
Save what each bureau issues the day the freeze lands: the confirmation number, the PIN or password the bureau assigns for lift requests, and the removal instructions that arrive in the written confirmation. A printed folder or a password-manager entry both work; the point is that a lift request three years from now should take minutes, not a rediscovery project. Keep the same record for the children’s credit freeze paperwork, because those files stay untouched the longest and the paperwork is the only key.
Lifting follows the mirror of the placement. Call or use the bureau’s site with the PIN, name the dates or the creditor, and the statutory one-hour clock starts; the mail route takes three business days, which is worth remembering only because application paper checks sometimes arrive that way. A permanent removal uses the same channel. Families that run the lift-refreeze pattern with one bureau at a time keep continuous coverage on the other two files, which is the whole trick.
Children and Incapacitated Adults: the Freezes That Guard a Blank File
A child’s credit file is supposed to be empty, which makes a frozen blank file the cheapest insurance a family can buy. federal rules give every parent a free freeze for children under 16, placed at all three bureaus in the child’s name, and the bureaus publish specific instructions for the minor process, which requires proof of authority. The freeze stays until you say otherwise, and it stops cold the specific fraud that often survives unnoticed for a decade: accounts opened in a kid’s name and discovered when the grown child applies for a first loan. The child process asks for the child’s birth certificate and Social Security card plus your government ID, and it differs slightly by bureau, so read each minor-freeze page rather than guessing the forms. Families that place the three freezes before the child ever pulls credit never learn about this class of fraud from a rejection letter years later.
The same statute covers incapacitated adults: a guardian, a conservator or a holder of a valid power of attorney can place the free freeze for the person they represent, using the bureau procedures for that role. Both cases share the same logic. The people least able to monitor a credit file are the people the freeze serves best, because the freeze does the monitoring for them.
The Common Freeze Mistakes That Waste the Protection
Four mistakes account for most of the coverage gaps families report. Freezing only one bureau is the first: two open files still let a thief open an account, so the freeze belongs at Equifax, Experian and TransUnion every time. Forgetting the lift timing on application day is the second; the one-hour lift rule is the reason a frozen file does not have to cost you a loan, so time the lift around the application instead of leaving files open for weeks. Losing the PINs and confirmation letters is the third; store them with the same care as the file they protect. Assuming a freeze blocks everything is the fourth, and the list of exempt viewers above is the correction: existing creditors, some government agencies and your own monitoring service still see the file, and a freeze never touches inquiries for jobs, apartments or insurance.
There is one more pattern worth naming: the freeze that gets placed after a scare and quietly lifted a month later because an application annoyed someone. Lifts should be temporary by design, one bureau for one application, and the re-freeze belongs in the same hour as the approval letter.
The Decision, In Three Questions
Are you actively applying for new credit this month? If not, the credit freeze is the standing answer, at all three bureaus, today. Are you a confirmed identity-theft victim, or do you have a service member on deployment? Then the alert layers on top of the freeze: extended or active-duty respectively, because neither costs anything in the presence of the freeze. Are you paying a monthly subscription for a lock with no special features you actually use? Cancel it and place the free freeze, keeping the app only if its one-tap toggle genuinely serves the household. A family can read the account-protection sequence in our guide to protecting elderly parents and stop a wide range of new-account fraud with the freeze-and-alert pair, and the pair costs nothing to run.
FAQ
Is a credit lock as good as a credit freeze?
Functionally similar, legally different. A lock toggles the same door through a paid product, while the security freeze is guaranteed free by federal law with fixed timing rules for placement and lifting. The CFPB’s own guidance tells consumers to pick the freeze when they want the free, law-backed option.
How long does it take for a credit freeze to take effect?
One business day when you place it by phone or through secure electronic requests, and three business days by mail. A lift lands within one hour on phone and electronic channels, which is why the freeze survives contact with real life: you can open it for the morning and close it after the loan decision.
Can a creditor still check my credit report when the freeze is on?
Some can. Existing creditors keep access to their own accounts, certain government agencies such as child-support enforcement keep theirs, and any monitoring service you personally signed up for still sees the file. The freeze targets new credit by strangers, which is why your score and your existing accounts behave as before.
What happens if I lose the freeze PIN a bureau gave me?
Go back to the bureau’s freeze page and request a replacement through its identity-verification steps, which is exactly why the confirmation letter told you how to remove the freeze in writing. The PINs are recoverable; the file stays frozen while you recover them, which is the failure mode the design prefers.
Does a credit freeze hurt my credit score?
No. A credit freeze restricts who can see the file, not what is in it, and the FTC freeze guidance states plainly that freezing does not affect your score. Accounts continue to report, and your history and scores keep moving as before.
Can I put a credit freeze on my child’s credit report?
Yes, for any child under 16, free of charge, at all three bureaus, and the freeze stays until you remove it. The bureaus publish separate instructions for minors, and the process requires documents proving your authority over the child’s file. Guardians and conservators can do the same for the adults they represent.
Do I still need a fraud alert if I have a credit freeze?
You can run the fraud alert next to your credit freeze, and victims usually should. The freeze blocks file access for new credit, while the alert asks lenders that see the file to verify identity first; the extended version lasts seven years and adds free credit reports for confirmed victims. They cost nothing together, so layering is the default for anyone who has already had an identity theft event.
What happens to a credit freeze when I need a loan or apartment?
Lift it at the one bureau the lender uses, send the application, and re-freeze when the pull is done. The one-hour lift rule on phone and electronic requests turns the freeze from a barrier into a switch, and the pattern works the same for car loans, rentals and credit-card applications. The only requests unaffected by the freeze law are employment, tenant-screening and insurance pulls, which proceed by their own rules.
- Official consumerfinance.gov/ask-cfpb/what-is-a-credit-freeze-or-security-free… — Bureau’s consumer page
- Official consumer.ftc.gov/articles/credit-freezes-and-fraud-alerts — FTC freeze guidance
- Official usa.gov/credit-freeze — one-hour lift rule
External sources linked in this article, in order of first mention. Spotted an error or a broken link? Tell us.
Cite this pagePublished Nov 21, 2026
Agron, E. (2026, November 21). Credit Freeze vs Credit Lock vs Fraud Alert: Which One Your File Needs. WorldNgayon. https://worldngayon.com/credit-freeze-vs-lock-vs-fraud-alert/
Agron, Edmon. “Credit Freeze vs Credit Lock vs Fraud Alert: Which One Your File Needs.” WorldNgayon, 21 Nov. 2026, worldngayon.com/credit-freeze-vs-lock-vs-fraud-alert/.
Agron, Edmon. “Credit Freeze vs Credit Lock vs Fraud Alert: Which One Your File Needs.” WorldNgayon, November 21, 2026. https://worldngayon.com/credit-freeze-vs-lock-vs-fraud-alert/.
Agron, E. (2026) ‘Credit Freeze vs Credit Lock vs Fraud Alert: Which One Your File Needs’, WorldNgayon, 21 November. Available at: https://worldngayon.com/credit-freeze-vs-lock-vs-fraud-alert/.
E. Agron, “Credit Freeze vs Credit Lock vs Fraud Alert: Which One Your File Needs,” WorldNgayon, Nov. 21, 2026. [Online]. Available: https://worldngayon.com/credit-freeze-vs-lock-vs-fraud-alert/
@online{agron2026creditfreeze,
  author       = {Agron, Edmon},
  title        = {{Credit Freeze vs Credit Lock vs Fraud Alert: Which One Your File Needs}},
  year         = {2026},
  date         = {2026-11-21},
  organization = {WorldNgayon},
  url          = {https://worldngayon.com/credit-freeze-vs-lock-vs-fraud-alert/},
  urldate      = {}
}TY - ELEC AU - Agron, Edmon TI - Credit Freeze vs Credit Lock vs Fraud Alert: Which One Your File Needs T2 - WorldNgayon PY - 2026 DA - 2026/11/21/ UR - https://worldngayon.com/credit-freeze-vs-lock-vs-fraud-alert/ Y2 - ER -
Cite the version you read; the page may be updated. Zotero and Mendeley can also import this page directly.