Table of Contents
Key Takeaway
- 💰 Eligibility in two numbers: a one-month SSS salary loan needs 36 posted monthly contributions, a two-month loan needs 72, and both need 6 posted within the last 12 months before you apply.
- 📈 The rate is 8% per year (0.67% monthly) for members in good standing, and under Circular 2026-005 the interest is deducted upfront from the release, so the money that lands is the loan minus the interest.
- 🧮 Your loanable amount keys to your average Monthly Salary Credit: one month of your 12-loan average for the smaller tier, two months for the bigger tier, so a higher declared MSC as an OFW directly raises what you can draw.
- 🌏 OFWs apply and repay without flying home: the application runs inside My.SSS, the repayment duty is monthly without fail, and the payment channels include the My.SSS portal, the mobile app, and country-specific rails like PaySG in Singapore.
- ✅ Tonight-action: log into My.SSS, open Loans > Salary Loan, and let the portal compute your exact loanable amount from your posted record, because the portal reads your real contribution history and answers in one screen.
The SSS salary loan is the Philippines’ cheapest formal credit, and the feature most OFWs pay into for years without ever testing, usually because the eligibility rules look opaque and the repayment-from-abroad route looks risky. Both fears dissolve once the rules are laid out plainly. This guide covers the eligibility table, the interest mechanics (with the upfront-deduction rule that changed how the release lands), the loanable-amount formula, the exact application path inside My.SSS, and the repayment channels that work from overseas, with the October 2026 LoanLite microloan as the SSS salary loan alternative for members short of the classic thresholds. The rules read stricter from a distance than they render on screen, and the SSS salary loan rewards exactly one habit: a contribution schedule kept current long before the need arrives. Every figure here is dated, and the FAQ names what triggers a refresh.
SSS Salary Loan Eligibility: the Two-Number Test
Eligibility for the SSS salary loan rests on posted contributions, not on income proof. The test, as of 2026:
| Requirement | One-month loan | Two-month loan |
|---|---|---|
| Posted monthly contributions | 36 or more | 72 or more |
| Recent activity | 6 posted within the last 12 months before application | |
| Standing | No penalty condonation claimed in the past 5 years (for the good-standing rate) | |
| Current employer delinquency | Employed members apply only if the employer is current on remittances | |
Voluntary members and OFWs meet the same thresholds because the rule set is member-class-neutral, which is the point most OFW guides miss: as long as the 36 (or 72) contributions are posted and 6 of the last 12 are live, the loanable tier is yours to request. The SSS contribution table piece shows how the OFW floor (a ₱8,000 MSC) builds those posts at ₱1,200 per month.
How Much You Can Borrow: the MSC Formula
The SSS salary loan amount keys to your Average Monthly Salary Credit (AMSC), the average of your 12 latest MSCs.
- One-month tier: equal to your AMSC, with a program-maximum that the My.SSS screen computes for you.
- Two-month tier: two monthly credits, twice the first tier, for members who clear the 72-post threshold.
- The OFW lever: because OFWs declare their own MSC between the ₱8,000 floor and the ₱35,000 ceiling, the declaration you chose when registering sets the loan ceiling years later, which is why under-declaring a MSC to save on contributions cheapens both the future loan and the future retirement claim.
A worked shape: an OFW declaring a ₱20,000 MSC holds a 12-loan AMSC of ₱20,000 and reaches the one-month tier near ₱20,000 before deductions, subject to the program ceilings My.SSS shows. The portal computes the exact figure from the posted record, so treat manual arithmetic as an estimate only.
The Interest Mechanics: 8% a Year, Deducted Upfront
Two rules define what actually lands in your account. First, the rate: the salary loan charges 8% per annum (0.67% monthly) for members in good standing, the rate set in the 2025 reform cycle and carried through 2026. Second, the deduction timing: under Circular 2026-005, issued August 4, 2026, the interest on a salary-loan application is deducted upfront from the release, and the official program page confirms the monthly amortization duty. A quick worked example keeps the numbers plain: on a ₱20,000 one-tier draw at the 24-month schedule, the first-year interest is roughly ₱1,600, so the released amount sits near ₱18,400 before any advance-amortization offset the screen applies. The exact release lands in your registered disbursement account, and the same screen lists the amortization schedule so you can see every due date before you accept.
The standing advice follows from those numbers: the salary loan is cheap relative to informal credit but not free, so borrow for a purpose with a deadline (tuition, medical, a family emergency covered by the plan your household finance routine already carries), not for a buffer you never spend. The loan is also a credit record: keeping it current builds the good-standing history that the next loan prices.
Applying From Abroad: the My.SSS Path
The SSS salary loan application never requires a Philippines trip:
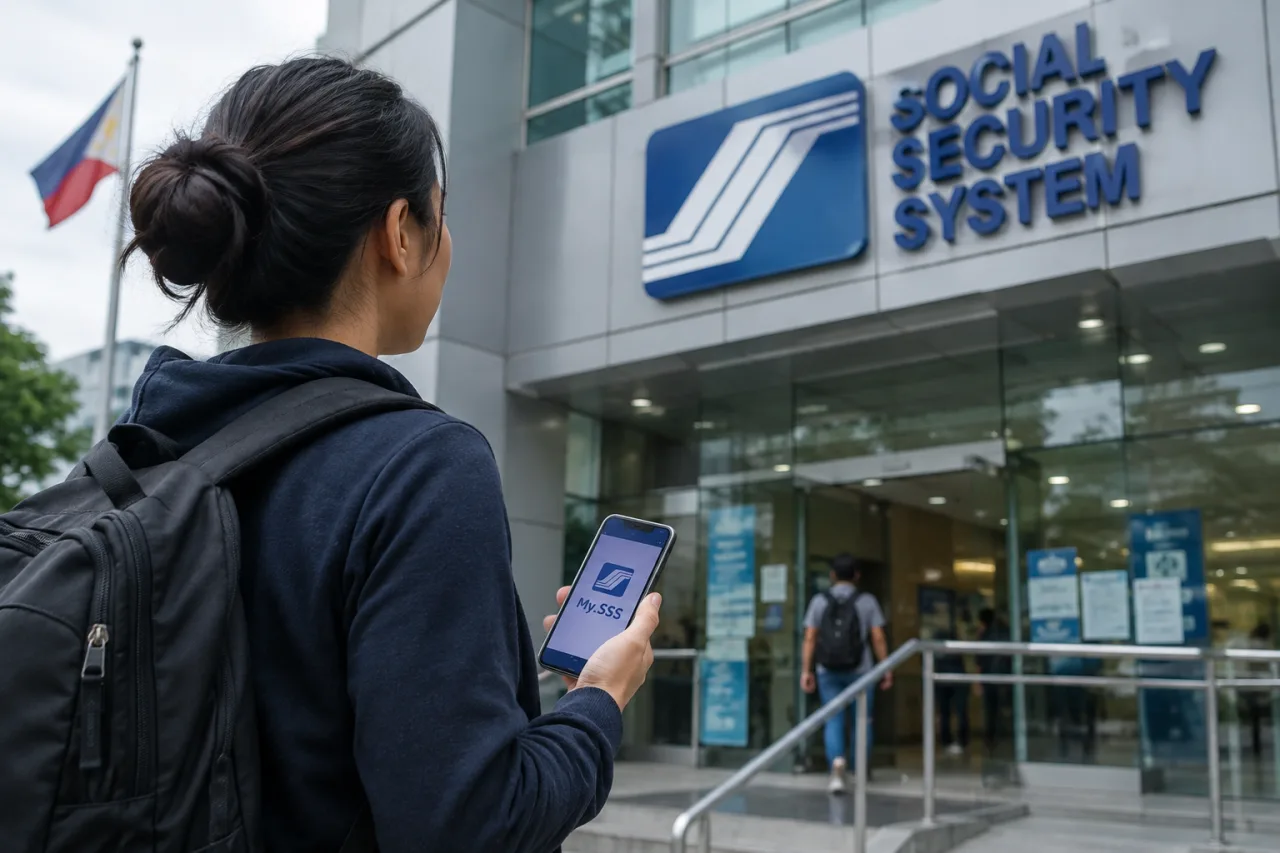
- Step 1: log in and check eligibility live. Inside My.SSS, open Loans, select Salary Loan, and the portal shows your tier, loanable amount, and rate with your real posted history.
- Step 2: confirm the disbursement account. The release flows to your enrolled bank or e-wallet account (UnionBank, GCash, Maya), so verify the account is active and in your name before submitting.
- Step 3: submit and read the schedule. Accept digitally, and the amortization schedule shows each due date; the standard term runs to 24 monthly payments beginning on the second month of the loan.
- Step 4: keep the reference. Save the loan number for the payment step, and screenshot the schedule for your household finance file.
The whole flow runs in minutes from any country, and the same account handles contribution payments, which is why the 7-channel payment guide and the loan flow belong on the same bookmark bar.
Repaying From Overseas: Channels and the OFW Duty
The official rule for voluntary members, non-working spouses, and land-based OFWs: the monthly amortization falls due without fail, and the member pays through an authorized channel. The working rails:
- My.SSS portal and mobile app: direct e-payment against the loan number, the default route most OFWs keep.
- Country rails: Singapore’s PaySG and similar SSS-authorized overseas collecting partners in other markets take PHP-denominated payments against your account.
- Local partners from home: some OFWs schedule payments through a trusted family member with the loan number, but the member of record owns the loan until it closes, so the safest habit is the direct rail.
Missed payments accumulate penalties on the outstanding balance and damage the standing that your next loan prices, so the durable pattern is an automatic reminder tied to each due date. The OFW loan legit-check guide covers what to do when a collector or fixer contacts you about an SSS account, including the registry sweep that separates official notices from impostors.
The October 2026 Microloan: the Smaller Alternative
Members short of the 36-post threshold gained a new door on October 2, 2026: the SSS microloan facility, with amounts from ₱1,000 to ₱20,000 keyed to the average of the 12 latest MSCs, launched to bring small-denomination credit inside the system, per the SSS announcement. The facility targets exactly the population the classic salary loan excludes (newly registering OFWs, reactivated members, first-generation contributors), and it runs through the same My.SSS account. For a member 20 posts short of the one-month tier, the microloan covers urgent small needs while the contribution routine matures, and the two products share the same credit record, so the microloan paid on time helps the next loan’s standing.
What Breaks the Loan, and What Fixes It
- Under-declared MSC. The declaration sets the ceiling; a member who declared the floor in 2023 and wants ₱40,000-tier credit in 2026 raises the MSC by increasing contributions going forward, and the AMSC improves as new posts land.
- Stale records. Unposted contributions (wrong SBR references, unclaimed payments) shrink the visible history; the reconciliation habit from the payment guide prevents it.
- Penalty condonation history. Members who availed a condonation inside the last 5 years pay the standard rate rather than the good-standing rate, which is the difference between 8% and the legacy pricing.
Renewals, Upgrades, and the Second Loan
The SSS salary loan is a repeatable facility, and its rules reward members who run it cleanly. An SSS salary loan renewal becomes available after the required share of the outstanding amortizations is paid, and the renewal settles a slice of the prior balance while the new draw extends forward, so members who need a larger amount across two years often use two sequential loans instead of waiting for the two-month tier. The upgrade route works differently: a member who availed the one-month tier and crossed the 72-post threshold since can request the two-month tier at renewal, and the My.SSS screen shows both the renewal capacity and the tier options in the same panel. The cleanest pattern the record supports: keep a small running loan paid on schedule, let the good-standing history price your renewals at the 8% rate, and hold the two-month tier in reserve for genuine large needs, because credit used slowly is credit available when it counts.
The second-loan etiquette matters for the household too: the amortization lands on the same date every month, so fold it into the remittance rhythm the family already runs, and never route it through a fixer. Families that manage an SSS account across borders should also brief whoever helps with paperwork at home, because the loan is the one SSS facility where the repayment discipline shows up in every future quote, from the next salary loan to the eventual claim smoothness.
The Salary Loan Against the Alternatives
The plain compare for an OFW planning a ₱10,000-to-₱40,000 need:
| Route | Typical cost | The trade |
|---|---|---|
| SSS salary loan | 8% a year, upfront-deduction, 24-month schedule | Requires posted history; builds credit standing |
| Savings-first | Zero interest, slower | Delays the need; the PERA route grows the buffer |
| Informal lenders | Steep, opaque, no paper trail | Fast and risky; no credit benefit, collector exposure |
| SSS microloan | 8% annual on smaller draws | The bridge for members below the classic thresholds |
The table’s bottom line echoes the guide’s spine: the SSS salary loan wins on cost and on the standing it builds, the savings route wins when the need can wait, the microloan wins when history is thin, and the informal route should lose every comparison it enters. The PERA account guide covers the savings-first lane, and the loan-legit-check sweep keeps whichever route you choose inside the official walls.
One last calibration closes the guide: loan features move slowly, but they do move (the 2025 rate reform and the 2026 upfront-deduction circular both shifted the economics inside two years), so the maintenance habit is one check per quarter inside My.SSS, reading the Loans panel with your real record. Eligibility, amount, and rate all render there against your own contributions, which makes the portal answer faster and more accurate than any recalculated table on the internet.
FAQ
How much is the SSS salary loan for OFWs?
The one-month tier keys to your average of the 12 latest Monthly Salary Credits and the two-month tier to double it, subject to program ceilings the My.SSS screen computes from your posted record. An OFW declaring a ₱20,000 MSC approximates a ₱20,000 one-tier draw before the upfront interest deduction.
What is the interest rate on an SSS salary loan in 2026?
8% per annum (0.67% monthly) for members in good standing, and the interest is deducted upfront from the release under Circular 2026-005 issued August 4, 2026. Good standing means no penalty condonation inside the past 5 years.
Can an OFW get an SSS loan without going home?
Yes: the application runs inside My.SSS, the release lands in your enrolled disbursement account, and repayment flows through the portal, the mobile app, and authorized overseas rails like PaySG in Singapore. No step requires a trip to a branch.
How many contributions do I need?
36 posted monthly contributions for the one-month loan, 72 for the two-month loan, plus 6 posted within the last 12 months before applying. The posted-history test, not income documentation, drives eligibility.
What happens if I miss a payment?
Penalties accumulate on the outstanding balance and the record loses good standing, which prices your next loan higher and blocks future renewals until settlement. If arrears are already large, the settlement programs SSS periodically opens are the lawful reset, and the loan legit-check guide separates official notices from impostor collectors.
Is the new microloan worth it instead of the salary loan?
For members short of the 36-post threshold, yes: the October 2, 2026 microloan facility lends ₱1,000 to ₱20,000 on the same 8% annual pricing and builds the credit record while contributions mature. For members who already clear both thresholds, the classic salary loan’s higher ceiling serves larger needs better, and the same My.SSS account shows both offers side by side.
- Official sss.gov.ph/wp-content/uploads/2026/08/CI2026-005-External.pdf — Circular 2026-005
- Official sss.gov.ph/salary-loan — official program page
- Official sss.gov.ph/news-and-updates/sss-encourages-members-to-avail-of-new-mi… — SSS announcement
External sources linked in this article, in order of first mention. Spotted an error or a broken link? Tell us.
Cite this pagePublished Nov 12, 2026
Agron, E. (2026, November 12). SSS Salary Loan 2026: the 8% Rate, the Eligibility Test, and the My.SSS Route From Abroad. WorldNgayon. https://worldngayon.com/sss-salary-loan-ofw/
Agron, Edmon. “SSS Salary Loan 2026: the 8% Rate, the Eligibility Test, and the My.SSS Route From Abroad.” WorldNgayon, 12 Nov. 2026, worldngayon.com/sss-salary-loan-ofw/.
Agron, Edmon. “SSS Salary Loan 2026: the 8% Rate, the Eligibility Test, and the My.SSS Route From Abroad.” WorldNgayon, November 12, 2026. https://worldngayon.com/sss-salary-loan-ofw/.
Agron, E. (2026) ‘SSS Salary Loan 2026: the 8% Rate, the Eligibility Test, and the My.SSS Route From Abroad’, WorldNgayon, 12 November. Available at: https://worldngayon.com/sss-salary-loan-ofw/.
E. Agron, “SSS Salary Loan 2026: the 8% Rate, the Eligibility Test, and the My.SSS Route From Abroad,” WorldNgayon, Nov. 12, 2026. [Online]. Available: https://worldngayon.com/sss-salary-loan-ofw/
@online{agron2026ssssalary,
  author       = {Agron, Edmon},
  title        = {{SSS Salary Loan 2026: the 8\% Rate, the Eligibility Test, and the My.SSS Route From Abroad}},
  year         = {2026},
  date         = {2026-11-12},
  organization = {WorldNgayon},
  url          = {https://worldngayon.com/sss-salary-loan-ofw/},
  urldate      = {}
}TY - ELEC AU - Agron, Edmon TI - SSS Salary Loan 2026: the 8% Rate, the Eligibility Test, and the My.SSS Route From Abroad T2 - WorldNgayon PY - 2026 DA - 2026/11/12/ UR - https://worldngayon.com/sss-salary-loan-ofw/ Y2 - ER -
Cite the version you read; the page may be updated. Zotero and Mendeley can also import this page directly.