Table of Contents
Digital Remittance Explained: How Money Actually Moves From Dubai to Manila
Digital remittance explained in one walk-through: your ₱/$ journey has four legs — the sender’s app converts and dispatches, a rail (bank network, card system, or stablecoin ledger) carries the value, a payout side delivers cash or credit, and fees plus FX spread come off mostly in the middle, where you can’t see them | the ₱50-billion-a-year fee bill and the 2% cap debate are fights over that middle | same corridor, four rails, four different prices — the piece maps each
Key Takeaway
- 🗺️ Every remittance is four legs: send (convert and instruct), carry (bank network, card rails, wallet ledger or stablecoin ledger), pay out (bank credit, wallet, cash pickup), and the fee sandwich — the visible charge plus the hidden FX spread.
- 🧾 The hidden cost usually out-sizes the visible one. A “zero-fee” transfer can still lose 2-4% at the exchange-rate mark-up; comparing apps on fees without comparing mid-market-rate deviation is how overpaying happens.
- 🚄 The rails are converging: traditional correspondent banking, card networks, e-wallet ecosystems (GCash-style direct-to-wallet delivery) and now stablecoin ledgers all compete on the same corridor — regulators count the difference (our BSP peso-stablecoin piece is the policy corner).
- 🛡️ The fee fight is now political: the drive to cut the global average cost of sending money home runs through exactly the four legs mapped here — and the ₱50-billion-a-year Philippine number makes the arithmetic personal.
- ⚠️ Explainer, not advice: this piece maps mechanisms and costs; it does not recommend any provider or corridor choice.
Remittances are the quiet giant of the digital economy, and yet the mechanics of a digital remittance stay invisible exactly where they matter most: in the fees. Digital remittance — money sent home through apps instead of over-the-counter windows — still costs the world’s senders an average of multiple percentage points per transfer, and the Philippine corridor alone absorbs roughly fifty billion pesos a year in charges, which is why the two-percent cap debate keeps surfacing in Manila. This piece answers the question most senders have never had answered plainly: when you press send on an app, where does the money actually go, and at which of the four legs does the cost get taken? Follow the dollars and pesos leg by leg — send, carry, pay out, and the fee sandwich — and the pricing differences between corridors stop being mysterious. They become a map you can read.
Leg One: Digital Remittance Begins at the Sender’s App — Conversion and Instruction
Everything starts with an instruction: who receives, where, and in what form — bank deposit, wallet credit, cash pickup, or home delivery. Behind that instruction the app does two jobs. Convert: the sender’s currency is exchanged into the destination currency at a rate the provider sets — and here sits the first and least visible cost: the spread, the gap between the mid-market rate quoted on any finance site and the rate the app actually gives you — the mechanism behind the mid-market-rate principle every provider prices against. A transfer can be labeled “fee-free” while the provider earns 2-4 percentage points inside the rate. Comply: KYC checks, sanctions screening and anti-fraud rules execute here — the compliance layer that justifies (and prices) the onboarding each provider runs. The app then dispatches an instruction to its payout network; nothing has physically moved yet — what has moved is a claim, which the next leg must settle.
Leg Two: the Rails — Four Ways to Carry Value Across a Border
- Correspondent banking: the classic system. Money rides interbank message networks between the sender’s bank, intermediary banks, and the receiving bank — reliable, regulated, and the slowest of the four: settlement can take one to three business days and each intermediary may take a cut, which is why the legacy corridor is the expensive baseline the newer rails attack.
- Card networks: where the payout side is a debit-card credit, the value rides card rails — faster than correspondence (often same-day, sometimes instant into the receiving account) with fees set by the network scheme and the issuers on both ends.
- Wallet-to-wallet ecosystems: closed-loop transfer inside one provider’s wallet universe (or between partnered wallets) — the sender deposits into the ecosystem, the beneficiary receives wallet credit instantly, and cash-out happens at the receiving end through the provider’s own agent and partner network. This is the rail most OFW families use daily, because the last meter to a Philippine household is a wallet QR, not a bank teller.
- Stablecoin ledgers: the newest leg. Value moves as a token on a public ledger — dollar or peso-denominated — settling in minutes at close-to-zero marginal cost, with conversion to local currency at the destination. The corridor economics are transformative where volumes are large; the open questions are regulatory custody and conversion discipline, which is why central banks — tracked globally by the BIS, and the BSP’s peso-stablecoin project foremost in our coverage — build supervised versions rather than ban the idea.
Read the four rails together and the industry’s price differences explain themselves: correspondent banking charges by the hop; card networks charge by scheme; wallets charge inside their own loop; stablecoin rails charge for conversion on and off the ledger — mostly at the edges. The same corridor priced on different rails can differ by several percentage points end-to-end, which is precisely the gap the fee-difference pieces on this desk keep measuring.
Leg Three: the Payout Side — Where the Family Actually Gets It
Delivery is the digital remittance’s own cost center. Bank credit lands in the receiving account but banks in the receiving market can apply their own receiving fees or delays. Wallet credit is near-instant and free to hold, with cash-out priced by the wallet’s own schedule — the visible and invisible charges at the family’s end of the pipe. Cash pickup through agent networks carries the highest payout-cost profile of the three — physical cash, security, premises, commissions — which is exactly why the industry’s cost debate and the push toward wallet-first delivery are the same conversation. Home delivery exists in thin corridors and prices accordingly. The payout leg is also where the remittance’s timing risk lives: the money is “sent” the moment leg two settles, but the family’s access waits on the payout operator’s own cut-off windows and holiday calendars.
Leg Four: the Fee Sandwich — Where the Number Actually Gets Taken
Add the legs up and the total cost of a digital remittance is a sandwich of four layers: the flat fee (what the app shows you), the FX spread (what it doesn’t), the rail charges on the middle (what the correspondent chain or scheme takes), and the payout-side charges (what the receiving end applies). The industry’s digital remittance transparency push — every “fees compared” table we publish, the the World Bank’s migration and remittances data brief and regulators’ dashboards, the corridor-level averages — exists to force those four layers into one visible number. The desk’s standing counsel, now permanent: compare in mid-market deviation. Take the amount you send, divide what the family actually receives, subtract the same calculation at the mid-market rate, and the true cost of the corridor appears — usually two to six points, sometimes worse on legacy rails, occasionally remarkably thin on the new ones.
The Corridor Walk-Through: a Digital Remittance From Dubai to Manila
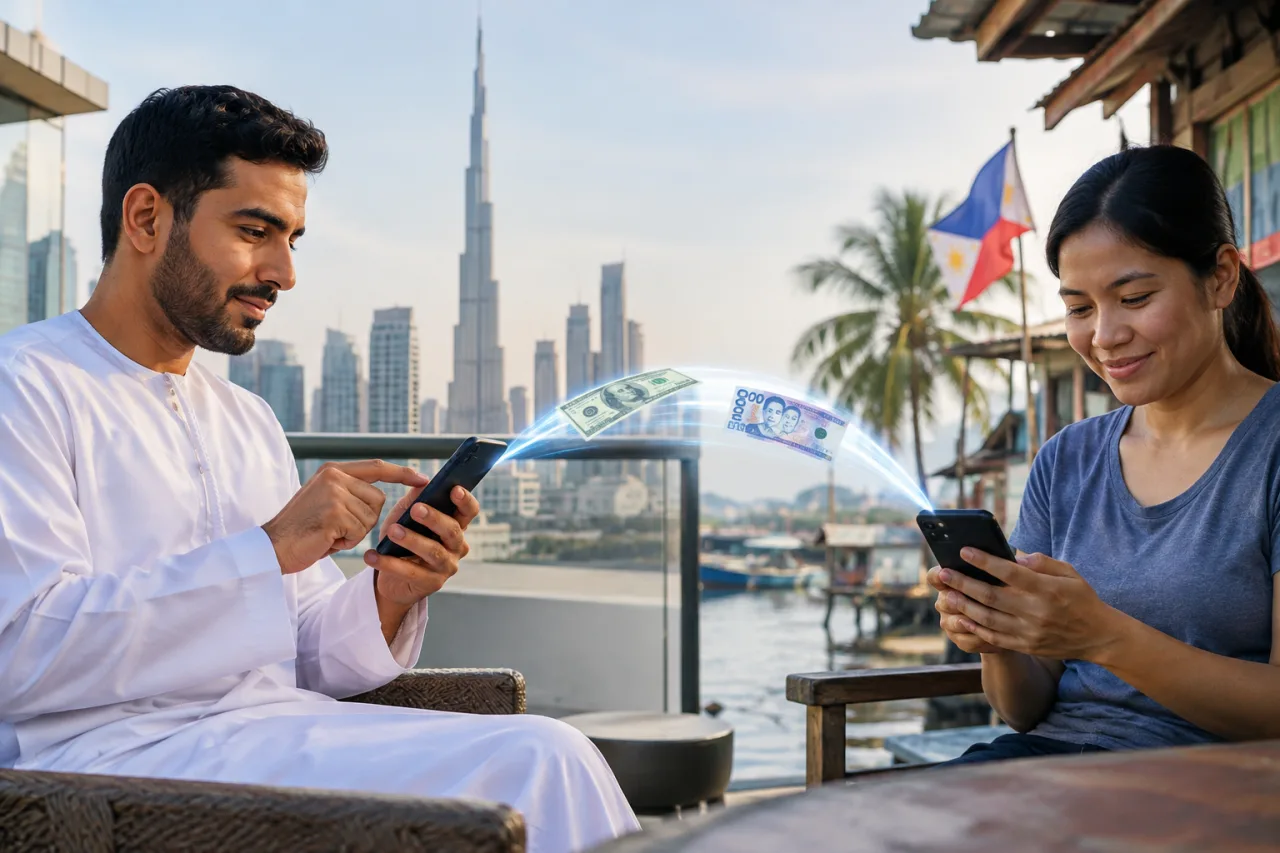
Make the legs concrete with the corridor the title promises — a digital remittance from Dubai to Manila, with figures labeled as an illustrative walk-through, not a quote. A sender in the UAE instructs the app to deliver ₱29,000 for a family’s rent. Leg one: the app quotes dirhams-to-pesos at a rate slightly off mid-market — the spread — and debits the sender. Leg two: depending on the provider, the value rides one of four rails: a correspondent chain through two banks (one to three business days, intermediary cuts), a partnered wallet loop (minutes, one ecosystem), a card-rail credit (same-day), or — the newest — a stablecoin ledger transfer that settles in minutes and converts at the Philippine end. Leg three: delivery — wallet credit lands instantly and cash-out costs per the wallet’s own schedule; bank credit takes the receiving bank’s cut and cut-offs; cash pickup at an agent costs the provider the most. Leg four: nobody shows you this one — the fee sandwich closes around whatever the flat fee hid, the spread took, the middle leg charged, and the payout applied.
Now compare corridors on the same ₱29,000 instruction. On the most modern wallet loop with a competitive rate, the family receives near the full peso figure — the true cost lands in the tenths of a percent. On a legacy bank-to-bank path, the same instruction can lose one-to-three points across the middle legs before the payout side touches it. On an app priced “zero fee, market rate,” the word “market” is doing heavy lifting: the deviation from the real mid-market rate is the charge. This is why the desk insists on mid-market-deviation comparisons in every remittance piece — the walk-through explains the four legs, and the comparison method converts each leg’s toll into one visible number.
Why the ₱50-Billion Digital Remittance Fight Is Happening Exactly Here
The Philippines’ roughly ₱50-billion-a-year digital remittance fee bill sits on these four legs, which is why the policy fight (the proposed cap on charges documented in the peso-63 playbook alongside the fee-cut guide) is really a fight about leg two and leg four: legacy correspondent chains and agent-heavy payout networks are the expensive machinery, and every upgrade — wallet credits, direct-to-bank rails, and eventually supervised peso stablecoins — attacks the middle. The trend line that matters to a monthly sender is therefore structural, not promotional: each year, more of the corridor moves onto rails where the marginal cost of the carry is near zero, and the fee sandwich compresses at the middle first. The sender’s practical move in the meantime is the same as the regulator’s: price the whole sandwich, rail by rail, and let the map decide.
FAQ
What is digital remittance in simple terms?
Sending money home through digital channels — an app, a wallet, or a bank transfer — instead of an over-the-counter window. The mechanics are four legs: the sender’s app (convert and instruct), a carrying rail (bank, card, wallet, or stablecoin ledger), the payout side (bank credit, wallet, or cash), and the fee sandwich that comes off along the way.
Why do fees differ so much between remittance apps?
Because each provider prices its own combination of the four layers: some take a large flat fee and a thin FX spread, others advertise zero fees and earn at the exchange-rate mark-up, wallet-loop players subsidize the transfer to win the float, and legacy correspondent rails pay intermediaries along the way. Comparing the amount-received at the same amount-sent across corridors reveals the real differences.
What is the FX spread on a remittance?
The gap between the mid-market exchange rate and the rate the provider actually gives you. It is the most commonly hidden charge in digital remittance — a “fee-free” transfer priced at a rate two percent away from mid-market effectively charges two percent per transfer. The mid-market rate is publicly quoted on any finance site, so the spread is checkable in seconds.
How long does a digital remittance take?
Depends on the rail. Wallet-to-wallet inside one ecosystem: usually instant. Card-rail payouts: often same-day. Standard bank-to-bank through correspondent chains: one to three business days. Stablecoin-ledger corridors settle in minutes, with the conversion to local currency at the receiving end.
Are stablecoin remittances safe?
The rails are fast and cheap, but safety depends on the issuer’s reserves and redemption discipline (see our stablecoins explainer) and on how the corridor converts the token to pesos at payout — the custody and conversion layers carry the risk, not the ledger speed. Supervised versions like the BSP’s peso-stablecoin project exist precisely to put regulation around those layers.
How can I pay the least to send money home?
Price the whole sandwich: check the app’s flat fee, compare the amount received against the mid-market rate, read the receiving-side charges, and prefer the newest rail available in your digital remittance corridor — wallet credits and supervised digital rails have compressed the middle leg the most. Our remittance-fees coverage keeps the corridor arithmetic current.
Financial Disclaimer: This article is an educational explainer for general information only — it is not investment, remittance or financial advice, and does not recommend any provider, corridor or product. Fees, exchange rates, spreads and delivery times change without notice and vary by corridor, amount and provider; verify every figure on the provider’s own channels on the day you send. Consult a licensed financial adviser for personal decisions. worldngayon.com holds no position in and is not affiliated with any provider named; it is not liable for outcomes from actions taken on this content.
Sources: the desk’s own filings-based coverage — the ₱50-billion remittance-fee analysis and the 2% cap bill; the BSP peso-stablecoin remittance-rails project; corridor pricing mechanics per provider-published schedules and the industry regulators’ cost-transparency frameworks; stablecoin-settlement mechanics per the stablecoins explainer on this desk.